
Mainfreight (NZSE:MFT) Could Be 19% Undervalued Following Strong Half Year Results
Why Mainfreight’s latest half year results matter
Mainfreight (NZSE:MFT) has put fresh numbers on the table after releasing half year results to 30 September 2026, giving investors new detail on revenue, profit and earnings per share.
Mainfreight’s latest half year update lands after a strong run in the share price, with a 9.10% 1 month share price return and 5.87% over the past week. The 1 year total shareholder return of 9.09% points to momentum that has been gradually rebuilding despite a weaker 5 year total shareholder return of an 8.70% decline.
Scan how Mainfreight’s earnings momentum compares by lining it up against our curated 193 high quality undervalued stocks built around strong cash generation and solid balance sheets.
After a sharp move higher on strong half year numbers, Mainfreight now sits at an interesting junction. Is most of the gain already in the price, or is there meaningful upside still on the table as valuation gets tested next?
Price-to-Earnings of 23x: Is it justified?
On valuation, the spotlight is on Mainfreight’s P/E. The stock closed at NZ$71.46, and at that level trades on a P/E of 23x that sits between its own estimated fair level and what peers are paying.
The P/E metric compares the current share price to earnings per share and gives you a shorthand view of how much investors are willing to pay for each dollar of profit. For a logistics and freight operator like Mainfreight, this ratio often reflects expectations around future volume, pricing power and how efficiently its network converts revenue into earnings.
Based on the data, Mainfreight’s P/E of 23x is below the estimated fair P/E of 27.4x. That suggests the current price is lower than the level our fair ratio work points to, and the gap is not small. Against peer averages, the picture flips. The same 23x multiple is below a peer group average of 44.5x yet above the Global Logistics industry average of 14.7x. This indicates the market is assigning a premium to this business relative to the broader sector while still pricing it below a tighter peer set. If the market leans more heavily toward the fair ratio over time, that P/E level could be an anchor investors keep in mind.
Explore the SWS fair ratio for Mainfreight.
Result: Price-to-Earnings of 23x (ABOUT RIGHT)
Still, the recent 1 month return of 9.10% and a richer P/E load expectations onto Mainfreight, while a weaker 5 year shareholder return signals sentiment can reverse quickly.
Find out about the key risks to this Mainfreight narrative.
Another view on Mainfreight’s valuation
The P/E points one way, but the SWS DCF model pulls in the opposite direction. On that cash flow view, Mainfreight at NZ$71.46 trades above an estimated future cash flow value of NZ$64.66, which frames the stock as overvalued on this method.
This gap between earnings based and cash flow based checks leaves a simple question for you. Which lens do you trust more when profit quality, growth forecasts and required returns do not line up neatly with today’s price: the headline multiple, or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
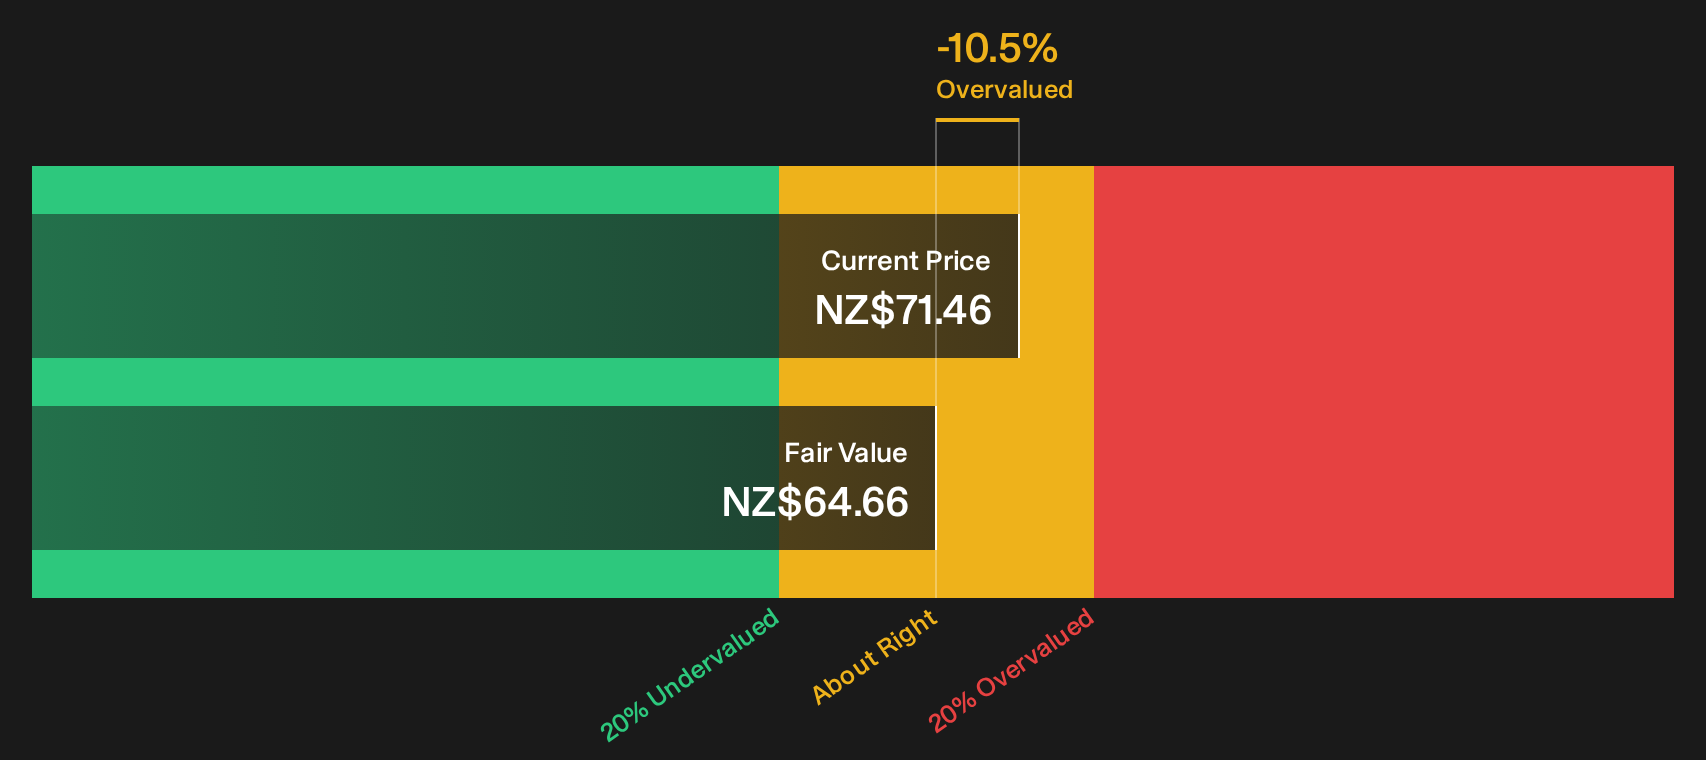
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mainfreight for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 193 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether this upbeat read on Mainfreight matches your own instincts about the business and its valuation? Move quickly, look through the numbers yourself, and weigh them against the fact that our work highlights 1 or more potential upsides that investors are already watching. To see what those are in detail, start with the 2 key rewards
Looking for more investment ideas beyond Mainfreight?
If Mainfreight has sharpened your focus, do not stop here. Expand your watchlist with targeted ideas that fit clear goals around value, income and resilience.
- Hunt for underappreciated quality by scanning a 193 high quality undervalued stocks that blends strong fundamentals with pricing that still looks reasonable.
- Build a cash flow focused portfolio by reviewing a 218 dividend fortresses that aims to combine income strength with stability.
- Strengthen your downside protection by filtering for a 207 resilient stocks with low risk scores that keeps volatility and financial risk scores in tighter check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com