
Learn Why The Bull Case For Atlanticus Holdings Stock Could Change Following Earnings Jump
- Atlanticus Holdings reported third quarter 2026 net income of US$95.35 million and sharply higher earnings per share versus a year earlier, alongside stronger results for the first nine months of 2026.
- The company also put a US$1b universal shelf registration in place, giving management wide flexibility to issue equity, debt or hybrid securities across multiple structures.
- We will now explore how Atlanticus Holdings' sharply higher quarterly earnings could reshape the existing investment narrative around growth and risk.
Scan how Atlanticus Holdings' latest earnings jump and new US$1b shelf registration compare with other potential breakout stories in our hand picked 20 high quality undiscovered gems list.
Atlanticus Holdings Investment Narrative Recap
To own Atlanticus Holdings, you need to be comfortable with a lender focused on near prime and underserved borrowers, where credit performance can change quickly if essential living costs rise. The sharp step up in net income and earnings per share in the third quarter highlights operating leverage, but it does not remove core sensitivities around delinquencies, funding access and Mercury integration.
At the moment, the key near term swing factor is whether the combined Mercury platform and record solicitation activity can continue to translate into attractive unit economics without pushing risk too far. The biggest threat remains any mix of weaker consumer payment behavior, softer response rates or more expensive funding, which could squeeze margins even if reported earnings remain high.
The US$1b universal shelf registration is the announcement that matters most for this story. It gives Atlanticus Holdings board approval to issue a broad range of securities, including common and preferred stock, debt, warrants and units, as opportunities or needs arise. That tool can interact directly with the funding risk that the analyst consensus Narrative on Simply Wall St highlights.
For investors, the question is how this new flexibility might influence execution of the Mercury integration, receivables growth and second look point of sale expansion. A shelf can support balance sheet capacity if securitization or warehouse markets become less friendly. However, it also introduces potential dilution or higher interest costs if used, which ties directly back into the key catalysts and the overall risk reward trade off.
Atlanticus Holdings' narrative projects US$5.3b revenue and US$425.7m earnings by 2029. This assumes 85.5% yearly revenue growth and an earnings increase of about US$226.5m from US$199.2m today.
Uncover why Atlanticus Holdings' fair value indicates a 57% potential upside to its current price that could narrow quickly.
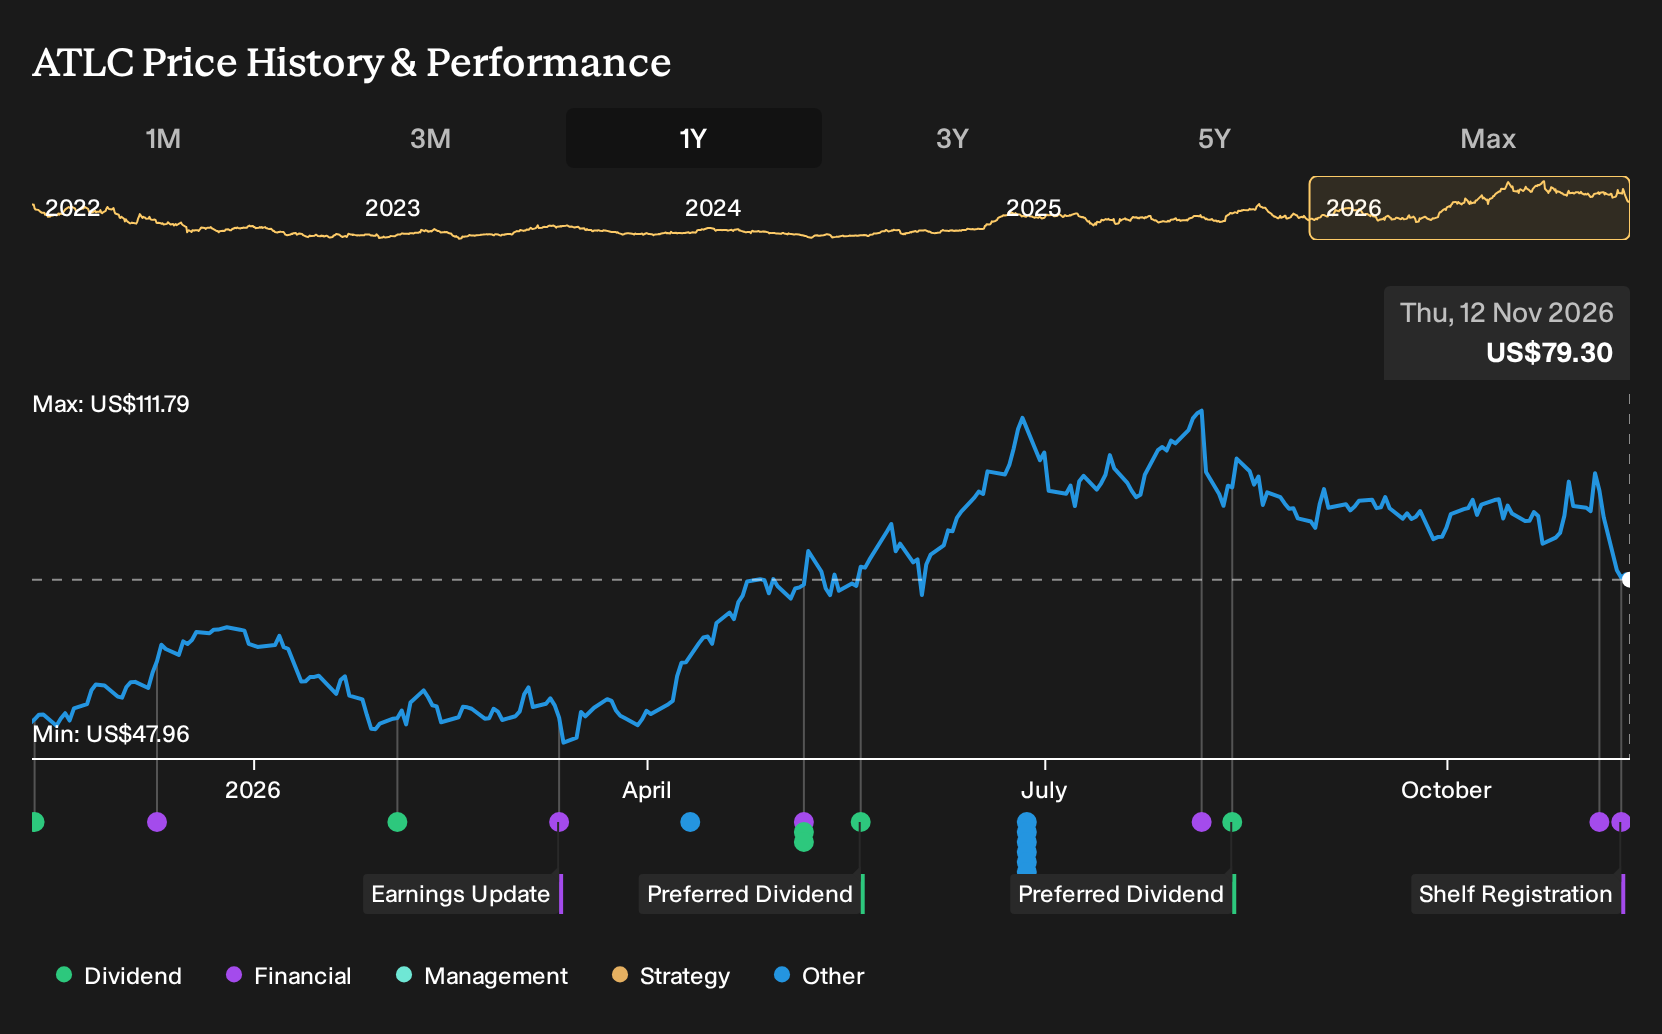
Exploring Other Perspectives
One bullish twist on Atlanticus Holdings focuses on funding rather than credit. The most optimistic analysts pointed to the first AAA ABS ratings and tighter spreads as a possible earnings engine, with forecasts up to US$5.5b revenue and US$523.8m earnings by 2029. Those projections predate this earnings jump and the new US$1b shelf, so you may want to compare how your own view of funding risk or opportunity lines up across several scenarios.
Explore 4 other Atlanticus Holdings fair value estimates, including one that suggests as much as 125686% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Atlanticus Holdings research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Atlanticus Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlanticus Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Atlanticus Holdings?
If this Atlanticus Holdings update has sharpened your view on risk, growth and funding, it can be helpful to set it alongside other companies with very different profiles. The Simply Wall St Screener lets you compare these stories in a structured way and quickly spot which ones deserve a place on your watchlist.
- For investors hunting for potential mispricing backed by solid fundamentals, start with a focused set of 32 high quality undervalued stocks that may warrant a closer look.
- If resilience matters most to you, filter for companies that score well on financial strength using a curated list of solid balance sheet and fundamentals (23 results) that you can review side by side.
- When capital preservation and smoother return profiles are the priority, consider a targeted 29 resilient stocks with low risk scores that can help you narrow down steadier options.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com