
Is Imperial Oil (TSX:IMO) Expensive After Strong Earnings And A Completed Buyback?
Imperial Oil (TSX:IMO) just reported strong third quarter and year to date earnings, alongside steady dividends and a completed share buyback. This gives investors fresh numbers to reassess the stock’s appeal.
Recent price action reflects that backdrop. Imperial Oil’s share price is up 48.56% year to date and the 5 year total shareholder return of 368.09% points to long running momentum, while the stock has eased slightly over the past quarter as investors digest the strong earnings, dividend affirmation and completed buyback at around CA$181.70 per share.
Scan how Imperial Oil’s earnings surge, dividend affirmation and completed buyback compare with peers by zeroing in on 5 high quality undervalued stocks with similar cash generation and balance sheet strength.
After a 48.56% year to date climb and a rich run over five years, Imperial Oil now forces a simple question. Is most of the upside already in the rear-view mirror, or does valuation still leave room ahead?
Most Popular Narrative: 10% Overvalued
Imperial Oil last closed at CA$181.70 compared with an analyst consensus fair value of about CA$165.59. The analyst consensus Narrative on Simply Wall St currently views the stock as ahead of its calculated worth, using a 6.44% discount rate and detailed earnings forecasts.
The numbers and this narrative’s view that Imperial Oil is fairly valued imply the share price already reflects both the company’s recent free cash generation and its commitment to return surplus cash through dividends and buybacks.
See why 32 investors see Imperial Oil as 10% overvalued.
Result: Fair Value of CA$165.59 (OVERVALUED)
Still, that fair value view can break if oil sands face tougher emissions rules that pressure margins, or if sustaining capital at Kearl and Cold Lake eats into free cash flow.
Find out about the key risks to this Imperial Oil narrative.
Another View: Cash Flows Point To Undervaluation
Analysts on Simply Wall St see Imperial Oil as about 10% overvalued against their CA$165.59 fair value. However, the SWS DCF model presents a different view. On that cash flow basis, the shares at CA$181.70 trade around 30% below an estimated value of CA$259.59. This raises a simple question: is the price reflecting earnings optics more than long term cash generation?
For a closer look at how those long term cash flows are modeled, and what assumptions sit underneath that CA$259.59 figure, Look into how the SWS DCF model arrives at its fair value.
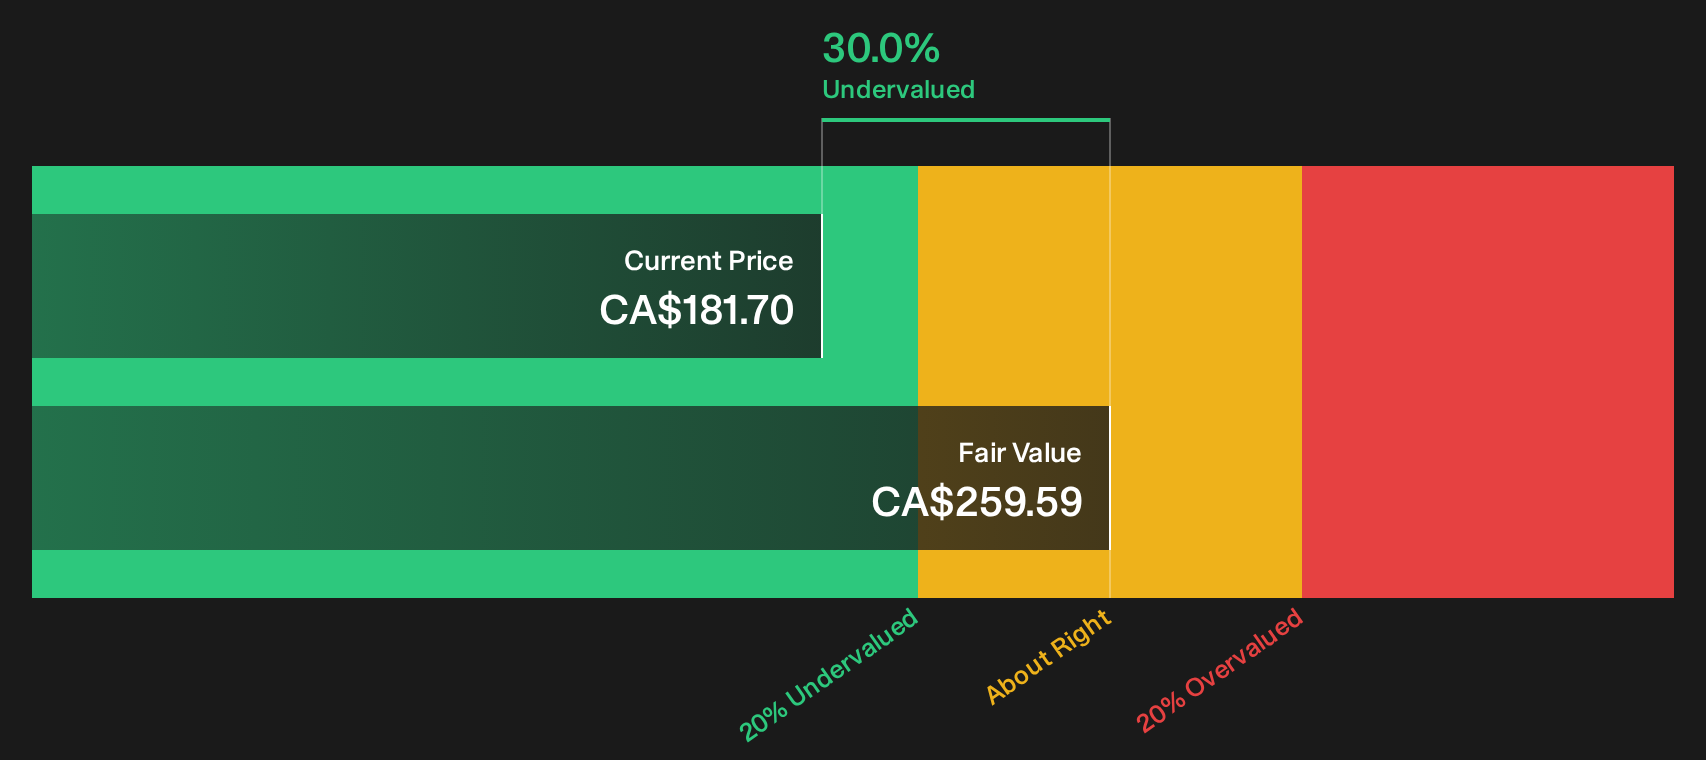
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Imperial Oil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and concern around Imperial Oil feels finely balanced, consider acting quickly and reviewing the data firsthand so you can form your own view, starting with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Imperial Oil?
If Imperial Oil has sharpened your focus on quality and pricing power, do not stop here. Cast the net wider and line up your next candidates now.
- Target resilient balance sheets and cut your research time by scanning a carefully filtered list of solid balance sheet and fundamentals (5 results) that already screens for financial strength.
- Hunt for potential mispricings and stress test your thesis against a curated 5 high quality undervalued stocks that combines quality metrics with valuation checks.
- Prioritize staying power over drama and shortlist ideas from a focused 9 resilient stocks with low risk scores built around lower risk scores and sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com