
Health 160 (02656): Received a double bet from Barclays+Southbound Funding. Is the inflection point for large-scale commercialization of AI healthcare imminent?
On October 29, the stock price of Health 160 (02656) showed significant changes. The biggest increase in the company's stock price reached 37.42% within one hour of opening in early trading. The biggest increase after noon trading was further raised to 57.51%, and finally closed up 45.88%.
The reason for this is that Barclays PLC increased its holdings of the company by 24.182 million shares at an average price of HK$3.18 per share on the same day, involving approximately HK$76.927,800. The positive trend vane actions of international investment banks have led many funds in the market to follow the bullish trend, and Health 160 has recently ushered in a market that has been out of business for a long time.
From the start of the explosion to contraction and retreat, where will the stock price go?
Affected by the lifting of the ban in September of this year combined with shareholders' holdings reduction, Health 160's stock price clearly retracted in September and October. It is easy to see from the market that during this period, the market almost drove its stock price from a high level of about HK$7.5 before the ban was lifted to the HK$2 range in the second half of October using a single logic of “reducing holdings is bad”.
The Zhitong Finance App observed that on October 7, the stock trading volume of Health 160 shrunk drastically to 146,800 shares; then, the company's stock price continued to fluctuate and fall slightly. On October 14, when the company's stock price fell by only 1.91%, the single-day trading volume reached 54.817,500 shares, showing a round of market sell-off and concentrated release of the market during the period when the ban was lifted. It can be seen that before Barack was listed, the exhaustion of Health's sales within 160 markets can be traced.
On October 27, Health 160's share price hit an intraday low of HK$2.10. The single-day trading volume once again shrunk from the previous high to less than 8 million shares, which means that most of the upper chips in the market have been cleared. According to the chip distribution for the day, Health 1,60's on-market chips were mainly concentrated near the HK$2.14 support level, and the peak chip price was far below the average cost of holding HK$6.52. This chip structure gave Barclays a better opportunity to enter the market.
Although Barclays ultimately chose to enter the market at a trading price of HK$3.18, which is nearly 50% above the support level, it can still obtain a considerable risk-return ratio due to the fact that the Health 160 stock price continues to be low.
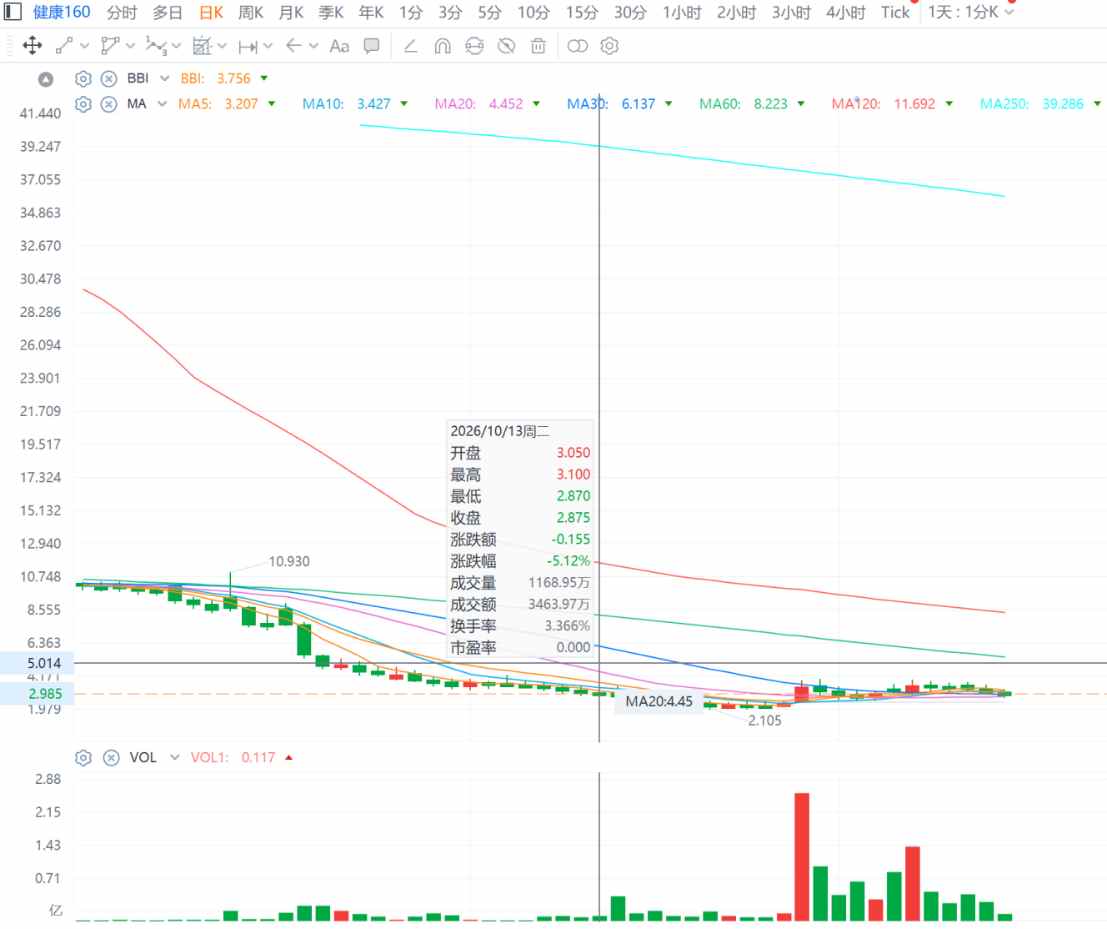
Judging from the market situation after Barclays was listed, after the outbreak began on October 29, there was an obvious high level of disagreement in the Health 160 stock price starting the next day.
From October 30 to November 3, the intraday turnover rate fell from 34.5% to 16.5% and then rebounded to 24.9%. The corresponding share price fluctuation reached 15-25%, indicating that during this period, there were drastic changes in the market, and the phenomenon of loss of profit trading and acceptance of new capital occurred at the same time.
After the first round of full chip exchange, it is clear that the Health 160 market is not over. From November 4 to 6, the company's stock price showed a second attempt to boost the current market. On November 6, Health 160's intraday stock price rose to 21.92% and closed up 12.96%. The stock turnover rate reached 46.81% on the same day, and the daily turnover reached 163 million shares. However, while OBV peaked simultaneously on the same day, Health 160's second peak attempt did not drive the single-day volume to a new high, and its performance was still below the peak on October 29.
Following the confirmation of the short-term “double top” structure, Health 160's stock price experienced a continuous contraction decline from November 9 to November 13, with an average daily volume contraction of more than 50% compared to the previous high.
Looking at technical indicators, the recent “five consecutive negative” performance brought Health 160 back below the 5-day EMA, showing short-term signs of pressure. However, the 20-day EMA and SAR medium-term trend lines have not yet been broken through, and the RSI14 index is still in the strong zone above 50. As a result, Health 160 is still in a relatively healthy short-term retracement phase. Even though it sold more than 40 million shares in a single day and closed down 7.41% on November 12, it did not break through the confidence of the bulls in the market.
On November 3, the company's single-day turnover shrank again, and sales continued to dry up. This usually indicates that the decline in the company's stock price at this time is more limited by liquidity factors rather than active selling pressure from within the market.
Under this trend, if the subsequent company's stock price continues to shrink and stabilize near the 20-day EMA and shows an upward trend, it is expected that a new round of steady rebound will begin.
Southbound capital continues to increase, betting on the inflection point of AI medical commercialization
On March 31 of this year, the National Health Insurance Administration officially included 12 AI-assisted diagnosis programs in the national unified medical insurance category B catalogue and simultaneously implemented them in 837 top three hospitals across the country, making China the first country in the world to integrate AI diagnosis into the national health insurance system on a large scale. This breakthrough on the medical insurance payment side has opened up the “last mile” of AI medical commercialization, and the industry generally believes that it will significantly accelerate the transition of products from R&D to normalized clinical use.
In fact, this is only a microcosm of the accelerated implementation of domestic AI medical commercialization policy support.
According to the Zhitong Finance App, as early as October of last year, five departments including the National Health Commission jointly issued the “Implementation Opinions on Promoting and Standardizing the Development of “Artificial Intelligence+Healthcare” applications, which clarified the schedule for widespread application of AI assistance at the grass-roots level in 2027 and basic full coverage by 2030. This also means that the domestic AI medical commercialization support policy has been upgraded from a “directional statement” to a “clear schedule+opening up payment channels+setting up assessment nodes”, making this concept a more definitive investment theme.
Back to Health 160, its uniqueness is that the company's business simultaneously places the three core links of hospital-side entrance, profit sharing of AI operations, and delivery of computing power infrastructure. With the support of domestic policies, the monetization rate in these multiple areas continues to increase, and as a result, Health 160 has become an optional target under the AI medical commercialization theme.
In terms of fundamentals, Health 160's 26H1 financial report shows that its current revenue increased 9.7% year on year to 319 million yuan, and net profit to mother reached 21.37 million yuan, a sharp increase of 111.18% year on year. This is a horizontal comparison of A-share peers Runda Healthcare and Anbiping. Health 160 has already reversed overall losses, taking the lead in showing a fundamental inflection point.
On September 16, Health 160 issued an announcement announcing that its indirect wholly-owned subsidiary signed a strategic cooperation framework agreement with an enterprise computing power infrastructure service provider in Shenzhen, with an estimated total cooperation amount of 650 million yuan. On October 13, the company announced the official implementation of the first 42 million yuan sales contract under this framework.
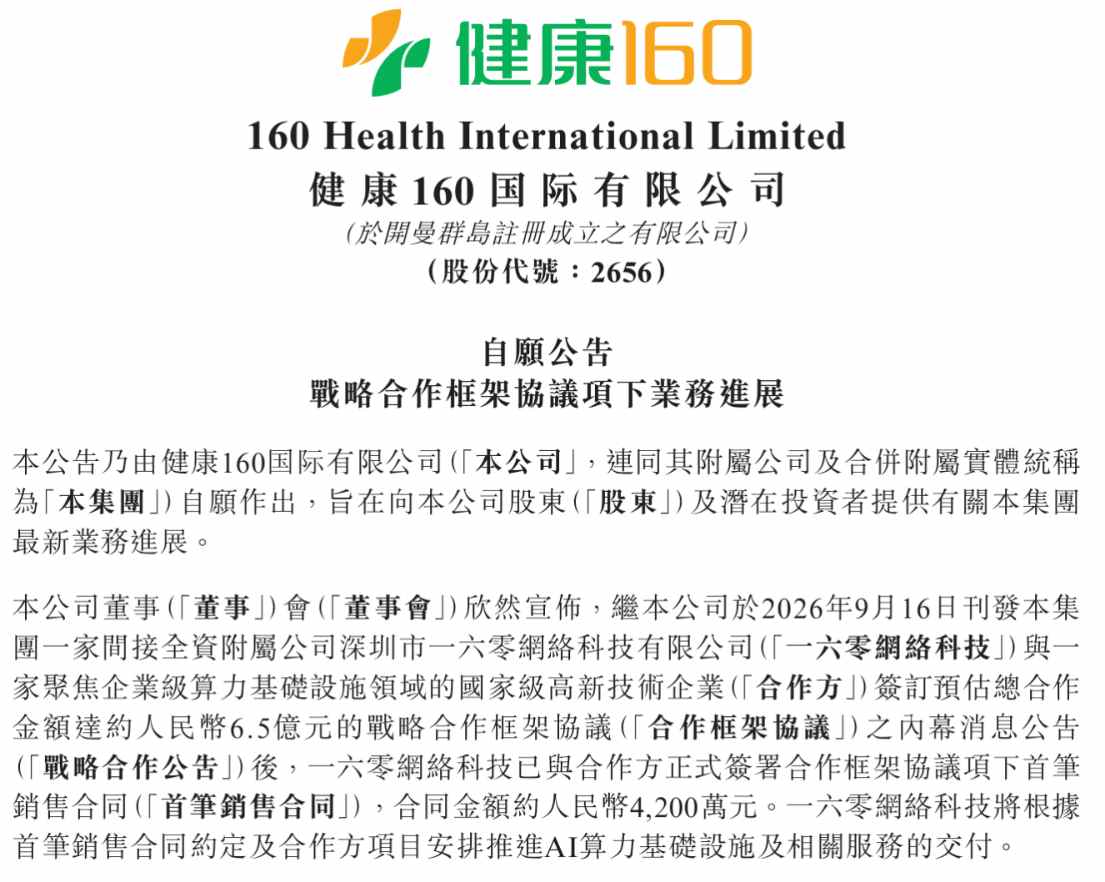
In fact, Health 160's initial AI computing power order of 42 million accounts for only 6.4% of its revenue for the full year of the previous year, but this still represents the shift of the company's digital healthcare solutions business with a gross margin of over 80% from computing power infrastructure to the fulfillment stage. Subsequent Barclays and Southbound Capital formed a “cross-verification” position at the low stock price of Health 160, which became the strongest external sign of its current market.
The Zhitong Finance App observed that between September 17 and September 22 after the disclosure announcement on September 16, Southbound Capital achieved a net purchase of 17.79,000 shares of the company within 4 trading days, of which 15.581 million shares were purchased in a single day on September 22, driving the overall shareholding ratio to jump from 11.34% to 13.88%.
According to broker transaction data for the past 20 days, the top five net buying brokers of Health 160 were Hong Kong Stock Connect (Shanghai), Hong Kong Stock Connect (Shenzhen), China Merchants Wing Lung Bank, Haitong International, and Hong Kong and Shanghai HSBC, which had net purchases of 16.672,800 shares, 5.7355 million shares, 3.8253 million shares and 3,0377 million shares respectively. It can be seen that the net purchases of the two major Hong Kong Stock Connect channels in the past 20 days accounted for 64.39% of the total volume of the top five buyers.
In fact, over this period, southbound capital continued to buck the trend and sweep the market at Health 160, and basically followed the left-hand side trading strategy of “increasing positions during a sharp decline and pullback, and reducing holdings when the growth rate is too fast”. As of November 12, its shareholding ratio in Health 160 had reached 22.47%.
In terms of shareholding costs, the average cost of Southbound Capital after weighted estimates since September 16 was about HK$3.9, while Barclays's listing price was HK$3.18. The average cost of opening a position on these two channels is clearly higher than the current stock price of Health 160.
However, the reference value of the cost of opening a position through these two channels is a pricing anchor that provides an external perspective. This pricing is anchored in the possibility that the gross margin of the digital medical business will continue to rise after Health 160, and the expectation that computing power orders will move from a framework to large-scale delivery.