
Blackstone (BX) Stock Looks Fairly Valued As Shares Fell 25% YTD
Blackstone has had a rough stretch so far in 2026, with the stock down 25.4% year to date. This puts the focus squarely on whether the current share price lines up with the returns the asset manager earns on the capital it invests. For anyone looking at the pullback and the steady stream of new deals, the key issue is how those capital returns compare with what the market is asking you to pay today.
- The year to date decline of 25.4% raises the question of whether the recent reset in Blackstone's valuation properly reflects the return it generates on its sizeable pool of fee paying and balance sheet capital.
- Fresh commitments such as up to US$1.5b in funding for Pfizer's obesity drug program and US$3.1b tied to Mitsubishi's LNG Canada stake can reshape the mix and timing of cash flows, and may influence how sustainably Blackstone can keep compounding returns on its capital base.
- What if you looked at Blackstone through its earnings instead? See why Blackstone's 26.7x P/E tells a different valuation story.
The issue now is whether the stock's current price is supported by the returns Blackstone earns on the capital it commits across credit, real estate and other investments.
If you want to see how other companies handle the same question of whether the price matches the returns earned on capital, it helps to compare that pattern with 32 high quality undervalued stocks.
Where Does Blackstone Sit on Excess Returns?
The Excess Returns model looks at what Blackstone earns on its equity over and above the cost of that capital. On this view, the firm is modeled with an average Return on Equity of 46.70%, sitting on Book Value of $11.05 per share and a Stable Book Value of $12.23 per share. The framework also uses Stable EPS of $5.71 per share, with a Cost of Equity of $0.98 per share, which leaves an Excess Return of $4.73 for every dollar of modeled earnings.
That spread between what Blackstone is assumed to earn and what its equity is priced to require helps explain why the Excess Returns projections put the estimated intrinsic value broadly in line with the current share price of $118.54. The recent warning that Anthropic may carry a speculative grade credit rating despite its record IPO underscores why the market may still demand a healthy risk premium even when modeled excess returns look strong. The comparison between the implied value from these assumptions and where the market is actually trading is explored in more detail in the full Excess Returns output. Find out what Blackstone could be worth using our Excess Returns estimate.
The Blackstone Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Blackstone pick up where the valuation puzzle leaves off. They spell out which specific assumptions on growth, profitability and earnings would need to play out for Blackstone's share price to sit meaningfully higher or lower than it does today. Each narrative ties its number to a clear view on how growth, margins and risks might evolve from here, giving you something concrete to revisit as fresh information comes through.
Bulls see more runway left in Blackstone than the more cautious camp is willing to credit.
Bull case: 16% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on combined Street forecasts for Blackstone.
"The expansion of perpetual and multi asset vehicles such as BXMA, which has reached US$109b of AUM after 25 consecutive quarters of positive returns and recent fundraising, supports more recurring fee revenue…"
Discover why this Narrative puts Blackstone at 16% undervalued.
Bear case: roughly fairly valued
This angle follows the bearish analyst Narrative on Simply Wall St, which leans on the lowest targets and more cautious assumptions for Blackstone.
"While Blackstone is reporting strong firmwide inflows and profit growth, persistent net outflows in BCRED after repurchase requests exceeded the 5% quarterly limit and only about half were met could signal product fatigue in a flagship private credit vehicle that may cap future management and performance fees from this channel…"
Explore why this Narrative puts Blackstone at roughly fairly valued.
One more Blackstone clue that could change how you read the story
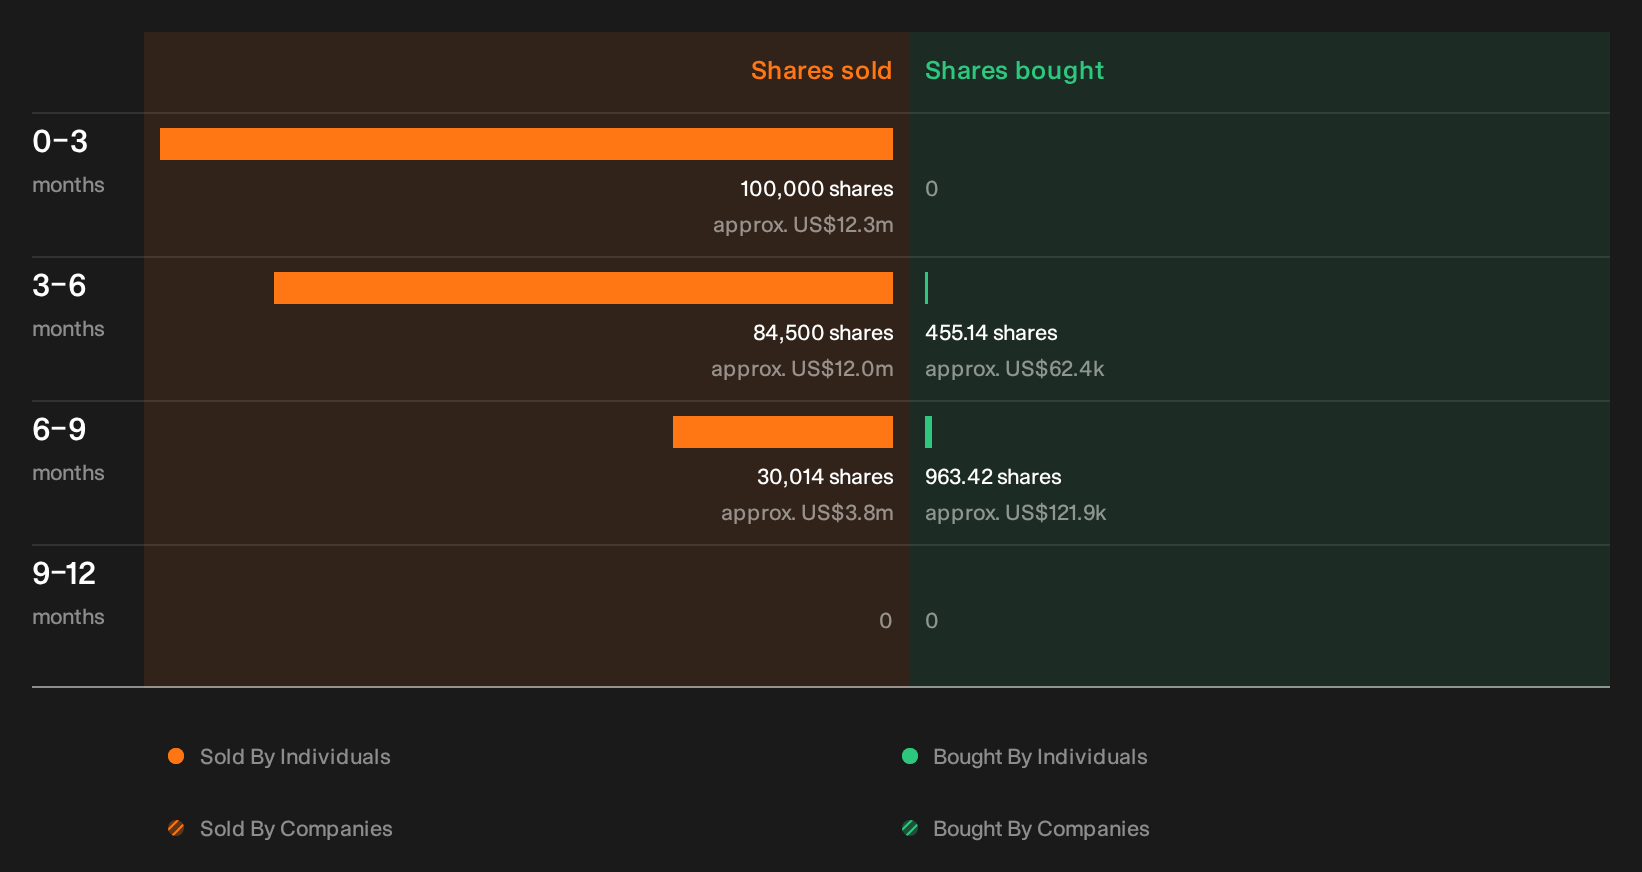
Valuation models tell you what the market might be pricing in, but recent trading by Blackstone insiders can hint at how those closest to the business are acting with their own capital. See the recent insider selling flagged for Blackstone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com