
How Earnings Turnaround At EchoStar (ECHO) Has Changed Its Investment Story
- EchoStar reported third quarter revenue of US$1,127.61 million and net income of US$2,782.25 million, with earnings per share returning to positive territory for both basic and diluted measures from continuing operations.
- The business also posted US$11,097.74 million in net income over the first nine months. This, along with improving AI driven efficiency at Sling TV and consumer promotions at Boost Mobile, has contributed to more optimistic analyst views on EchoStar's earnings power.
- We will now look at how EchoStar's sharp swing back to profitability could influence the broader investment narrative around the company.
What Is EchoStar's Investment Narrative?
To own EchoStar, you have to buy into a fairly simple idea. The group needs to turn its mix of pay TV, wireless and satellite assets into repeatable cash earnings, not just one off accounting gains. The swing to US$2,782.25 million in third quarter profit and US$11,097.74 million for the first nine months, alongside a P/E ratio of 2.9x, keeps attention on that earnings power story. Sling TV’s higher AI driven resolution rates and Boost Mobile’s holiday promotions speak to execution on cost and demand, which are key short term catalysts.
The tougher part is durability. Revenue over the first nine months, at US$8,371.26 million, sits below the prior year figure that was reported, while forecasts point to slower revenue growth and declining earnings over the next few years. That combination, plus capital needs across wireless and 5G, leaves little room for operational missteps if the recent profitability proves hard to repeat.
Even so, before treating EchoStar’s sharp profit rebound as a settled story, it is worth pausing on ...
There's only one way to know the right time to buy, sell or hold EchoStar. Head to Simply Wall St's company report for the latest analysis of EchoStar's Fair Value.
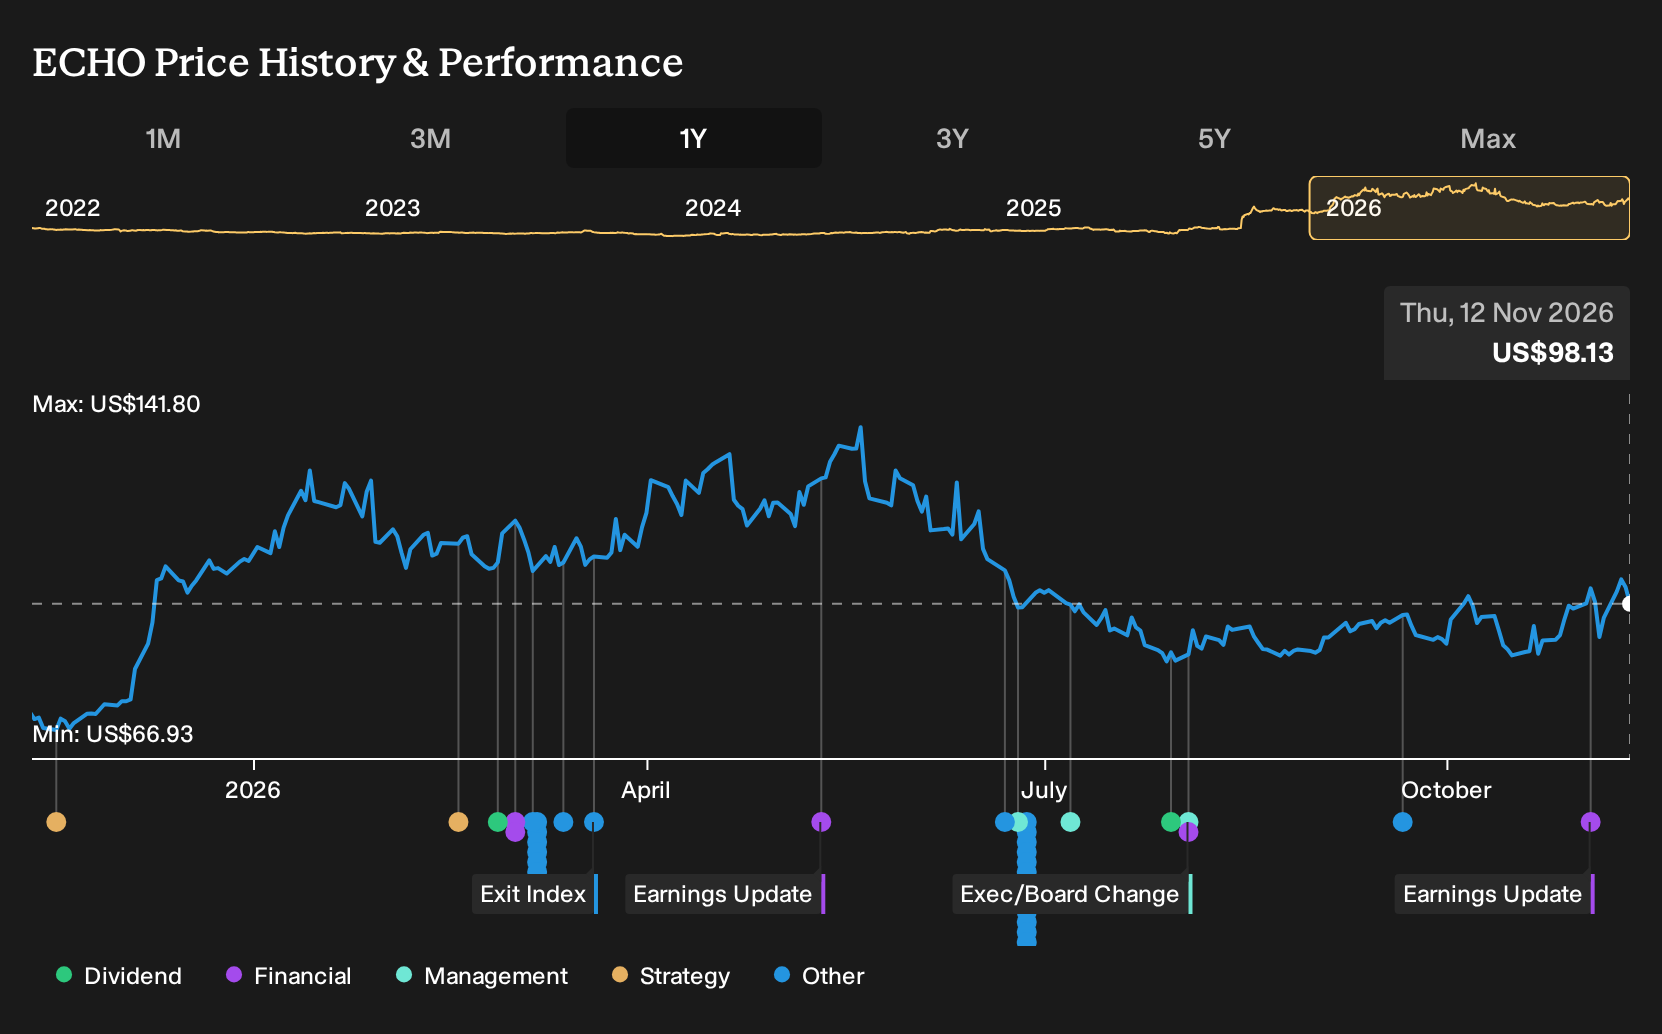
Exploring Other Perspectives
Pessimistic analysts focus on a different angle for EchoStar. They worry that restructuring risk and litigation around Hughes could eat into the roughly US$14b to US$15b cash pile that bullish forecasts lean on. Some of the highest pre news estimates still penciled in US$13.6b of 2029 revenue and US$467.1m of earnings, yet flagged real downside if cash is consumed. You should treat these spreads in expectations as a reminder that smart people can look at the same numbers and reach very different conclusions, so it is worth exploring several viewpoints before making up your mind.
Explore 5 other EchoStar fair value estimates, including one that suggests as much as 63% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your EchoStar research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for EchoStar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EchoStar's overall financial health at a glance.
Looking For More Investment Ideas Beyond EchoStar?
If EchoStar has sharpened your focus on where earnings resets and cash generation might matter most, it can help to scan other opportunities with clear, rules based filters before you commit fresh capital.
- If you want to focus on quality that the market might be overlooking, sort through a curated pool of strong fundamentals with the 20 high quality undiscovered gems.
- If capital preservation is top of mind, concentrate on sturdier balance sheets and steadier profiles using the 29 resilient stocks with low risk scores.
- If reliable cash returns appeal to you, narrow the field to higher yielding payout candidates with the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com