
Aya Gold & Silver (TSX:AYA) Stock Looks Fully Priced As It Sells A Project
Aya Gold & Silver has delivered a strong multi year share price run, even with a recent pullback, which naturally puts the focus on what investors are paying for its earnings today. With the stock still reacting to fresh mine news and portfolio moves, the question now is how firmly its current price rests on the profit engine behind it.
- Over the past 3 years the share price has climbed 272.1%, which puts a lot of weight on whether the company’s earnings can support that kind of re rating.
- Record production, profit growth and the planned sale of the Azegour project for an equity stake in Sama Resources may support expectations for a more focused portfolio and earnings power tied closely to Aya Gold & Silver’s Moroccan assets.
- Your read on Aya Gold & Silver is one view; the desks covering it have another. See what analysts think Aya Gold & Silver's shares could be worth.
The issue now is whether Aya Gold & Silver’s current share price is justified by the level and quality of its earnings.
If you are weighing whether Aya Gold & Silver’s earnings fully back today’s price, it can help to compare that question across 33 elite gold producer stocks
Is Aya Gold & Silver Getting Expensive on Earnings?
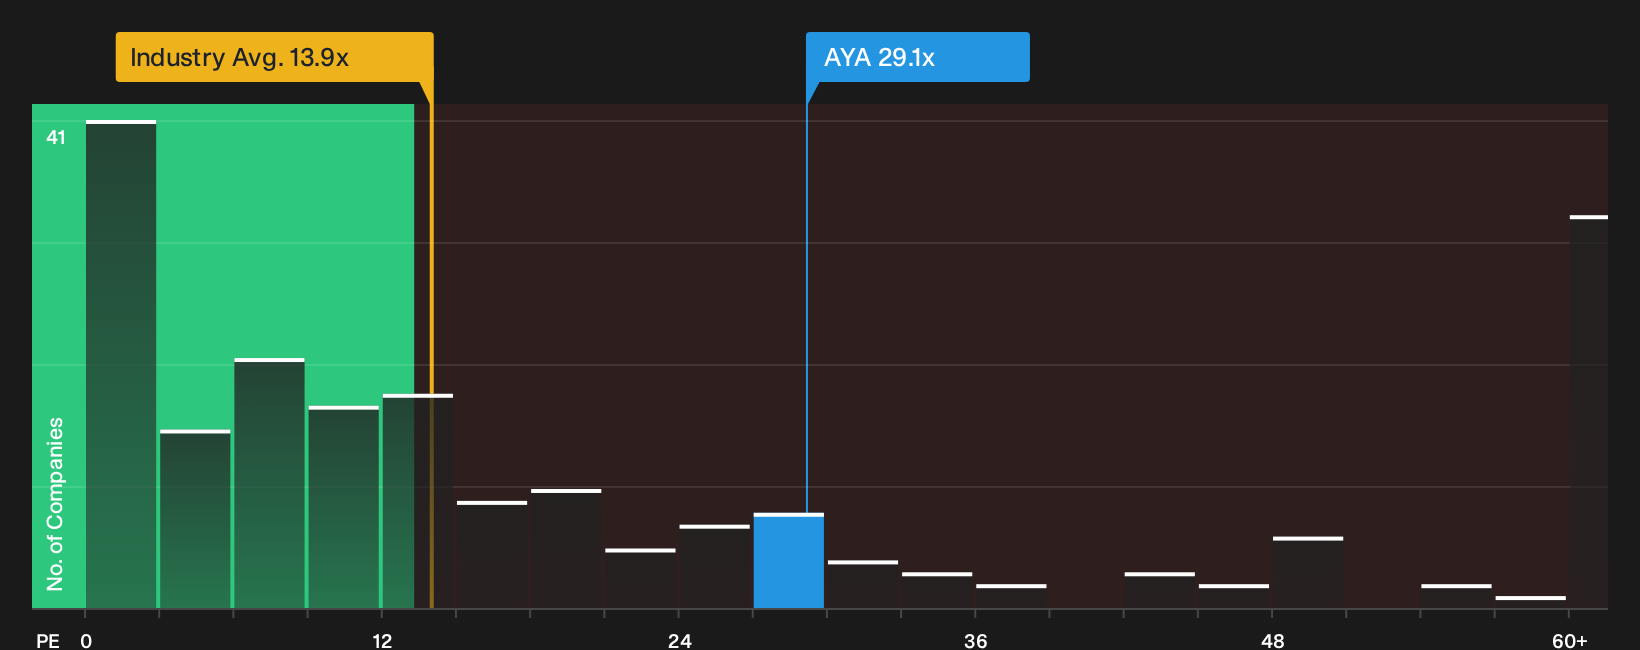
The P/E lens suits Aya Gold & Silver because investors are focused on how quickly its reported profits catch up with the share price. On this yardstick, the stock trades on roughly 29.1x earnings, compared with about 13.9x for the broader Metals and Mining industry and around 24.5x for its closest peers.
Recent news around record production and profit growth at Aya Gold & Silver helps explain why the market is willing to pay a premium. However, the current P/E still screens as overvalued versus the level suggested by a tailored fair multiple that factors in its growth profile, margins, size and risk. The fair benchmark comes out far lower than the live market P/E, because the model heavily penalises the company’s negative free cash flow track record and projected cash outflows. The gap is therefore better read as a warning that the stock prices in very optimistic outcomes on this framework rather than a precise target. Explore the numbers behind Aya Gold & Silver's P/E valuation.
The Aya Gold & Silver Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Aya Gold & Silver leaves off by spelling out the specific paths for growth, margins and earnings that would need to play out for the share price to look meaningfully higher or lower than it does today. Rather than relying on a single multiple or one model result, each narrative lays out the assumptions behind its view of value so you can judge them against Aya Gold & Silver's future reports as they arrive.
One of the top community narratives on Aya Gold & Silver: roughly fairly valued
According to heliogabal, a Simply Wall St Community investor who wrote the Narrative, Aya Gold & Silver is described as being focused on de risked production and silver exposure.
"AYA is a de risked production story with exceptional silver torque trading at a Morocco discount, with Boumadine providing free optionality for later years…"
Discover why this Narrative puts Aya Gold & Silver at roughly fairly valued.
Before you move on Aya Gold & Silver still has unanswered questions
Price tags and profit ratios only tell part of the Aya Gold & Silver story, and our broader checks have flagged specific areas of concern that deserve a closer look before you act. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com