
Erasca (ERAS) Gets Fast Track And Starts New Trial As Undervalued Case Stays Alive
Erasca (ERAS) is back in focus after fresh clinical and regulatory news around its pan RAS program, including the launch of a Phase 1/2 combination trial and the granting of FDA Fast Track status for ERAS-0015.
Erasca’s latest clinical updates are landing after a powerful run, with the share price up 339.55% year to date and the 1 year total shareholder return above 5x. However, the 90 day share price return declined 14.15%, and the 5 year total shareholder return is still slightly negative.
Capitalize on the surge of interest around Erasca's RAS-focused pipeline by scanning a curated set of oncology-focused opportunities in our 20 high quality undiscovered gems.The market now prices Erasca about 35% below the average analyst target after a huge run and widening losses. Is that a margin of safety or a warning sign as investors reassess the risk profile?
Most Popular Narrative: 35% Undervalued
Erasca last closed at $15.78, while the analyst consensus Narrative on Simply Wall St anchors fair value at $24.11. This frames a wide gap that the narrative links to RAS franchise expectations rather than near term earnings.
Planned initiation of three ERAS-0015 registration-enabling trials in second line and later non small cell lung cancer, frontline non small cell lung cancer with pembrolizumab and chemotherapy, and first line pancreatic cancer between 2027 and 2028 could expand Erasca’s addressable market and eventually influence revenue scale.
Early ERAS-0015 Phase 1 lung and pancreatic cancer data with objective response rates ranging from about 40% to 75% at pharmacologically active doses, combined with generally manageable safety and no treatment discontinuations for toxicity in key cohorts, positions Erasca to pursue broader clinical use that may support future revenue growth.
See why 2 investors see Erasca as 35% undervalued.
Result: Fair Value of $24.11 (UNDERVALUED)
Still, the bullish Erasca narrative could unravel if ERAS-0015 faces safety setbacks or if litigation over its data and patents materially constrains commercialization.
Find out about the key risks to this Erasca narrative.
Another Lens On Erasca’s Valuation
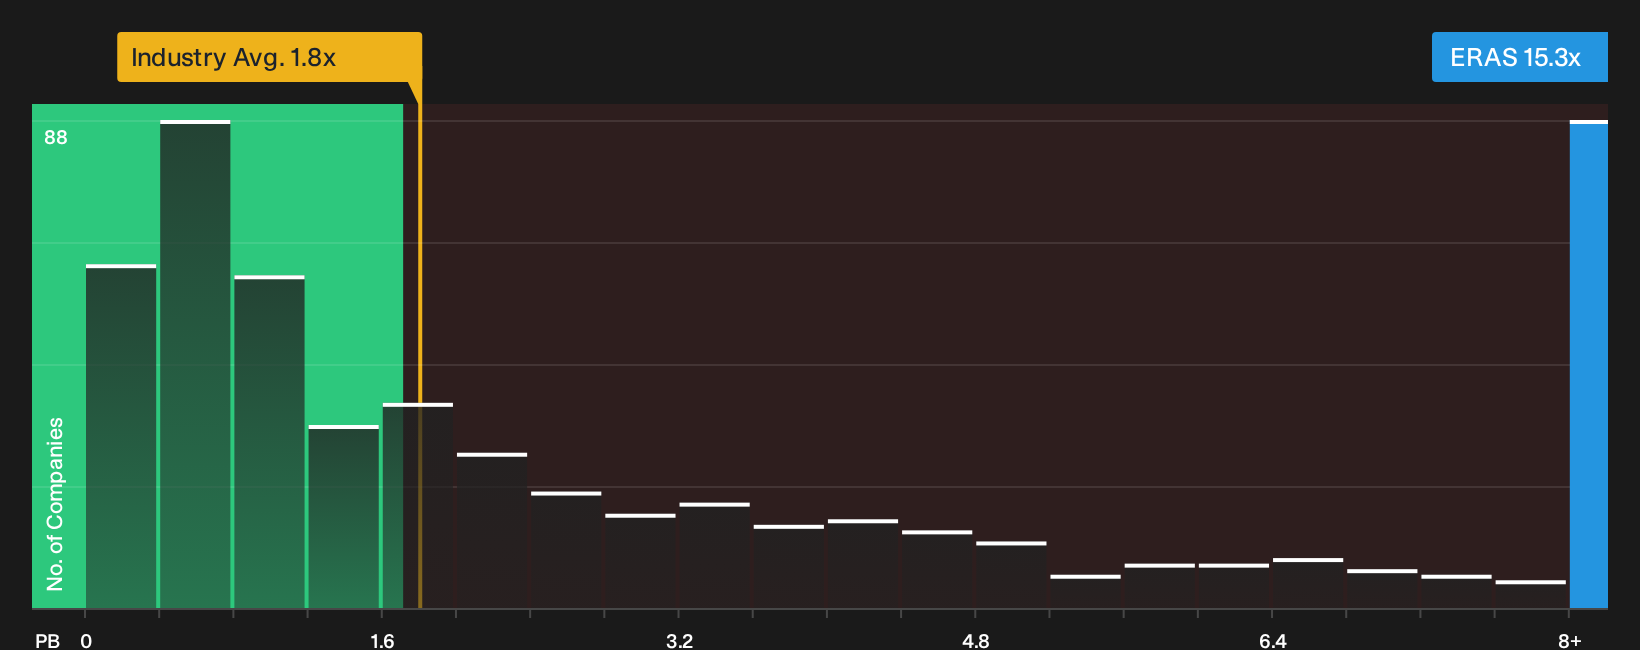
The analyst fair value of $24.11 suggests Erasca looks cheap on the story of future earnings, yet the market is paying a P/B of 15.3x versus 1.9x for the broader US Biotechs industry and 57.2x for close peers. That mix of premium to the sector but discount to peers raises a simple question: Is this pricing a cushion or a trap if expectations change?
To see how these book value signals line up with detailed assumptions on earnings power and risks, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Curious whether this mostly bullish Erasca story truly offsets the concerns around risk? Dig into the underlying data now and weigh the 3 important warning signs.
Looking For More Investment Ideas Beyond Erasca?
If Erasca has your attention, do not stop here. Broader context from other opportunities can sharpen your judgment and keep your watchlist one step ahead.
- Target potential upside in beaten down corners of the market by scanning 11 elite penny stocks with strong financials that pair tiny market caps with stronger fundamentals.
- Prioritise price discipline and business quality together by reviewing a curated mix of 32 high quality undervalued stocks that combine solid cash flows with sturdier balance sheets.
- Dial back portfolio stress and focus on resilience by checking 29 resilient stocks with low risk scores that score well on financial strength and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com