
How Investors May Respond To Netcompany Group Stock As AI Investment Call Begins
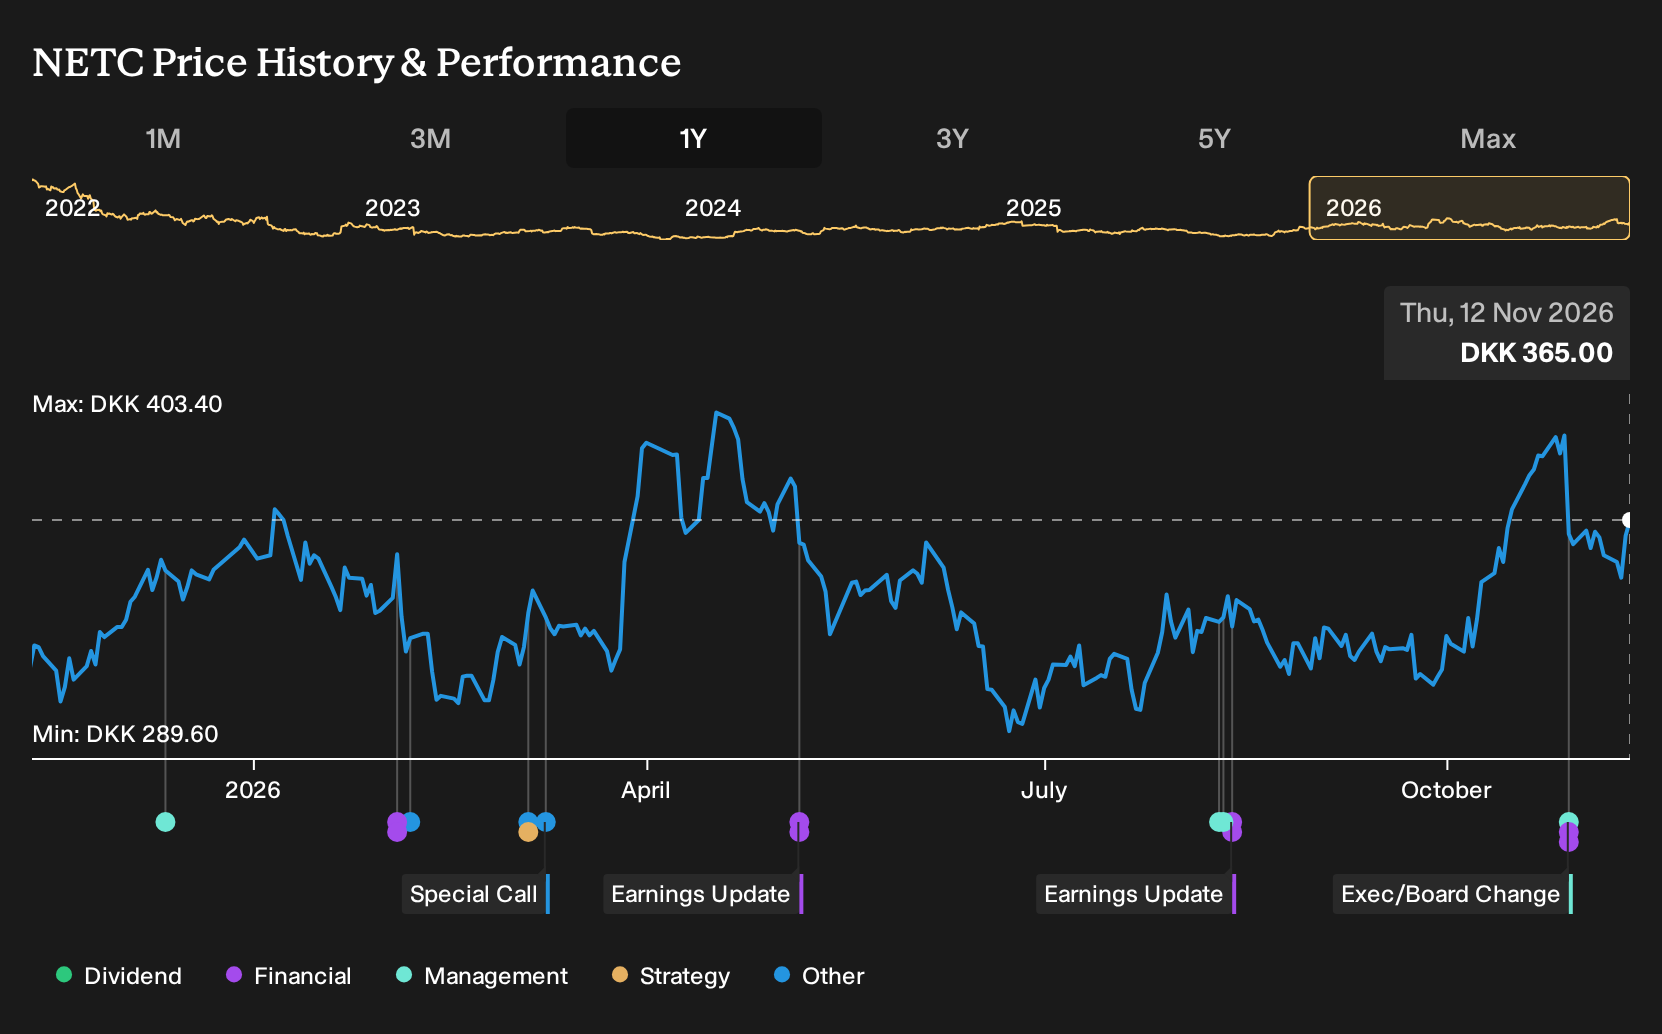
- Netcompany Group recently held a shareholder and analyst call to discuss its investment in Danish Centre for AI Innovation A/S, the company behind the Gefion AI supercomputer.
- The move connects Netcompany Group more closely to European AI infrastructure and this relationship could influence how it builds and delivers its digital platforms over time.
- Attention now turns to how Netcompany Group's investment narrative evolves as it backs the Gefion AI supercomputer through this AI focused partnership.
Scan how other AI focused infrastructure plays are shaping up by running your filters over 53 AI infrastructure stocks, aligned with moves like Netcompany Group's Gefion partnership.
Netcompany Group Investment Narrative Recap
To own Netcompany Group, you need to believe it can keep shifting more of its work toward higher margin platforms and AI enabled products while holding pricing power with European public and regulated clients. The analyst consensus Narrative on Simply Wall St leans on that mix change and on earnings growth running ahead of revenue growth. The Gefion AI supercomputer link fits that story but does not, on its own, reset the near term setup.
The more immediate swing factor still looks like execution on AI infused offerings such as Feniks AI, PULSE and Banking Services while keeping cost discipline as product and AI spending rises. The biggest risk right now is that heavier AI and development investment, combined with debt that is not well covered by operating cash flow, squeezes flexibility if demand softens.
With limited fresh announcements alongside the Gefion AI move, the key reference point remains management commentary that almost all recent customer conversations involve AI and that Feniks AI can cut IT development time by up to 45%. That operational detail matters more than the supercomputer headline for gauging how Netcompany Group can turn demand into actual project wins.
If Feniks AI and related platforms support larger, multi year contracts and higher revenue per employee, they line up directly with the catalysts in the analyst consensus Narrative on Simply Wall St around margin improvement and earnings growth. The risk is that elevated AI and product costs, plus compressed market sentiment after earlier target cuts, leave less room for error if those platforms do not scale as expected.
What The Current Forecasts Assume For Netcompany Group
Netcompany Group's current analyst storyline is built on revenue growth of 7.6% a year over the next three years, profit margins rising from 4.5% today to 11.2%, and earnings climbing from DKK 420.0 million today to DKK 1.3b by 2029, which is roughly a 3x step up in profit. In addition, analysts are working with a forecast that revenues reach DKK 11.6b and earnings land at DKK 1.3b in 2029, with the stock trading on a P/E of 15x instead of 42x today and with the share count shrinking by about 4% a year for the next three years.
Netcompany Group's narrative projects DKK 11.6b revenue and DKK 1.3b earnings by 2029. This implies 7.6% yearly revenue growth and roughly a 3x earnings increase from DKK 420.0 million today.
Uncover why Netcompany Group's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Netcompany Group’s margin risk rather than its AI opportunity. The most bearish analysts were only baking in about 6.7% annual revenue growth and DKK 1.3b earnings by 2029 before this Gefion AI supercomputer news. That is a much tougher storyline. Use it as a prompt to compare several competing forecasts before you decide how this new AI partnership might reshape the picture.
Explore 2 other Netcompany Group fair value estimates, including one that suggests it could be worth just DKK 357.70.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Netcompany Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Netcompany Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Netcompany Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Netcompany Group?
If the Gefion AI angle has you thinking about where else to deploy capital, it can help to line Netcompany Group up against other opportunities that fit your style. Use the Simply Wall St Screener to build that wider watchlist without losing sight of quality, balance sheet strength or potential income.
- If capital protection matters most to you, focus on resilience first and returns second by starting with 207 resilient stocks with low risk scores that have historically scored well on stability and risk checks.
- For investors who want staying power on the balance sheet and solid underlying metrics, filter for companies with strong finances using the list of solid balance sheet and fundamentals (199 results) to see which businesses match that profile.
- If you are hunting for opportunities the crowd may not be paying attention to yet, scan through the 566 high quality undiscovered gems that pair quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com