
How Raised Earnings Guidance At Encore Capital Group (ECPG) Has Changed Its Investment Story
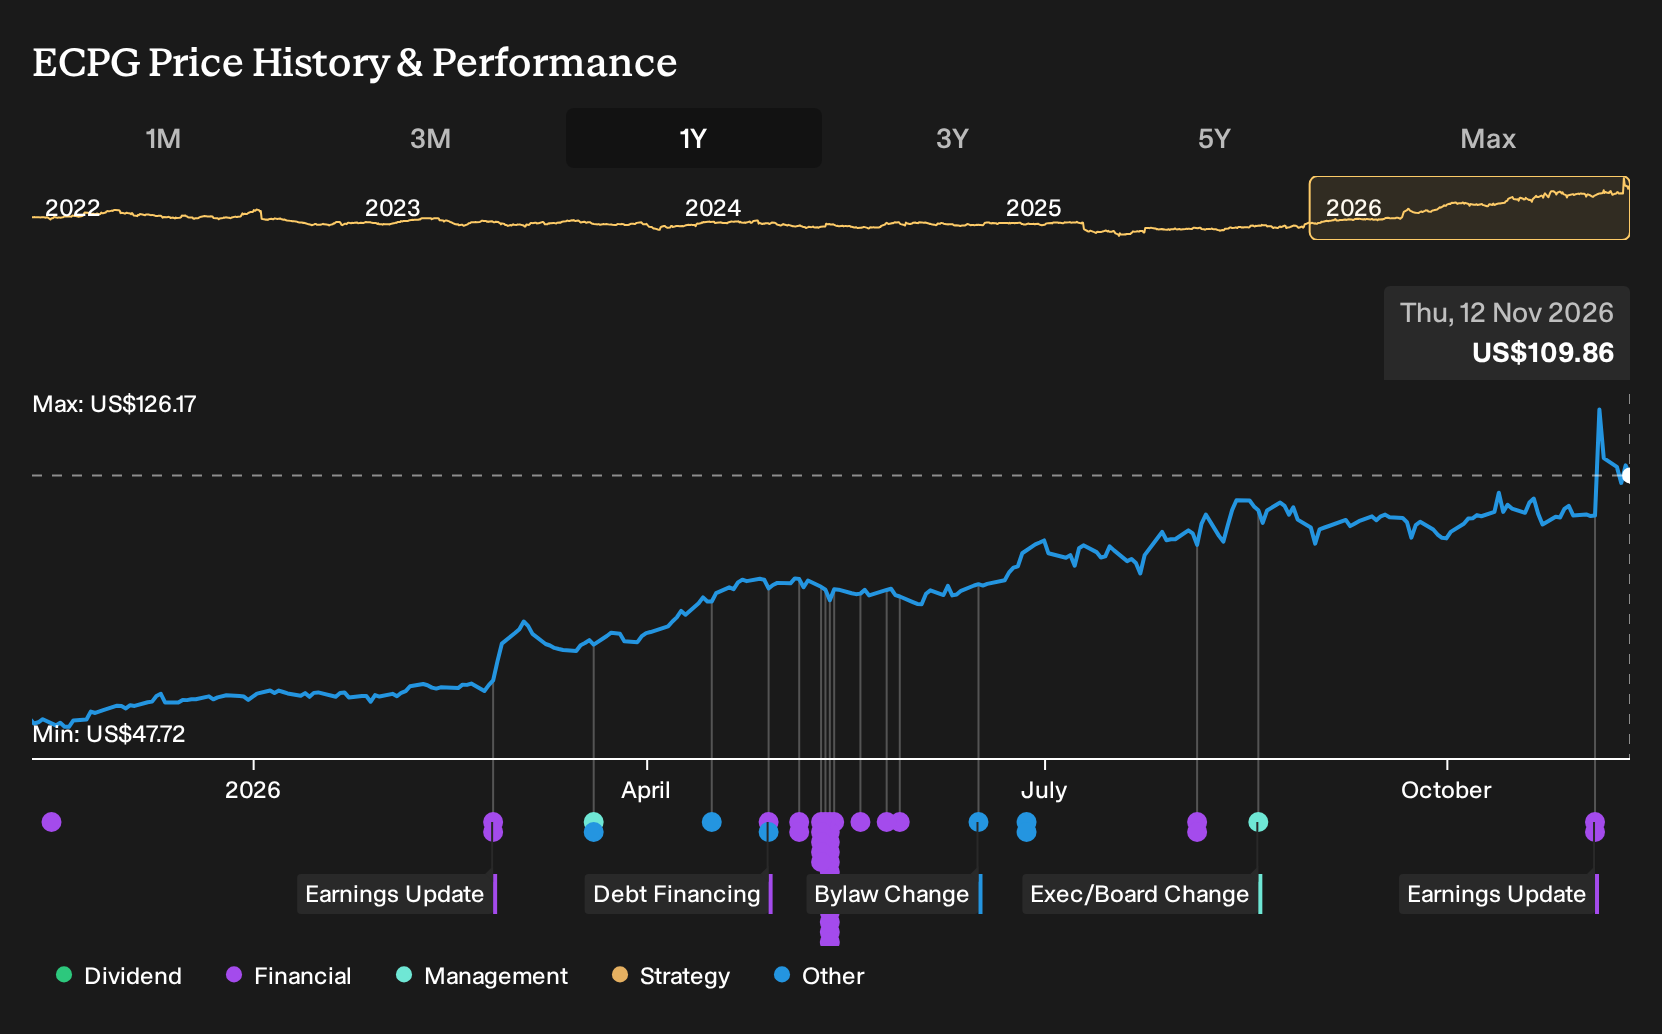
- Encore Capital Group reported third quarter 2026 revenue of US$544.54 million and net income of US$124.01 million, with basic EPS from continuing operations of US$5.80, and also updated nine month 2026 results alongside a higher full year EPS outlook.
- The raised 2026 EPS guidance range of US$15.50 to US$16.00 is presented by management as an indication that current earnings momentum and operating discipline can support materially stronger full year profitability than 2025.
- We will now look at how Encore Capital Group's earlier narrative of missteps and underappreciated assets interacts with this upgraded 2026 earnings guidance.
Scan how Encore Capital Group’s raised guidance compares with other debt collectors and credit-focused financials by checking the curated 29 resilient stocks with low risk scores that pair resilient balance sheets with disciplined earnings profiles.
Encore Capital Group Investment Narrative Recap
To own Encore Capital Group, you need to believe its debt purchasing and recovery model can keep converting purchased portfolios into cash at attractive returns while controlling funding costs. The raised 2026 EPS guidance points to management confidence in current collection performance and operating discipline. The near term catalyst is whether that earnings delivery matches the upgraded range.
The biggest risk right now sits on the balance sheet. Interest payments are described as not well covered by earnings, and the business relies entirely on higher risk borrowing rather than deposits. If portfolio collections soften or funding costs rise, that leverage could matter more than this year’s guidance upgrade.
The raised full year 2026 EPS outlook to US$15.50 to US$16.00 per share is the key announcement to focus on. It links directly to the third quarter report, where Encore Capital Group recorded US$544.54 million of revenue and US$124.01 million of net income, with basic EPS from continuing operations of US$5.80.
That guidance also reshapes how you might read the earlier worries laid out by Joe222, a Simply Wall St Community investor who highlighted prior goodwill write downs and shaken confidence in management. The new outlook puts more weight on execution in the next few quarters. Any shortfall against the guidance range could quickly drag those older concerns back into focus.
On Joe222’s numbers, Encore Capital Group’s fair value of US$120.38 rests on a narrative that pairs a 13.5% annual revenue growth assumption with a future profit margin of 15.7%. It treats the sizeable estimated remaining collections pool as support for those long term cash flows.
Uncover why Encore Capital Group's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster tightly between US$120.38 and US$123, yet investor opinions on Encore Capital Group can still split sharply once fresh information hits. The raised full year 2026 EPS guidance, announced on 4 November 2026, gives you a clear reason to revisit those pre news estimates and compare several alternative viewpoints.
Explore another Encore Capital Group fair value estimate, including one that suggests it could be worth just $120.38.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Encore Capital Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Encore Capital Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Encore Capital Group's overall financial health at a glance.
Looking for more investment ideas beyond Encore Capital Group?
Once you have a view on Encore Capital Group, it can help to widen the lens and line it up against other businesses with different risk and income profiles.
- If capital preservation and steady operations matter most to you, start with a curated set of resilient businesses in the 29 resilient stocks with low risk scores that aim to keep volatility in check.
- If value is your first filter, scan the 32 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their underlying financial strength.
- If you prefer income on top of potential price moves, review the 6 dividend fortresses for ideas that pair higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com