
JPMorgan Chase (JPM) Funding Moves Put Valuation In Focus As Shares Test Record Territory
JPMorgan Chase (JPM) has been active in the funding markets, issuing a series of long-dated notes with fixed coupons that influence its interest costs and liquidity profile over the coming decades.
At a share price of $342.82, JPMorgan Chase has logged a 5.33% year to date share price return, while its 1 year total shareholder return of 12.91% and very large 3 year and 5 year total shareholder returns point to momentum that has cooled in the last quarter. The 90 day share price return declined 5.52%, even as ETF flows, long dated bond issuance and fresh AI related partnerships keep the story in focus for long term holders.
Scan how JPMorgan Chase fits into the broader financials story by comparing it with 32 high quality undervalued stocks that ETFs and long term investors are watching closely right now.
JPMorgan Chase now trades near record territory after a long run and a softer last quarter. Does that set up a stretched bet or a still appealing risk reward as valuation comes into focus next?
Most Popular Narrative: 7% Undervalued
JPMorgan Chase last traded at $342.82, against a narrative fair value of $370.39 that frames the current level as mildly discounted. According to duarte_EM, an investor in the Simply Wall St Community who wrote the narrative, the big US bank is being judged through a long cycle lens rather than a single quarter.
JPMorgan is the best-run large bank in the world, a diversified "fortress balance sheet" spanning consumer, corporate, investment banking and asset management. It is my financial-sector anchor and a source of steady dividends.
Catalysts: net interest income, capital returns (dividends + buybacks), market-share gains in downturns, and scale advantages in technology. It tends to emerge from crises stronger.
See why 26 investors see JPMorgan Chase as 7% undervalued.
In this framework, JPMorgan Chase is priced with a modest 7.4% discount to that $370.39 fair value, using a discount rate of 8.03% to bring projected cash flows back to today. The view leans on a large, diversified banking platform, steady profit growth over time and the ability to keep returning capital while funding technology and risk controls.
Net income of $64.53b on $190.73b of revenue, combined with 9.6% annual earnings growth over the past 5 years, underpins the narrative focus on durable profitability rather than rapid expansion. Earnings growth over the last year is described as 13.9%, which exceeds the 5 year average, and a current net margin near 33.8% still leaves breathing room even though it is fractionally lower than last year.
The narrative also works alongside Simply Wall St's own cash flow view. That model currently values JPMorgan Chase at $496.40 per share, which is 30.9% above the last close and signals a larger margin between market price and future cash flow estimate than the community fair value. For readers weighing those two reference points, the narrative fair value offers a more conservative anchor, while the SWS DCF output frames what a stronger long term cash generation path could be worth if it plays out.
Result: Fair Value of $370.39 (UNDERVALUED)
Still, tighter regulation or a weaker credit cycle could squeeze JPMorgan Chase, especially if net interest income or investment banking activity comes under pressure.
Find out about the key risks to this JPMorgan Chase narrative.
Another View On JPMorgan Chase Valuation
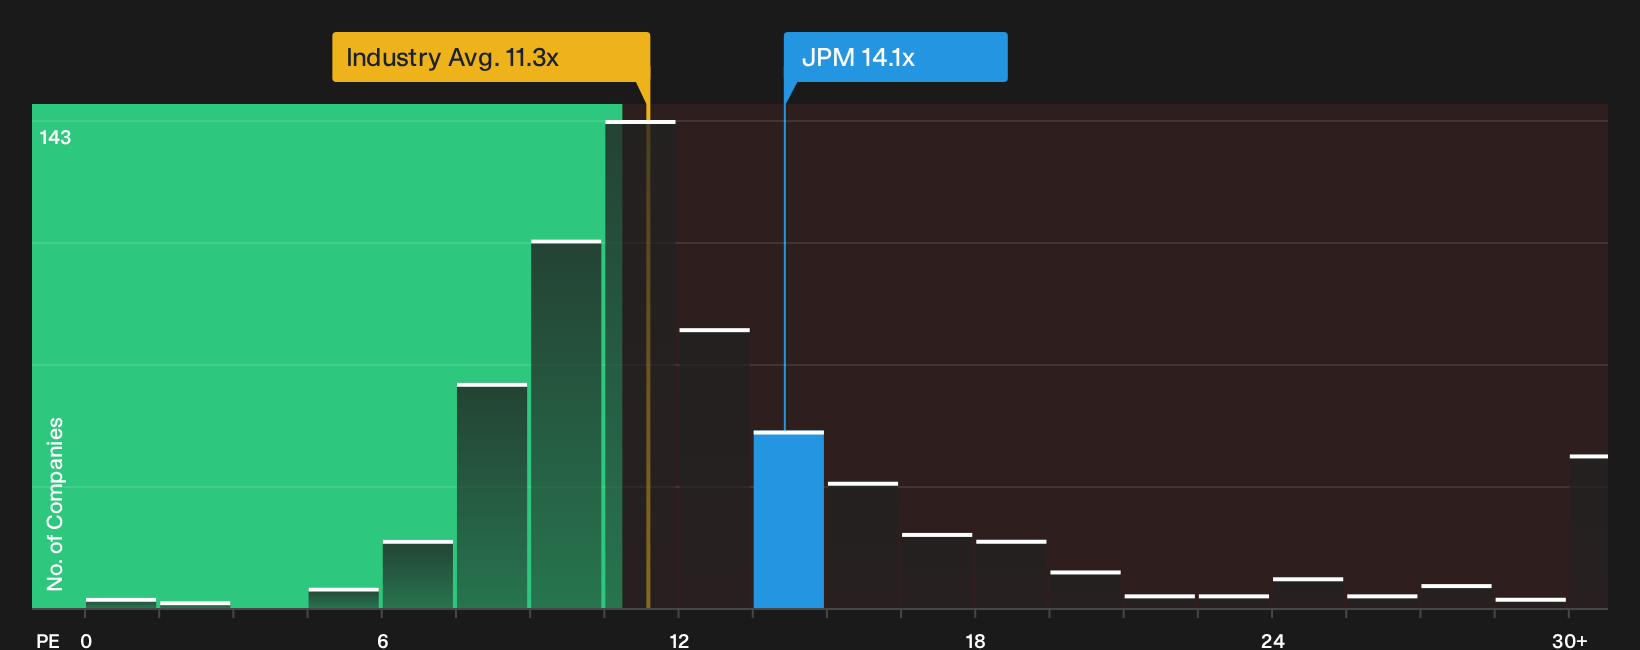
The community narrative leans on cash flows and a SWS DCF fair value of $496.40 that frames JPMorgan Chase as undervalued. The market, though, prices the stock at a P/E of 14.1x versus 11.3x for the US Banks industry and 11.7x for peers, only slightly below a fair ratio of 14.3x. That gap points to a quality premium rather than an obvious bargain, which leaves the real question for you as whether the earnings profile is strong enough to keep justifying that extra multiple.
See what the numbers say about this price in our valuation breakdown, then decide how much weight you want to put on relative P/E versus future cash flows in your own framework See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this JPMorgan Chase story sounds promising on the surface, do not leave the judgment solely to headline metrics or community narratives. Take a closer look at the underlying strengths and risks, and then weigh how the 3 key rewards aligns with your own expectations.
Looking for more ideas beyond JPMorgan Chase?
If JPMorgan Chase fits your framework, consider broadening your watchlist with other opportunities that share similar qualities in value, resilience, or income potential.
Use the Simply Wall St screener to uncover fresh ideas before they move beyond reach.
- Target resilient performers with strong balance sheets by scanning a list of solid balance sheet and fundamentals (23 results) that can handle shocks better than more fragile businesses.
- Look for potential mispriced opportunities by reviewing a curated 32 high quality undervalued stocks that combines quality metrics with room for re rating.
- Build a portfolio that aims to work harder for you by focusing on a short list of income focused 6 dividend fortresses while keeping an eye on fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com