
3 Canadian Quality Stocks With ROE Over 25%
AI related trade is breaking records, yet global rate hikes remain in focus. That mix rewards Canadian companies with healthy profits and low financial strain. Cash rich balance sheets can help absorb higher borrowing costs while still funding growth tied to this AI driven demand. This article walks through three Canadian stocks with strong returns on equity and solid fundamentals from our quality screener.
The stocks highlighted below are just a sample from this quality screen, and the full results include 2 more Canadian companies with equally compelling balance sheet strength and return profiles that are not covered here.
To go wider than this short list and quickly identify your own high conviction ideas, head straight into the Solid Balance Sheet and Fundamentals screener
Lundin Gold (TSX:LUG)
Overview: Lundin Gold is a Vancouver based miner that owns and operates the Fruta del Norte gold project in Ecuador, generating cash flow from producing and selling gold and silver.
Operations: Lundin Gold generates about $2.2b in revenue from the Fruta Del Norte mine in Ecuador, which is its primary cash source.
Market Cap: CA$23.3b
Lundin Gold sits firmly in this solid balance sheet screen because Fruta del Norte is a single, high cash flow asset that has been supporting strong profitability. The bearish analyst Narrative on Simply Wall St sets this against a tougher tax and policy backdrop.
"Although Lundin Gold is currently generating strong free cash flow and margins from Fruta del Norte, the notice of a 2023 sovereign adjustment of US$154 million highlights the risk that future reinterpretations of fiscal terms could absorb a larger share of revenue and compress net margins, especially if higher gold prices keep royalties and profit sharing elevated."
The long term story for Lundin Gold’s returns may hinge on how one quiet shift in its operating framework ultimately lands.
That inflection point is exactly what the full narrative for Lundin Gold unpacks, showing where fiscal risk, reinvestment options and AI era gold demand could be quietly accelerating Lundin Gold’s upside potential.

Sprott (TSX:SII)
Overview: Sprott is a Toronto based asset manager that runs mutual funds, ETFs and other investment products focused on commodities and precious metals.
Operations: The group generates about $236 million from Exchange Listed Products, $94 million from Managed Equities and $78 million from Private Strategies, mostly in Canada and the United States.
Market Cap: CA$4.2b
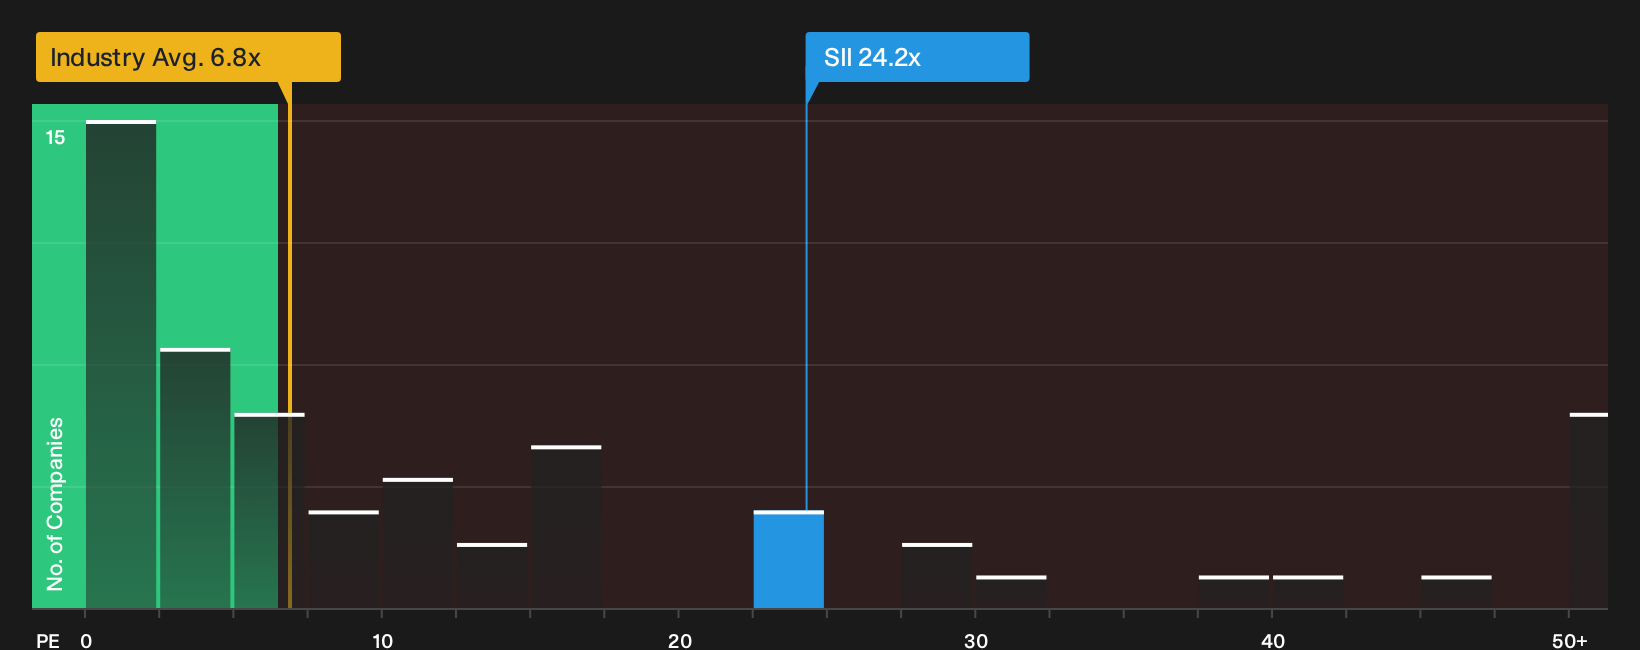
Sprott combines a high 27.2% ROE with fee based businesses that support a solid balance sheet, helped by a debt free position and over $200 million in cash. Earnings grew 127.1% last year and net profit margins are 27.9%. The rich 24.2x P/E therefore depends on what happens if one pressure on future fee growth quietly shifts.
That fee pressure question is exactly where the 2 key rewards and 1 important warning sign lays out how Sprott’s rich P/E could either compress or continue to surprise investors.
OceanaGold (TSX:OGC)
Overview: OceanaGold runs producing gold and gold copper mines in the United States, the Philippines and New Zealand, where recurring cash flow from assets like Didipio, Macraes, Waihi and Haile supports its return on equity and balance sheet strength.
Operations: OceanaGold generates about $2.7b in revenue, led by Haile at $935.6 million, Macraes at $828.7 million, Didipio at $556 million and Waihi at $348.8 million.
Market Cap: CA$8.7b
OceanaGold appears in this solid balance sheet screen because its producing mines generate recurring cash that can be used to fund growth, dividends and buybacks. This aligns with the bullish analyst narrative on Simply Wall St, which focuses on the links between asset quality, returns on equity and balance sheet strength.
"Optimization and expansion at Didipio, including restoration of normal underground rates and a targeted 2.5 million tonne annual mining rate by 2026, should increase copper and gold output from an already low cost asset, enhancing consolidated cash flow and margins."
One potential consideration is how any change in the allocation of that extra cash between new projects and capital returns might affect the overall margin profile.
That capital allocation question is where the full narrative for OceanaGold maps how OceanaGold could balance growth projects and cash returns as production scales and copper exposure widens investor interest.

Seeking Fresh Alternatives Before They Fly?
Fresh opportunities can start breaking out while many investors are still watching yesterday’s winners. Explore these curated ideas before the crowd focuses on them and the most attractive entry points change.
- Scan for income workhorses and use the 3 dividend fortresses to zero in on payout streams that aim to keep cheques coming while prices move.
- Track potential infrastructure leaders by using the 43 power grid technology and infrastructure stocks and finding operators positioned to benefit if energy systems continue to modernise.
- Monitor early momentum in digital assets by scanning the 24 cryptocurrency and blockchain stocks where listed businesses are involved with blockchain, exchanges and transaction activity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com