
How Investors Are Reacting To NorthWestern Energy Group (NWE) Mixed Q3 Earnings
- NorthWestern Energy Group reported third quarter 2026 revenue of US$423.8 million and net income of US$30.7 million, alongside a US$0.67 per share dividend declared for payment on December 1, 2026.
- The mix of higher year over year sales with lower earnings and earnings per share highlights pressure on costs and profitability, even as the regulated utility keeps its dividend in place.
- We will now look at how NorthWestern Energy Group's higher revenue but lower earnings trend could shape its longer term investment narrative.
Compare NorthWestern Energy Group's earnings pressure with other regulated utilities by scanning our hand picked 43 power grid technology and infrastructure stocks for ideas with different revenue and profit profiles.
NorthWestern Energy Group Investment Narrative Recap
To own NorthWestern Energy Group, you need to believe that its regulated utility model, data center load agreements and planned merger with Black Hills can offset current earnings pressure. Revenue grew in the third quarter, but net income and EPS were lower, which points to cost inflation, weather and coal related headwinds still biting into profitability.
The analyst consensus narrative on Simply Wall St leans on future earnings improvement and rate base investment, yet the latest quarter does not materially change the near term story. The biggest near term swing factor remains regulatory and cost recovery progress, while the key risk is that higher operating and financing costs keep squeezing margins and dividend coverage.
The most relevant fresh datapoint is the third quarter 2026 earnings release. NorthWestern Energy Group reported US$423.8 million of revenue for the quarter and US$30.7 million of net income. Basic and diluted EPS from continuing operations were US$0.50, compared with US$0.62 a year earlier, which shows that profit compression is sitting alongside higher sales.
This pattern also shows up over the first nine months of 2026, with revenue of US$1,313.9 million and net income of US$119.2 million, both different from the prior year. For catalysts like data center load, the Large New Load tariff and the proposed Black Hills merger, the near term question is whether current margin pressure and interest costs limit flexibility while these longer term projects are executed.
NorthWestern Energy Group's current narrative assumes revenue grows at about 4.4% per year and reaches roughly US$1.9b by 2029, with earnings projected to be US$266.7 million in that same year. This would be up from US$171.4 million today, which implies an earnings increase of about US$95 million over the period.
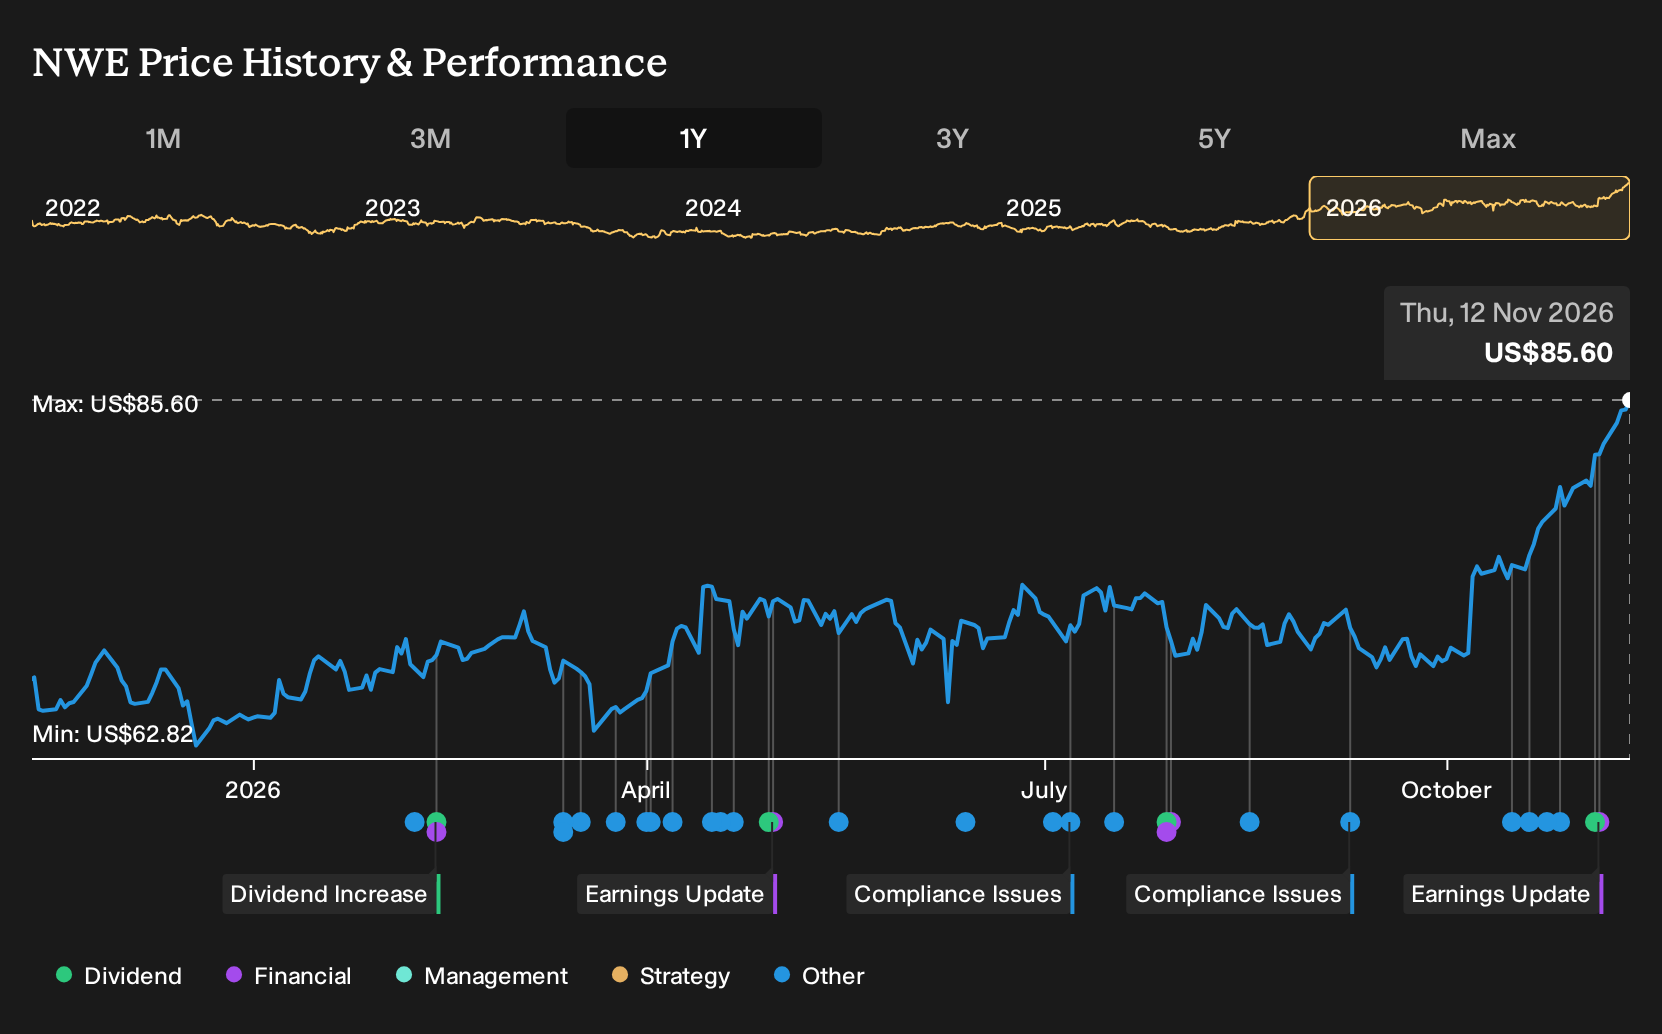
Uncover why NorthWestern Energy Group's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$18.7 to US$79.2 per share, which shows how far apart retail opinions on NorthWestern Energy Group can sit. Set that against coal exposure, warmer weather risk and rising secured debt costs, and then decide which scenarios you think carry more weight.
Explore 2 other NorthWestern Energy Group fair value estimates, including one that suggests there could be as much as 78% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NorthWestern Energy Group research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NorthWestern Energy Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NorthWestern Energy Group's overall financial health at a glance.
Looking for more NorthWestern Energy Group style investment ideas?
If this NorthWestern Energy Group review sharpened your thinking, use that momentum to widen your watchlist with other businesses that fit the kind of risk and return profile you want.
- For investors who want potential upside with tighter quality filters, scan a curated set of 20 high quality undiscovered gems that pair solid fundamentals with less widely followed stories.
- If capital preservation and a smoother ride matter most to you, focus on 29 resilient stocks with low risk scores that score well on resilience and downside control.
- Income seekers can anchor their research around consistent cash payouts by screening for 6 dividend fortresses that aim to combine elevated yields with strength in core financial metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com