
What VSE (VSEC)'s Raised Revenue Outlook Means For Shareholders
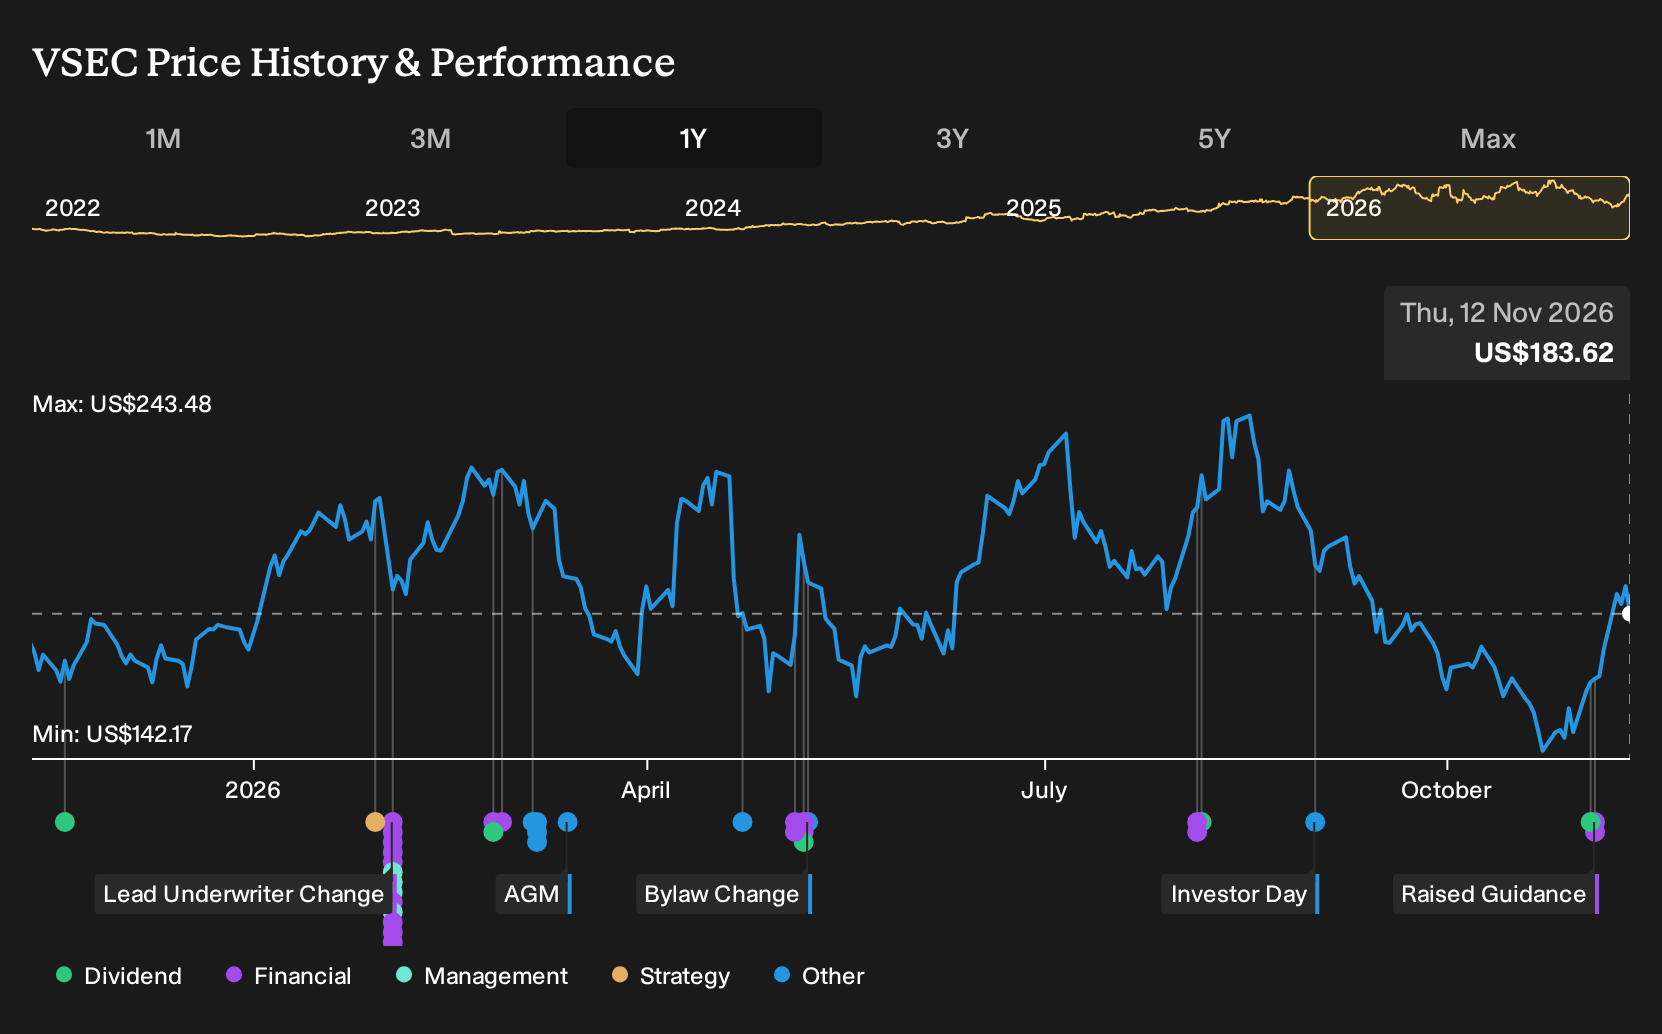
- VSE Corporation reported third quarter 2026 revenue of US$541.01 million and net income of US$47.26 million, alongside higher full year revenue growth guidance of 65% to 66.5% and an affirmed US$0.10 quarterly dividend payable in January 2027.
- The shift from a net loss in the prior nine month period to net income of US$104.84 million in 2026 highlights how VSE's aviation focused model is associated with stronger profitability and cash distribution capacity.
- This article examines how VSE's raised 2026 revenue growth guidance may reshape the existing aviation aftermarket investment narrative for investors.
VSE Investment Narrative Recap
To own VSE, you need to be comfortable with a pure aviation aftermarket story where growth is tied closely to air traffic, engine shop throughput and OEM distribution programs. The analyst consensus Narrative on Simply Wall St leans on this model scaling over time. The raised 2026 revenue growth guidance to 65% to 66.5% keeps that thesis intact and supports near term execution confidence.
The main near term swing factor is integration of the Precision Aviation Group acquisition and delivery of planned cost and in sourcing synergies. The biggest operational risk is that higher leverage, large upfront inventory commitments and any air travel slowdown squeeze free cash flow and delay debt reduction, which this update does not fully resolve.
The raised full year 2026 revenue outlook is the clearest operational signal in the latest announcements. Management now guides to 65% to 66.5% growth, reflecting third quarter revenue of US$541.01 million and solid nine month performance. For you, the key question is whether this pace is sustainable while VSE absorbs acquisitions and builds out OEM programs.
This higher top line range also interacts with valuation. VSE trades on a P/E of about 41.7x and sits roughly 25.9% below the current analyst price target, so strong reported growth is already an important catalyst for sentiment. If integration, working capital and leverage are managed tightly, the upgraded guidance can help maintain confidence in the existing aviation aftermarket narrative.
What VSE's Long Range Forecasts Assume
Analysts are effectively asking you to underwrite a much larger VSE aviation platform by the end of this decade. Their models point to revenue of about US$2.6b and earnings of roughly US$236.3 million by 2029, based on an assumed 16.5% yearly increase in sales over the next three years. That profit figure compares with current earnings of about US$127.1 million. This implies earnings would almost double, reaching roughly 1.9 times the current level, if the consensus view plays out.
Discover why VSE's fair value indicates a 35% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community offers three fair value views for VSE between about US$198 and US$248, which already span a wide US$50 band before the latest earnings, guidance lift and dividend affirmation. You can weigh that spread against risks from higher leverage and aviation cycle exposure, then explore how different investors frame potential upside and downside.
Explore 2 other VSE fair value estimates, including one that suggests there could be up to 35% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VSE research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for VSE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VSE's overall financial health at a glance.
Looking For More Investment Ideas Beyond VSE?
Once you have formed a view on VSE, it can help to compare it with other opportunities that share similar qualities, whether that is strong balance sheets, dependable income or under-the-radar potential. The Simply Wall St Screener lets you apply those filters quickly so you spend more time assessing the story and less time trawling through tickers.
- If capital preservation is high on your list, start with a group of resilient companies by running a screen on 29 resilient stocks with low risk scores.
- For investors who care about robust finances and staying power, filter for businesses with healthier funding and liquidity profiles using our list of solid balance sheet and fundamentals (23 results).
- If you prefer opportunities that are still off most radars, widen your watchlist with a curated 20 high quality undiscovered gems that combine quality fundamentals with quieter coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com