
Parsons (PSN) Stock Looks Above Fair Value As Shares Fell 42%
Parsons shares closed at US$49.87 and have delivered a sharp 41.5% decline over the past year, which puts a fresh spotlight on whether that lower price now lines up with what the business is earning. With investors reacting to both contract wins and execution risks, the real question is how the current earnings profile stacks up against what the market is willing to pay.
- The stock has fallen 41.5% over the past 12 months, so the recent slide puts more weight on whether Parsons' earnings can support even this reduced valuation.
- New contract wins, including a US$100m ceiling-value amendment for environmental engineering work and fresh awards in defense and infrastructure, can influence how steadily Parsons converts its backlog into earnings and cash flow over time.
- Your read on Parsons is one view; the desks covering it have another. See what analysts think Parsons's shares could be worth.
The issue now is whether Parsons' current share price is justified by its earnings when measured against the Fair Ratio benchmark.
For a broader sense of how Parsons' contract driven story compares with other opportunities, line it up against companies in 43 power grid technology and infrastructure stocks.
Does Parsons Look Pricey on Earnings?
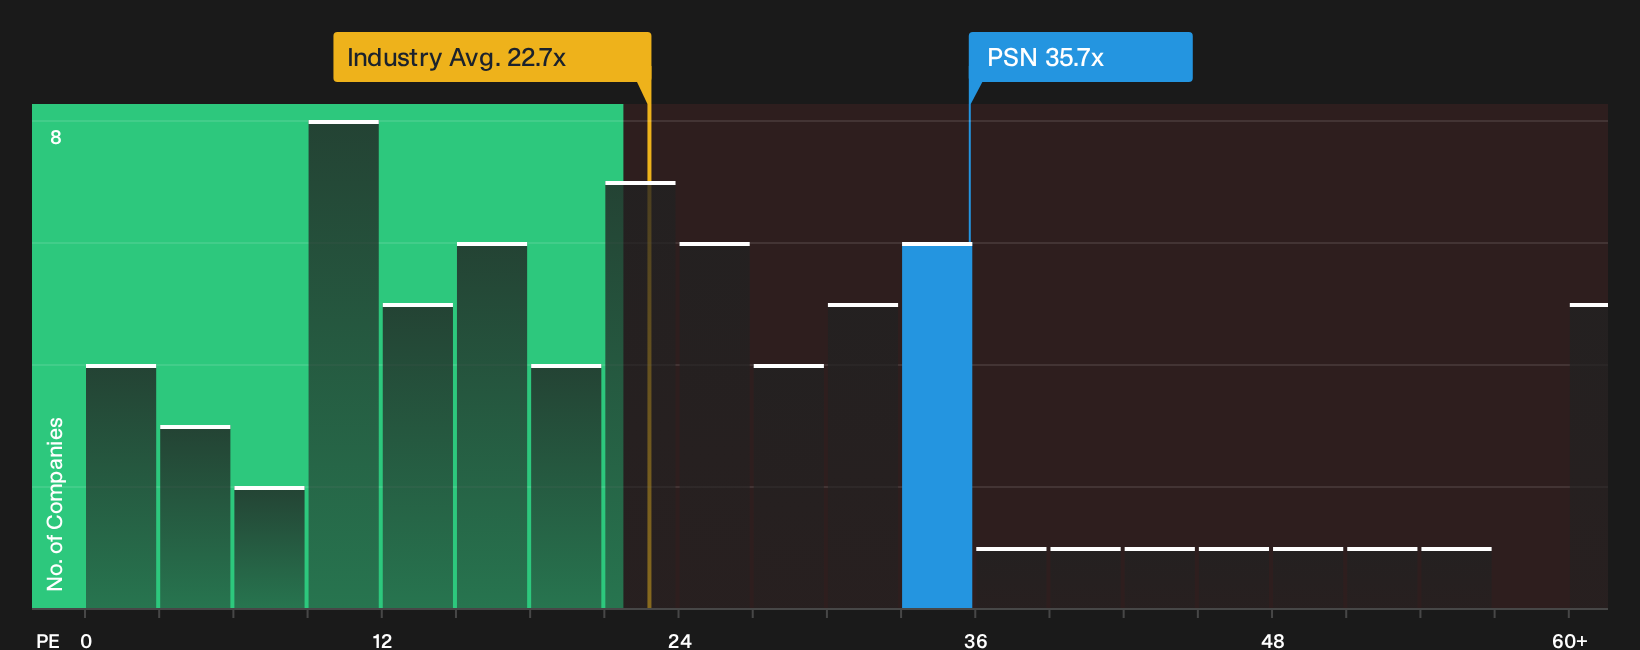
P/E fits Parsons because earnings are a key reference point for a contract heavy, project based operation. On that metric, the stock trades on roughly 35.7x earnings, which is higher than the Professional Services industry average of about 22.7x and also above the peer group mark near 25.5x. Against the Fair Ratio benchmark, which adjusts for Parsons' own mix of growth profile, margins, scale and risk, the current P/E sits on the expensive side and points to an overvalued reading on this framework.
Because Parsons has recently reported fresh contract wins and product launches, such as iNET Convergent Response for faster decision making, the valuation already assumes a lot of that execution turning into steady earnings. For an investor, the gap between the current P/E and the earnings multiple implied by the Fair Ratio model is a reminder to check whether the quality and durability of those profits feel strong enough to justify paying a richer tag than both the sector and close peers. Explore the numbers behind Parsons's P/E valuation.
The Parsons Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Parsons valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to be worth meaningfully more or meaningfully less than it is today on the screen. Each narrative links its number to a specific view on how Parsons' prospects and risks could shift, giving you something concrete to revisit as fresh information arrives.
One of the top narratives on Parsons: 24% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"Scaling of Parsons’ AI enabled product portfolio, with roughly $350 million of expected 2026 product revenue and a plan for 20% to 30% growth in 2027 at margins above the corporate average..."
Discover why this Narrative puts Parsons at 24% undervalued.
Parsons’ price is only one piece of the decision
Before you treat Parsons as just a story about contracts and P/E, factor in that Simply Wall St’s broader checks have highlighted specific risk signals you may want to weigh for yourself. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com