
Is GE Vernova (GEV) A Bargain On SoftBank Contract Risks And Strong Guidance?
GE Vernova (GEV) is back in focus after SoftBank revised its U.S. data center power equipment plans and booked a multi billion dollar charge linked to contracts that include GE Vernova technology.
GE Vernova has been on a sharp round trip this year, with a 1 year total shareholder return of 47% and a year to date share price return of 20.45%. Recent momentum has faded, however, as the 30 day share price return declined 18.48% and the 90 day move fell 23.02%, despite a 6.23% gain over the past week and a 1.27% rise in the last session to US$818.49.
That slump since mid year has tracked a series of data center headlines, including SoftBank’s multibillion dollar charge on power equipment contracts tied to GE Vernova technology, along with broader concerns about how durable AI driven infrastructure spending will be.
In contrast, investors have been weighing strong third quarter 2026 results with 96% organic order growth, raised 2026 revenue and free cash flow guidance, and fresh project wins such as the new onshore wind agreement in Germany. Together, these factors help explain why total shareholder returns over 12 months still look much stronger than the recent share price pullback.
Spot 43 power grid technology and infrastructure stocks that could benefit from the same data center and electrification forces now pulling GE Vernova into the spotlight.GE Vernova looks like a powerful grid and gas turbine franchise caught in a sentiment swing. After a 31% slide since June, are you paying a fair price for that strength or overpaying for the story?
Most Popular Narrative: 36% Undervalued
GE Vernova’s most followed valuation storyline pegs fair value at $1,269.77, well above the last close at $818.49. This frames a sizeable upside gap before even touching analyst price targets.
This view comes from prajeeshprathap, a Simply Wall St Community investor who wrote the narrative, and who highlights the scale and durability of GE Vernova’s role in power infrastructure as a central pillar of that valuation case.
GE Vernova sits at the center of one of the most important industrial shifts of this decade: the explosive growth in electricity demand driven by AI data centers, electrification, and grid modernization. While many investors focus on semiconductor companies benefiting from AI, GE Vernova is effectively the “power infrastructure backbone” enabling the entire ecosystem. Every hyperscale AI data center needs massive amounts of reliable electricity, and GE Vernova supplies the gas turbines, transformers, switchgear, and grid systems that generate and deliver that power.
See why 65 investors see GE Vernova as 36% undervalued.
The narrative uses a 9.697389% discount rate to bring those future cash flows and margins back to today. This is a relatively demanding hurdle for an industrial group with $44.0b in annual revenue and a market value of about $212.8b. It leans heavily on the idea that Power and Electrification, backed by a very large installed turbine base and long term service contracts, can support higher and more predictable free cash generation than GE Vernova was known for historically.
That story, and the 36% discount to the $1,269.77 fair value implied in the narrative, also sits alongside mixed valuation signals elsewhere. Analysts collectively see room for the share price to move toward a $1,178.39 target according to the data provided, while the SWS DCF model points to a lower future cash flow value of $752.12, below the current share price. Together, those numbers underline how much hinges on whether recent earnings strength and very high return on equity can be sustained once one off gains and data center driven order spikes normalise.
Result: Fair Value of $1,269.77 (UNDERVALUED)
Still, the GE Vernova narrative could unravel quickly if AI focused power demand slows or if the Wind segment’s legacy contracts weigh more heavily on profitability.
Find out about the key risks to this GE Vernova narrative.
Another View: GE Vernova Through The P/E Lens
The DCF narrative paints GE Vernova as 36% undervalued at $1,269.77. The market signal from plain P/E is softer. At 20.8x earnings, the stock trades cheaper than the US Electrical industry at 27.1x, peers at 88.4x, and even a fair ratio of 32.9x. Is that a margin of safety or a warning that expectations are already rich on cyclical earnings and one off gains?
For investors weighing this earnings based view, See what the numbers say about this price — find out in our valuation breakdown.
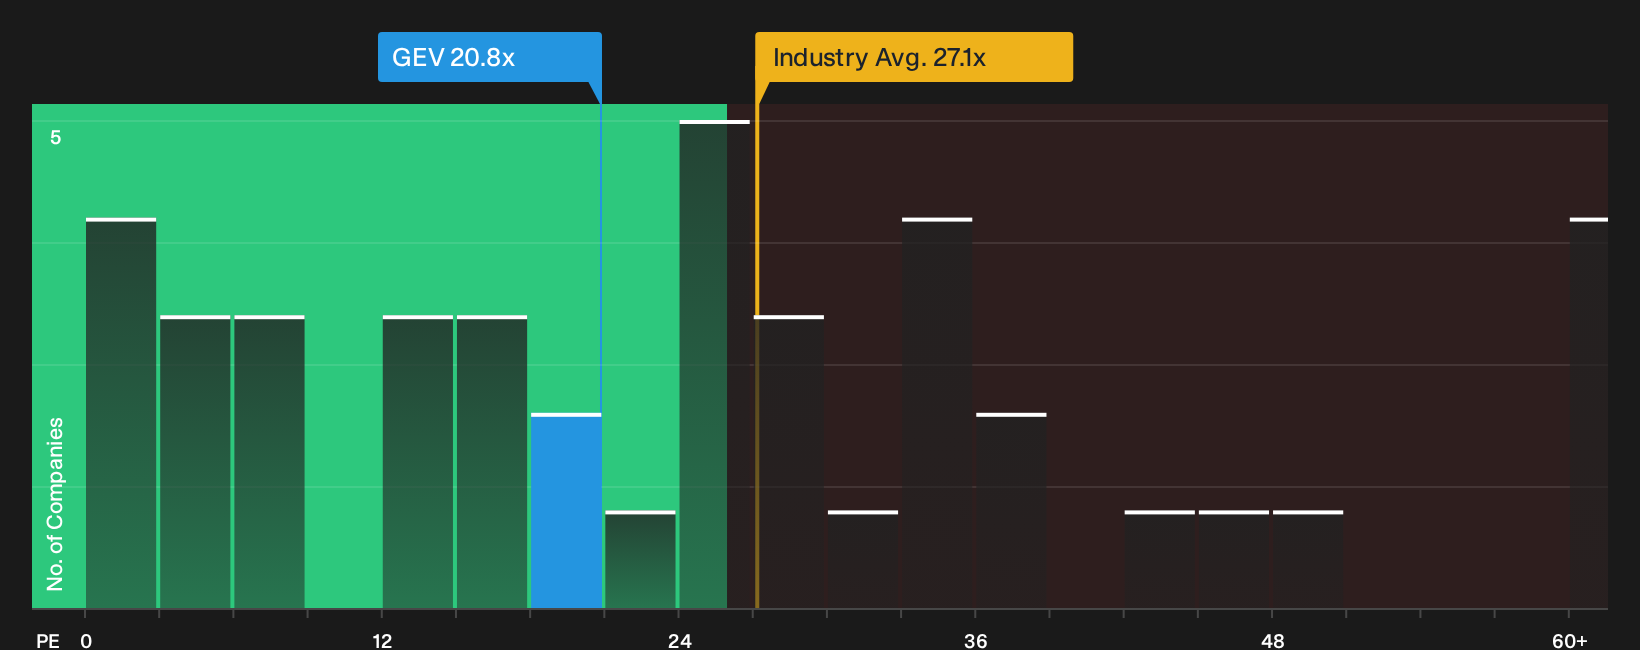
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out GE Vernova for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in this GE Vernova story pulls in different directions. Enthusiasm for potential rewards is offset by concern about risks, so move quickly and examine the data yourself before sentiment shifts again, and then weigh up the balance of 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond GE Vernova?
Do not stop with GE Vernova. Broaden your watchlist with a few focused stock ideas that match how you like to balance upside and risk.
- Target resilient balance sheets and cash rich businesses by scanning our list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced opportunities with strong fundamentals using the 32 high quality undervalued stocks.
- Lock in cash flow today while still aiming for stability by reviewing a curated set of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com