
Twin Disc, Incorporated (NASDAQ:TWIN) Looks Interesting, And It's About To Pay A Dividend
Regular readers will know that we love our dividends at Simply Wall St, which is why it's exciting to see Twin Disc, Incorporated (NASDAQ:TWIN) is about to trade ex-dividend in the next 4 days. Typically, the ex-dividend date is one business day before the record date, which is the date on which a company determines the shareholders eligible to receive a dividend. The ex-dividend date is an important date to be aware of as any purchase of the stock made on or after this date might mean a late settlement that doesn't show on the record date. Meaning, you will need to purchase Twin Disc's shares before the 18th of November to receive the dividend, which will be paid on the 1st of December.
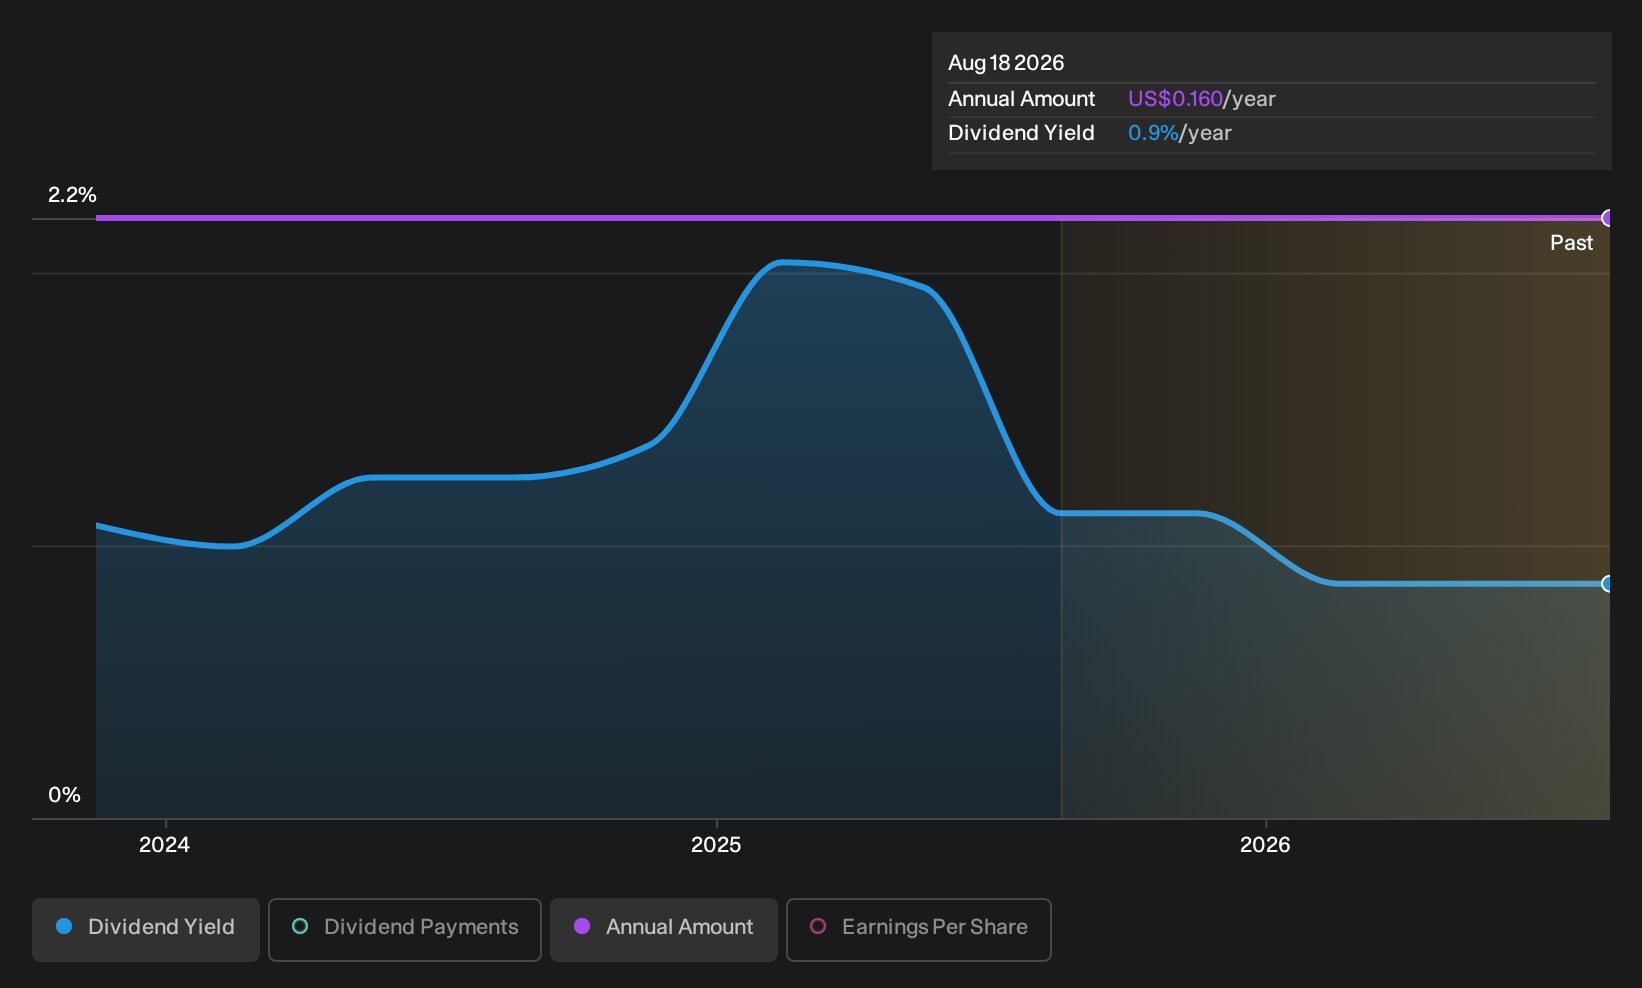
The company's next dividend payment will be US$0.05 per share. Last year, in total, the company distributed US$0.16 to shareholders. Based on the last year's worth of payments, Twin Disc stock has a trailing yield of around 0.8% on the current share price of US$24.63. If you buy this business for its dividend, you should have an idea of whether Twin Disc's dividend is reliable and sustainable. So we need to check whether the dividend payments are covered, and if earnings are growing.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. Twin Disc paid out just 7.8% of its profit last year, which we think is conservatively low and leaves plenty of margin for unexpected circumstances. A useful secondary check can be to evaluate whether Twin Disc generated enough free cash flow to afford its dividend. The good news is it paid out just 9.5% of its free cash flow in the last year.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
View our latest analysis for Twin Disc
Click here to see how much of its profit Twin Disc paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Businesses with strong growth prospects usually make the best dividend payers, because it's easier to grow dividends when earnings per share are improving. If business enters a downturn and the dividend is cut, the company could see its value fall precipitously. That's why it's comforting to see Twin Disc's earnings have been skyrocketing, up 48% per annum for the past five years. With earnings per share growing rapidly and the company sensibly reinvesting almost all of its profits within the business, Twin Disc looks like a promising growth company.
Another key way to measure a company's dividend prospects is by measuring its historical rate of dividend growth. Since the start of our data, three years ago, Twin Disc has lifted its dividend by approximately 7.7% a year on average. It's encouraging to see the company lifting dividends while earnings are growing, suggesting at least some corporate interest in rewarding shareholders.
Final Takeaway
From a dividend perspective, should investors buy or avoid Twin Disc? Twin Disc has been growing earnings at a rapid rate, and has a conservatively low payout ratio, implying that it is reinvesting heavily in its business; a sterling combination. It's a promising combination that should mark this company worthy of closer attention.
With that in mind, a critical part of thorough stock research is being aware of any risks that stock currently faces. Be aware that Twin Disc is showing 2 warning signs in our investment analysis, and 1 of those is concerning...
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.