
Earnings Update: Immatics N.V. (NASDAQ:IMTX) Just Reported Its Third-Quarter Results And Analysts Are Updating Their Forecasts
The analysts might have been a bit too bullish on Immatics N.V. (NASDAQ:IMTX), given that the company fell short of expectations when it released its quarterly results last week. Earnings missed the mark, with revenues of €6.8m falling badly (37%) short of expectations. Losses were mildly higher, with a €0.49 per-share loss being 7.8% above what the analysts modelled. Earnings are an important time for investors, as they can track a company's performance, look at what the analysts are forecasting for next year, and see if there's been a change in sentiment towards the company. Readers will be glad to know we've aggregated the latest statutory forecasts to see whether the analysts have changed their mind on Immatics after the latest results.
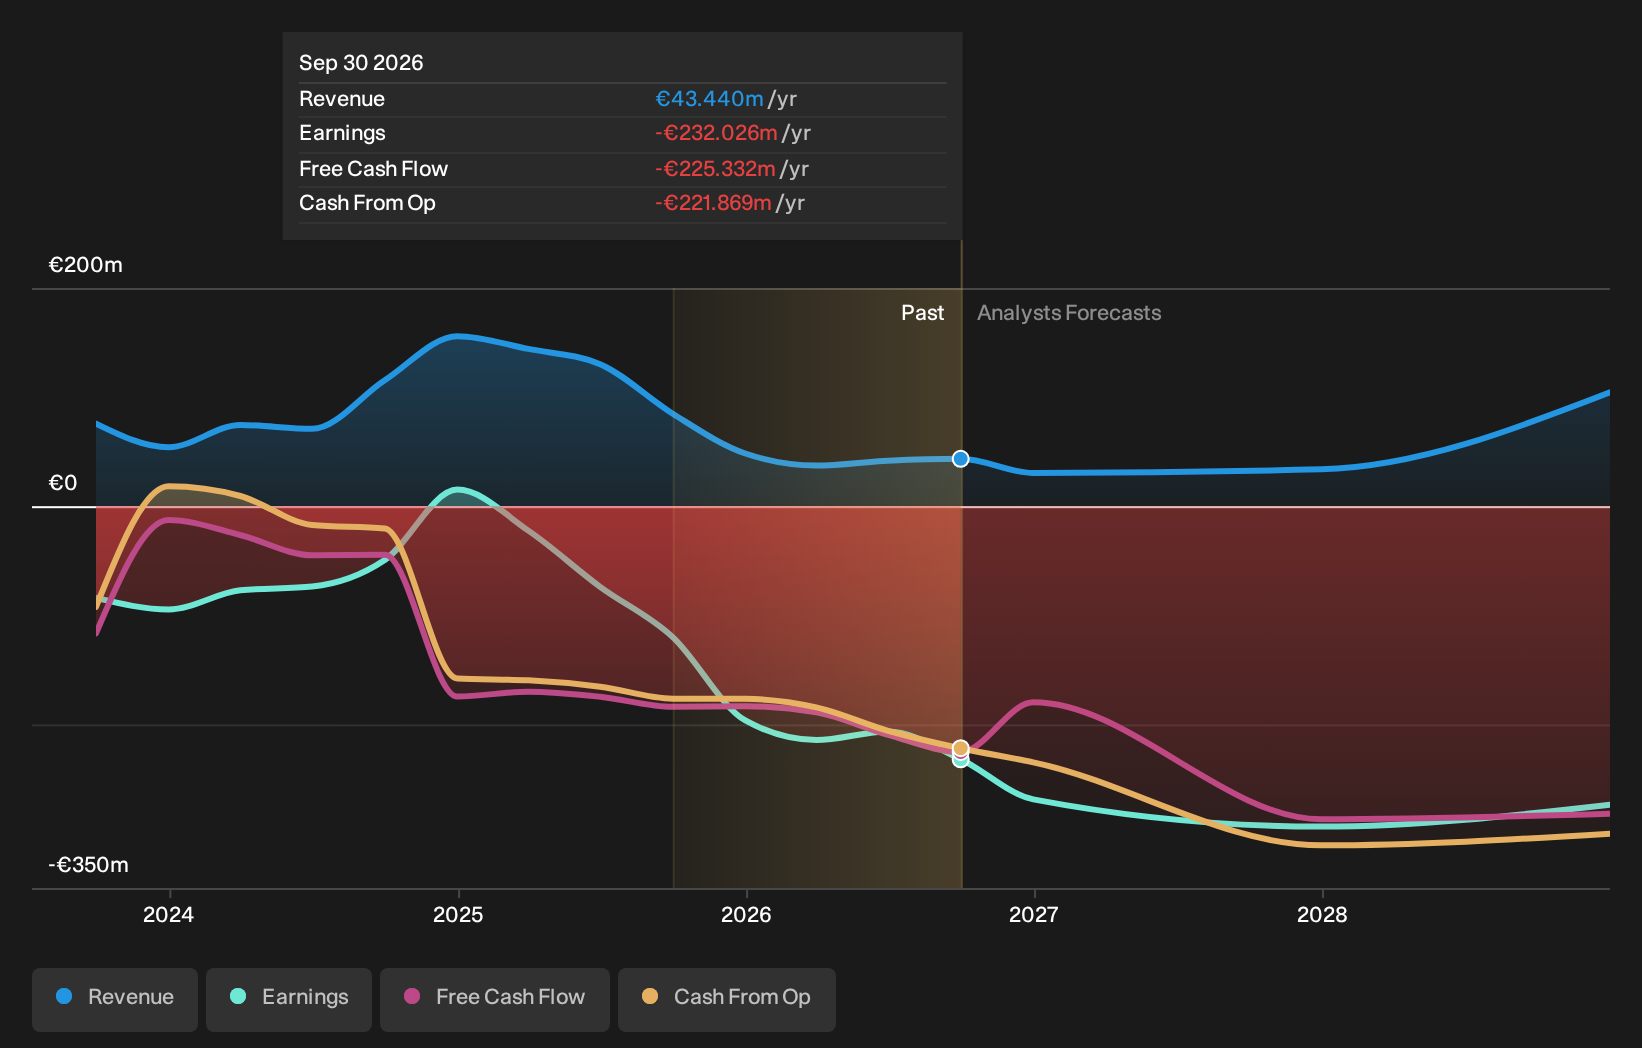
Following the recent earnings report, the consensus from eight analysts covering Immatics is for revenues of €33.7m in 2027. This implies a disturbing 22% decline in revenue compared to the last 12 months. Per-share losses are predicted to creep up to €1.85. Yet prior to the latest earnings, the analysts had been forecasting revenues of €35.4m and losses of €1.83 per share in 2027.
See our latest analysis for Immatics
There was no real change to the average price target of US$16.40, suggesting that the revisions to revenue estimates are not expected to have a long-term impact on Immatics' valuation. The consensus price target is just an average of individual analyst targets, so - it could be handy to see how wide the range of underlying estimates is. There are some variant perceptions on Immatics, with the most bullish analyst valuing it at US$21.00 and the most bearish at US$11.80 per share. This shows there is still a bit of diversity in estimates, but analysts don't appear to be totally split on the stock as though it might be a success or failure situation.
One way to get more context on these forecasts is to look at how they compare to both past performance, and how other companies in the same industry are performing. Over the past five years, revenues have declined around 7.1% annually. Worse, forecasts are essentially predicting the decline to accelerate, with the estimate for an annualised 18% decline in revenue until the end of 2027. Compare this against analyst estimates for companies in the broader industry, which suggest that revenues (in aggregate) are expected to grow 22% annually. So it's pretty clear that, while it does have declining revenues, the analysts also expect Immatics to suffer worse than the wider industry.
The Bottom Line
The most obvious conclusion is that the analysts made no changes to their forecasts for a loss next year. On the negative side, they also downgraded their revenue estimates, and forecasts imply they will perform worse than the wider industry. The consensus price target held steady at US$16.40, with the latest estimates not enough to have an impact on their price targets.
Keeping that in mind, we still think that the longer term trajectory of the business is much more important for investors to consider. At Simply Wall St, we have a full range of analyst estimates for Immatics going out to 2028, and you can see them free on our platform here..
However, before you get too enthused, we've discovered 2 warning signs for Immatics (1 shouldn't be ignored!) that you should be aware of.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.