
Apple Hospitality REIT (APLE) Earnings Beat Raises The Question Of Whether Shares Are Fully Valued
Apple Hospitality REIT (APLE) just delivered third quarter numbers that showed higher revenue and net income than a year earlier, and management responded by lifting full year 2026 earnings guidance.
Recent trading has been strong for Apple Hospitality REIT, with the share price posting a 30 day gain of 17.64% and a 90 day share price return of 21.16% as investors reacted to the earnings beat and guidance raise. The move builds on earlier momentum, with a year to date share price return of 61.44% and a 1 year total shareholder return of 78.98%, signaling that the market has been steadily reassessing both income potential and perceived risk around the stock.
Scan how Apple Hospitality REIT compares with other real estate plays showing resilient fundamentals and fresh momentum by reviewing our hand picked list of solid balance sheet and fundamentals (23 results)
After a 1 year total return near 79% and a share price now a little above the average analyst target, the real puzzle is where fair value for Apple Hospitality REIT actually sits across the full range of estimates.
Most Popular Narrative: 9% Overvalued
On the analyst consensus Narrative on Simply Wall St, Apple Hospitality REIT screens as modestly overvalued, with a fair value of about $17.94 against the latest close of $19.47. This raises the question of what is powering that premium.
The current valuation, along with evidence of resilient RevPAR, margin expansion, regular monthly cash distributions near a mid single digit yield and improving external views on Apple Hospitality REIT’s earnings outlook, suggests the share price already reflects a fairly valued, bullish narrative that assumes continued execution rather than a deep discount.
See why 49 investors see Apple Hospitality REIT as 9% overvalued.
Result: Fair Value of $17.94 (OVERVALUED)
Still, that bullish Apple Hospitality REIT story can be knocked off course if hotel renovations drag on, causing guest disruption, or if softer demand in markets like Phoenix weighs on RevPAR and earnings.
Find out about the key risks to this Apple Hospitality REIT narrative.
Another View: Apple Hospitality REIT Through A P/E Lens
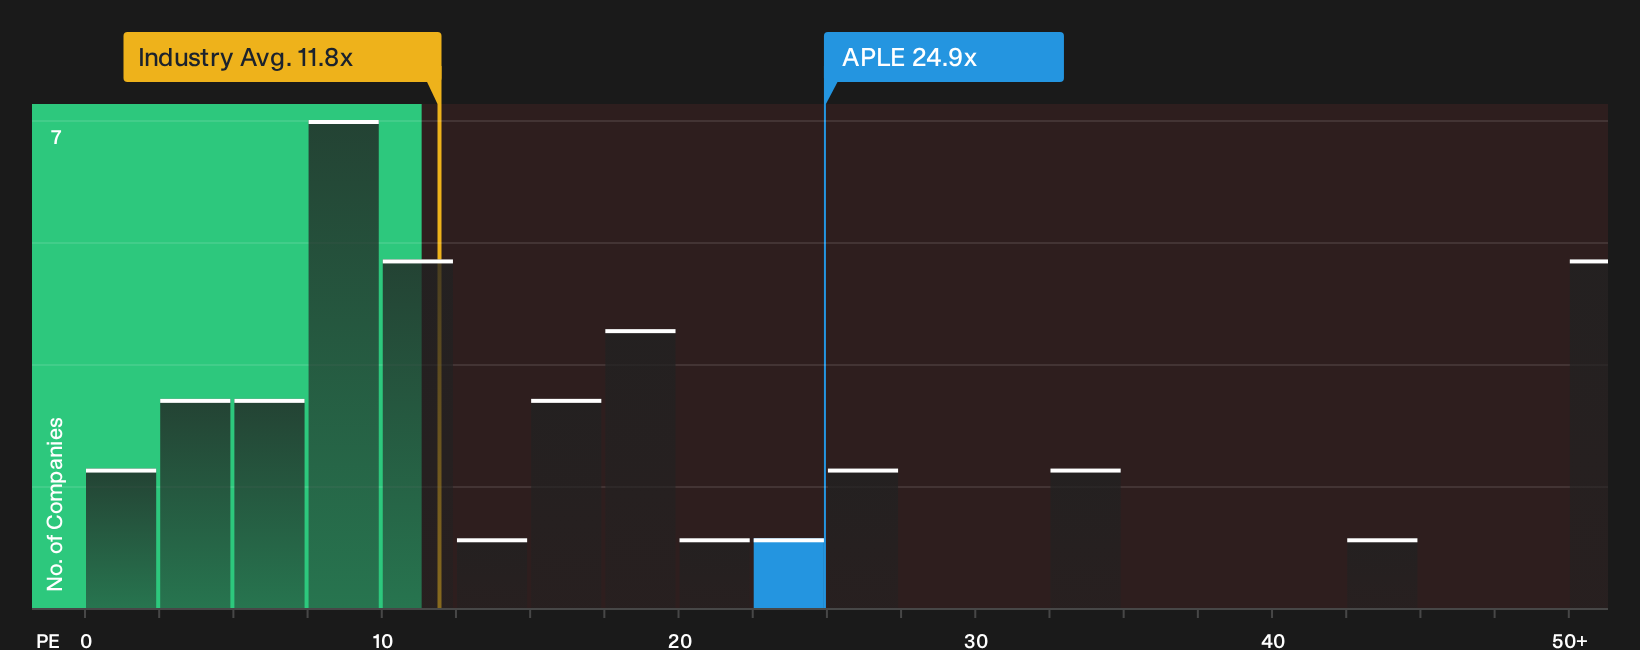
There is a sharp contrast once Apple Hospitality REIT is viewed through simple earnings multiples. The stock trades on a P/E of 24.9x, which is higher than the Global Hotel and Resort REITs group at 11.6x and slightly above the peer average of 24.3x, yet still below a fair ratio of 33x implied by regression work. That mix of richer pricing than the sector but a gap to the fair ratio raises a practical question for investors: Is this a premium story that has more room to rerate, or is the market already paying up for comfort on quality and income?
To see how that P/E gap and fair ratio play out in detail, including where valuation risk and potential opportunity may sit across peers, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Apple Hospitality REIT so far. If you want to move quickly and form your own view, start by weighing the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Apple Hospitality REIT?
If Apple Hospitality REIT has sharpened your focus, do not stop here. Broader ideas can help you stress test your thinking and refine your watchlist.
- Target resilient balance sheets and steady fundamentals by scanning our curated list of solid balance sheet and fundamentals (23 results).
- Hunt for potential value gaps by reviewing a hand picked set of 32 high quality undervalued stocks.
- Prioritise stability and income potential by checking out a focused group of 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com