
Dana (DAN) Stock Still Looks Cheap As Its 93% Run Draws Focus
Dana Incorporated has had a choppy year in the market, yet the longer track record is strong enough that investors are now asking whether the current share price still lines up with its sales base. With fresh scrutiny on the business following a proposed sale to Eaton Corporation, the question is how much revenue power the market is baking into Dana today.
- Over the past 3 years the stock has returned 93.4%, which puts real weight on whether recent share gains reflect sustainable sales rather than just sentiment.
- The investigation into the planned sale to Eaton can influence how investors think about future revenue scale, margin potential and the value they ascribe to each dollar of Dana's sales.
- The analysts covering Dana have run their own numbers. See what analysts think Dana's shares could be worth.
The stock's next move may depend on whether the current market value can be squared with the level and quality of Dana's sales.
If you want to test the same sales-based valuation question beyond Dana, broaden the lens with a set of 32 high quality undervalued stocks.
Is Dana Still Cheap on Sales?
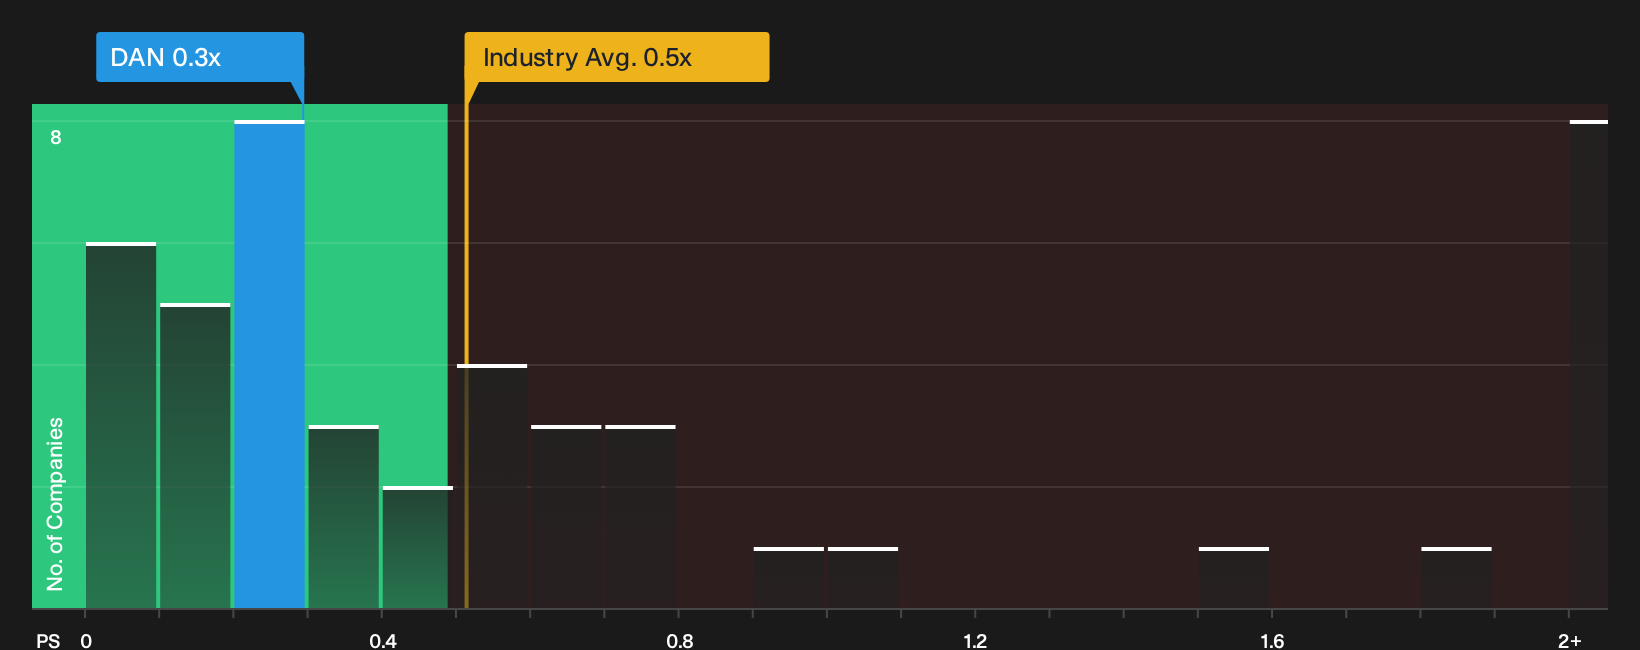
P/S fits Dana because the business is more about steady component revenue than headline earnings that can swing around with one off items. On this lens, the stock trades on a P/S of 0.3x, which is below both the Auto Components industry average of 0.5x and the peer group around 0.6x. The fair multiple model, which tries to reflect Dana’s own scale, margins and risk profile rather than just raw sector averages, also points to a higher P/S than the market is currently paying.
Because the proposed sale to Eaton has sharpened focus on what each dollar of Dana sales might be worth inside a larger group, a discounted P/S raises the question of whether investors are still pricing in deal uncertainty or just marking the business as structurally less attractive than peers. For anyone weighing that gap, the key judgement is whether Dana’s revenue mix and profitability potential justify a P/S closer to the tailored fair level suggested by the modelling, or whether the present discount is a reasonable reflection of risk. Explore the numbers behind Dana's P/S valuation.
The Dana Narrative: What Would Justify Today's Price?
That valuation gap sets up Simply Wall St Narratives for Dana as the next step, since they spell out which paths for future growth, margins and earnings would need to play out for the stock to deserve a much higher or lower price than today. Each scenario then ties a fair value estimate to a specific set of potential catalysts and risks so you can watch over time which version of Dana's story appears to be taking shape.
One of the top narratives on Dana: 35% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Dana delivers the planned cost savings and Eaton Mobility synergies, while building a larger, higher margin aftermarket and defense mix..."
Discover why this Narrative puts Dana at 35% undervalued.
Dana's valuation is only half the story
Price and sales multiples tell you what the market is paying for Dana today, but the research also flags specific risk checks that deserve your attention before making any decision. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com