
Is Alpha Pore Launch Altering The Investment Case For Donaldson Company Stock?
- Donaldson Company recently introduced Alpha-Pore technology, a sterile filtration platform aimed at extending filter service life while keeping flow, sterility and process integrity within required parameters. Internal tests cited up to 2.5x longer run time and durability through up to 150 sterilization-in-place cycles.
- The launch expands the LifeTec portfolio into higher performance filtration, where longer run time and consistent differential pressure can reduce changeout frequency, which may support customer productivity and deepen Donaldson Company’s role in process critical food and beverage applications.
- The focus now shifts to how Donaldson Company’s investment narrative could be affected by Alpha-Pore’s longer life sterile filtration technology.
Donaldson Company Investment Narrative Recap
For Donaldson Company, the core belief as a shareholder is that higher technology filtration and a large recurring aftermarket can keep earnings resilient even while parts of the portfolio are being reshaped. The analyst consensus Narrative on Simply Wall St leans on that mix as the foundation. Alpha-Pore fits that idea operationally, but by itself it does not change the near term picture in a big way.
The key near term swing factor remains execution in Industrial Solutions and the clean up of Facet related costs and facility moves. The largest risk is that bioprocessing and other high margin Life Sciences areas stay soft or take longer to contribute, which would make it harder for Donaldson Company to lift group margins as planned.
The Alpha-Pore launch sits closest to the existing catalyst that Donaldson Company keeps shifting toward high purity, higher value filtration where content per asset is higher. Longer life sterile filters and stable differential pressure plug directly into that effort to deepen the LifeTec portfolio and increase exposure to complex food and beverage processes.
That matters for the broader thesis that recurring aftermarket and higher margin segments can offset pressure elsewhere, including any lingering operational inefficiencies in Industrial Solutions. The real test will be operational execution, adoption by process customers, and how credibly management at events such as the Baird 2026 Global Industrial Conference ties Alpha-Pore and similar platforms into the margin and cash flow story.
Analysts currently model Donaldson Company reaching US$4.6b in revenue and US$610.5m in earnings by 2029, which implies 5.9% yearly revenue growth and an earnings increase of about US$156.7m from US$453.8m today.
Uncover why Donaldson Company's fair value indicates a 15% potential upside to its current price before the discount to Donaldson Company narrows.
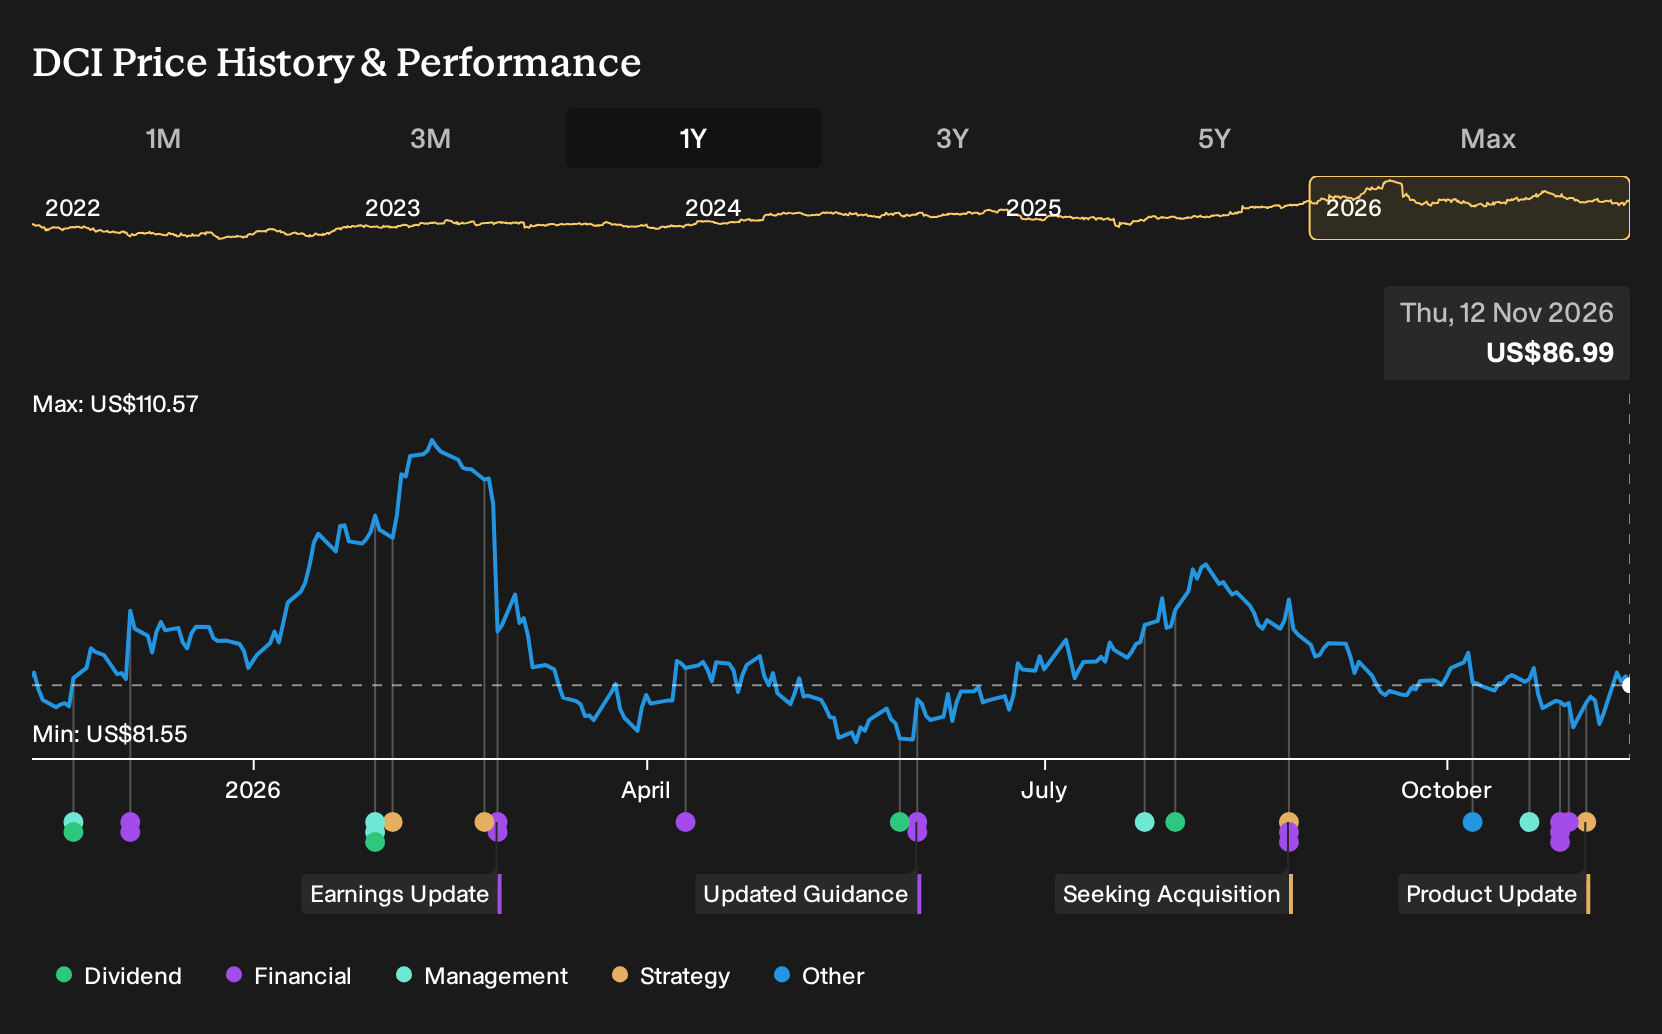
Exploring Other Perspectives
One alternate angle on Donaldson Company puts the power generation ramp front and center. Bullish analysts were already penciling in 7.0% yearly revenue growth and US$630.1m in earnings by 2029 before this Alpha-Pore news. You can treat that as a more optimistic storyline and ask whether these new filtration claims push those forecasts higher or not.
Explore 4 other Donaldson Company fair value estimates, including one that suggests as much as 41% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Donaldson Company research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Donaldson Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Donaldson Company's overall financial health at a glance.
Looking for more investment ideas beyond Donaldson Company?
Once you have a view on Donaldson Company, it helps to widen the lens and stack it up against other businesses that share similar quality signals, balance sheet strength or income potential. The Simply Wall St Screener can surface those types of opportunities quickly so you can compare fundamentals side by side instead of researching each ticker in isolation.
- If you want potential mispricing with stronger underlying fundamentals, start by scanning a curated set of 32 high quality undervalued stocks that may warrant a closer look on cash flow, quality and balance sheets.
- For investors who care most about resilience and downside protection, consider focusing on a 29 resilient stocks with low risk scores that screens for businesses with sturdier financial profiles.
- When you are hunting for fresh ideas off the beaten path, build a watchlist from a 20 high quality undiscovered gems that combines quality metrics with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com