
SulNOx Group And 2 British Growth Stocks To Watch
AI related goods are driving a large share of global trade growth, even as tariffs rise and supply chains are rewired. For fast growing British companies with healthy balance sheets, that surge in digital infrastructure and data spending creates a clear opening. Missing the right businesses could leave investors on the sidelines. This article highlights three high growth UK stocks that match that theme.
The three stocks in this article are just a starting sample, and the full screen surfaced 5 more high growth UK companies with equally compelling narratives that are not covered below. To identify and analyze the highest conviction ideas quickly, head straight to the Best high growth potential screener.
SulNOx Group (OFEX:SNOX)
Overview: SulNOx Group develops and sells organic, biodegradable fuel conditioners that aim to improve fuel efficiency and lower emissions across heavy fuel users.
Operations: The business currently generates about £2.6 million from specialty chemicals, with revenue mainly from Asia at roughly £1.4 million and other international markets.
Market Cap: £41.7 million
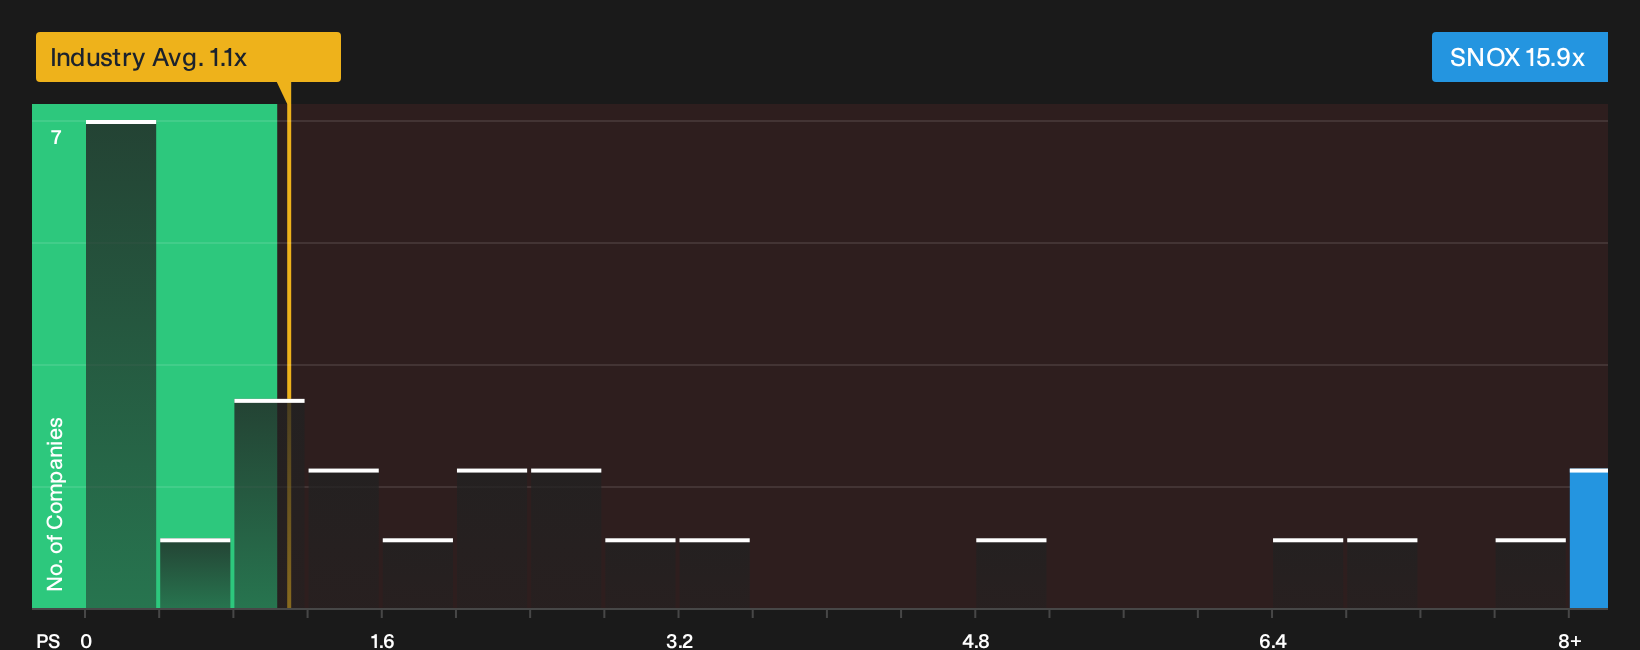
For investors focused on the Best high growth potential theme, SulNOx Group links forecast earnings growth near 90% a year to tangible products already selling into marine, logistics, mining and generator markets. However, 2026 results still show a loss and a high P/S of 15.9x. Interest centres on what happens if a single key assumption about funding and balance sheet resilience breaks.
If that funding hinge matters to you, go straight to the 1 key reward and 1 important warning sign to see what could accelerate SulNOx Group or stall the story.
Gulf Keystone Petroleum (LSE:GKP)
Overview: Gulf Keystone Petroleum develops and produces oil in the Shaikan Field in the Kurdistan Region of Iraq, with growth tied directly to ramping that asset.
Operations: The business generated about US$192.8 million from exploration and production of oil and gas, with roughly US$164.5 million coming from the Kurdistan Region of Iraq.
Market Cap: £420 million
Gulf Keystone Petroleum matters for this high growth potential screen because its Shaikan Field expansion connects forecast revenue and earnings growth directly to higher output, and MacroValue_Research, a Simply Wall St Community investor, argues that recent contract and payment developments could be just as important as the drilling plans themselves.
"In October 2026, SOMO completed the lifting of the maiden top-up crude cargo at Ceyhan (~478k bbl) to reconcile Q4 2025 sales to international Dated Brent prices, establishing operational precedent for contract compliance. The tripartite interim agreement expires on January 31, 2027, transitioning toward a permanent federal revenue mechanism with direct 30-day international settlement cycles."
The real swing factor for Gulf Keystone Petroleum now sits in how that new revenue framework interacts with future Shaikan production and pricing.
That tension between barrels and payments makes the full narrative for Gulf Keystone Petroleum a useful way to see how contract risk, cash returns and future capital allocation could be accelerating or stalled.

Ceres Power Holdings (LSE:CWR)
Overview: Ceres Power Holdings develops and licenses solid oxide fuel cell and electrolysis technologies and products for cleaner power and green hydrogen.
Operations: The group currently records most revenue from Asia at about £32.3 million, with smaller contributions from Europe and North America.
Market Cap: £566 million
Ceres Power Holdings fits the Best high growth potential theme through its Endura based SOFC and SOEC product lines. The analyst consensus Narrative on Simply Wall St describes how that commercial push could translate into faster top-line progress and a shift toward profitability.
"Ceres Power Holdings is rolling out the Endura stack as a single, steel-based solid oxide platform that partners can mass manufacture using standard equipment, which could support higher royalty revenue and improve net margins as more capacity reaches scale."
What happens to those future margins and growth now largely turns on whether one key assumption about partner licensing momentum actually holds.
If that licensing hinge is what you care about, read the full narrative for Ceres Power Holdings to see how partner momentum, cash burn and scaling risk could be accelerating or stalling.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time momentum headlines hit, the best entry points can be gone. Scan under the radar for now, then consider moving early if it fits your strategy.
- Monitor potential income strength by tracking companies screened as 5 dividend fortresses while yields may still compensate you for taking equity risk, before any significant price changes occur.
- Look for early participants in AI infrastructure by scanning 53 AI infrastructure stocks before changing demand conditions affect the pricing of quieter operators.
- Track structural metal demand and review 16 top copper producer stocks while supply developments are still being evaluated and long term trends are still unfolding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com