
Arcutis Biotherapeutics (ARQT) Could Be 30% Undervalued As Guidance Rises
Earnings and Guidance Put Arcutis Biotherapeutics in Focus
Arcutis Biotherapeutics (ARQT) has drawn fresh attention after reporting third quarter 2026 results, posting higher revenue and net income than a year earlier and lifting full year net product sales guidance.
Management now expects 2026 net product sales between US$535 million and US$545 million. For investors, that updated range becomes a key reference point when weighing how the current share price reflects Arcutis Biotherapeutics’ operating performance.
Recent trading tells a mixed story. The share price is around US$27.53 after a 30 day share price return of 5.52% and a 90 day share price return of 5.12%. The 1 year total shareholder return of 20.43% and very large 3 year total shareholder return suggest longer term momentum has been strong as Arcutis Biotherapeutics rolls out ZORYVE and advances new Phase 3 trials alongside fresh leadership changes.
Seize the momentum around Arcutis Biotherapeutics' guidance raise and ZORYVE trial progress by scanning a curated set of 35 healthcare AI stocks that could be riding similar healthcare tailwinds.The recent uptick could reflect investors recalibrating Arcutis Biotherapeutics to stronger reported earnings, or it could simply be sentiment chasing guidance headlines. How does the current share price stack up against those fundamentals?
Most Popular Narrative: 29.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Arcutis Biotherapeutics carries a fair value of $39.13 against the latest close at $27.53. This points to a sizeable valuation gap that investors have to interpret alongside execution risks and pipeline milestones.
The structural shift in topical prescribing toward branded nonsteroidal options, where ZORYVE now holds nearly half of that segment and nonsteroidals have grown to nearly 10% of total topical prescriptions, suggests further conversion away from steroids that can add volume driven revenue and support operating leverage.
Digital access initiatives such as the virtual health platform launched in June 2026 and the AI enabled prescription workflow partnership introduced in July 2026 can simplify prescribing and fulfillment for ZORYVE, which may increase prescription throughput and improve the efficiency of selling costs relative to revenue.
See why 35 investors see Arcutis Biotherapeutics as 30% undervalued.
Result: Fair Value of $39.13 (UNDERVALUED)
Still, the Arcutis Biotherapeutics story leans heavily on ZORYVE execution. Any setback in payer access or weaker prescription trends could quickly challenge that undervalued narrative.
Find out about the key risks to this Arcutis Biotherapeutics narrative.
Another Angle On Arcutis Biotherapeutics’ Valuation
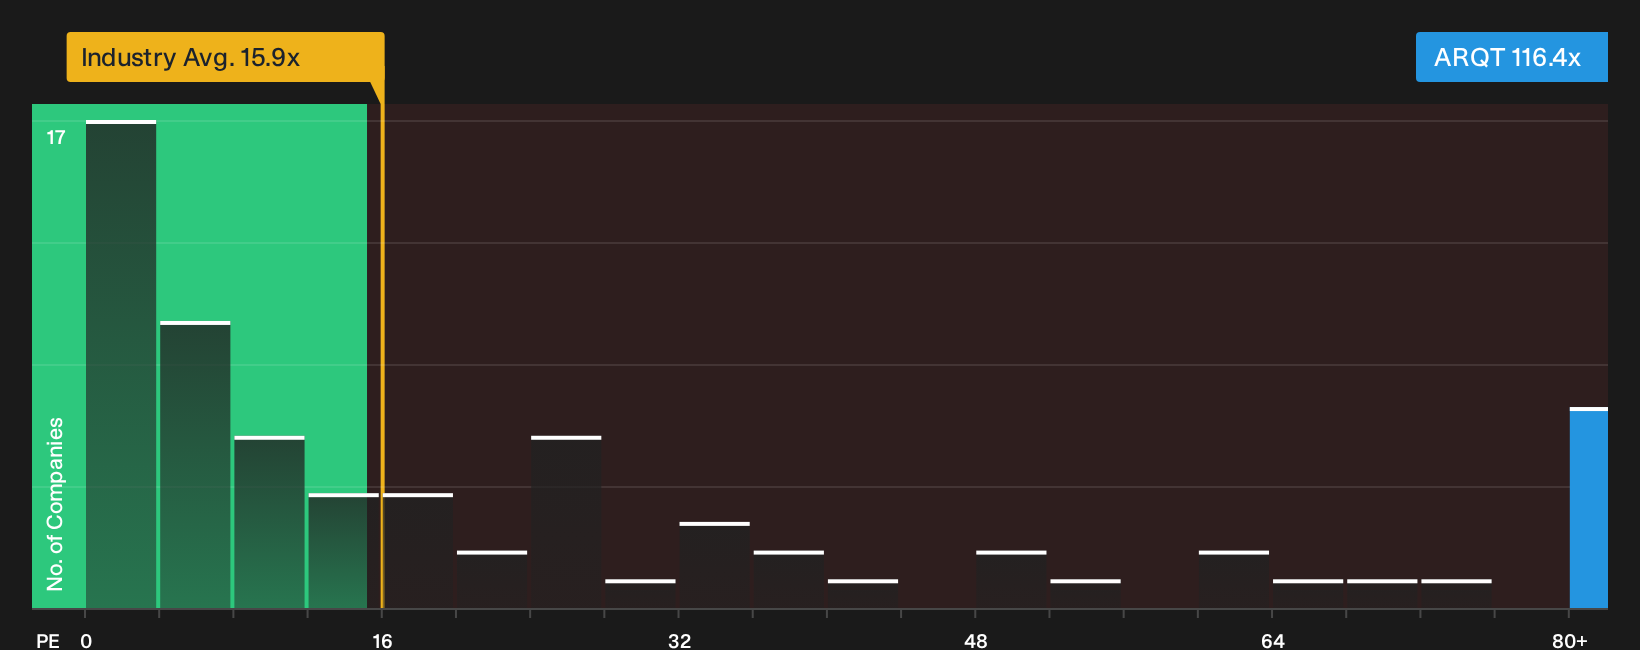
That 29.6% discount to fair value from the analyst Narrative runs straight into a very different picture when you look at simple earnings multiples. Arcutis Biotherapeutics trades on a P/E of 116.4x, while the US Biotechs industry sits near 16x and the fair ratio points to 36.1x, which pushes valuation risk in the opposite direction and leaves you asking which story to trust.
To unpack what such a wide gap to the fair ratio and peers could mean for upside and downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Arcutis Biotherapeutics story so far. Act while the data is fresh and weigh both sides through 4 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Arcutis Biotherapeutics?
If Arcutis Biotherapeutics has your attention, do not stop here. Broaden your watchlist with other clear setups that could round out your portfolio.
- Target fresh potential by scanning 20 high quality undiscovered gems that the wider market may not be watching yet.
- Strengthen your downside protection with a 29 resilient stocks with low risk scores that focuses on resilience when conditions change fast.
- Lock in stronger financial footing by checking a list of solid balance sheet and fundamentals (23 results) before capital flows to the next idea.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com