
Is Box (BOX) Expensive After Its AI Product Push And NVIDIA Tie Up?
Box’s AI product push and why it matters for investors
Box (BOX) has just rolled out Box Architect for agentic workflows, expanded its Box for Industries portfolio, tightened security controls, and deepened AI ties with NVIDIA and Litera. For investors, this cluster of launches raises fresh questions about how the business is positioning itself in enterprise AI and secure content management.
Recent AI announcements have landed alongside a strong run in the Box share price, with the stock at US$43.63 after a 14.6% 1 month share price return and a 51.34% year to date share price return. The 5 year total shareholder return of 77.29% points to gains that long term holders have already captured as momentum has built through 2026.
Scan how Box’s AI push compares to other companies riding a similar wave of demand by exploring 53 AI infrastructure stocks in the current market.
Box now trades slightly above the average analyst target yet still shows a 26.8% gap to one intrinsic value estimate. Is the recent AI-fueled surge already pricing in that spread or not?
Most Popular Narrative: 6% Overvalued
Box closed at $43.63, while the analyst consensus Narrative on Simply Wall St places fair value at $41.14 using an 8.65% discount rate. This frames the current AI optimism against more measured long term assumptions.
The main factor that has to go well is that Enterprise Advanced, AI units and ecosystem partnerships continue to convert Box's large seat expansion and legacy migration pipeline into durable customer spend and net retention.
The current figures on growth, margins and capital returns imply a share price that may not fully reflect Box's potential benefits from higher value per customer and greater AI-driven consumption.
See why 7 investors see Box as 6% overvalued.
Result: Fair Value of $41.14 (OVERVALUED)
Still, Box faces real tests if bundled collaboration suites continue to undercut its pricing power or if higher AI compute costs squeeze margins more than analysts currently factor in.
Find out about the key risks to this Box narrative.
Another View on Box’s valuation
The analyst narrative on Box leans on earnings and P/E style assumptions. A different lens, the Simply Wall St DCF model based on future cash flows, points the other way and flags the stock as undervalued at $43.63 compared with an estimated value of $59.62. Which story feels more realistic to you: a multiple built on forecasts, or a cash flow path you can inspect step by step?
Look into how the SWS DCF model arrives at its fair value.
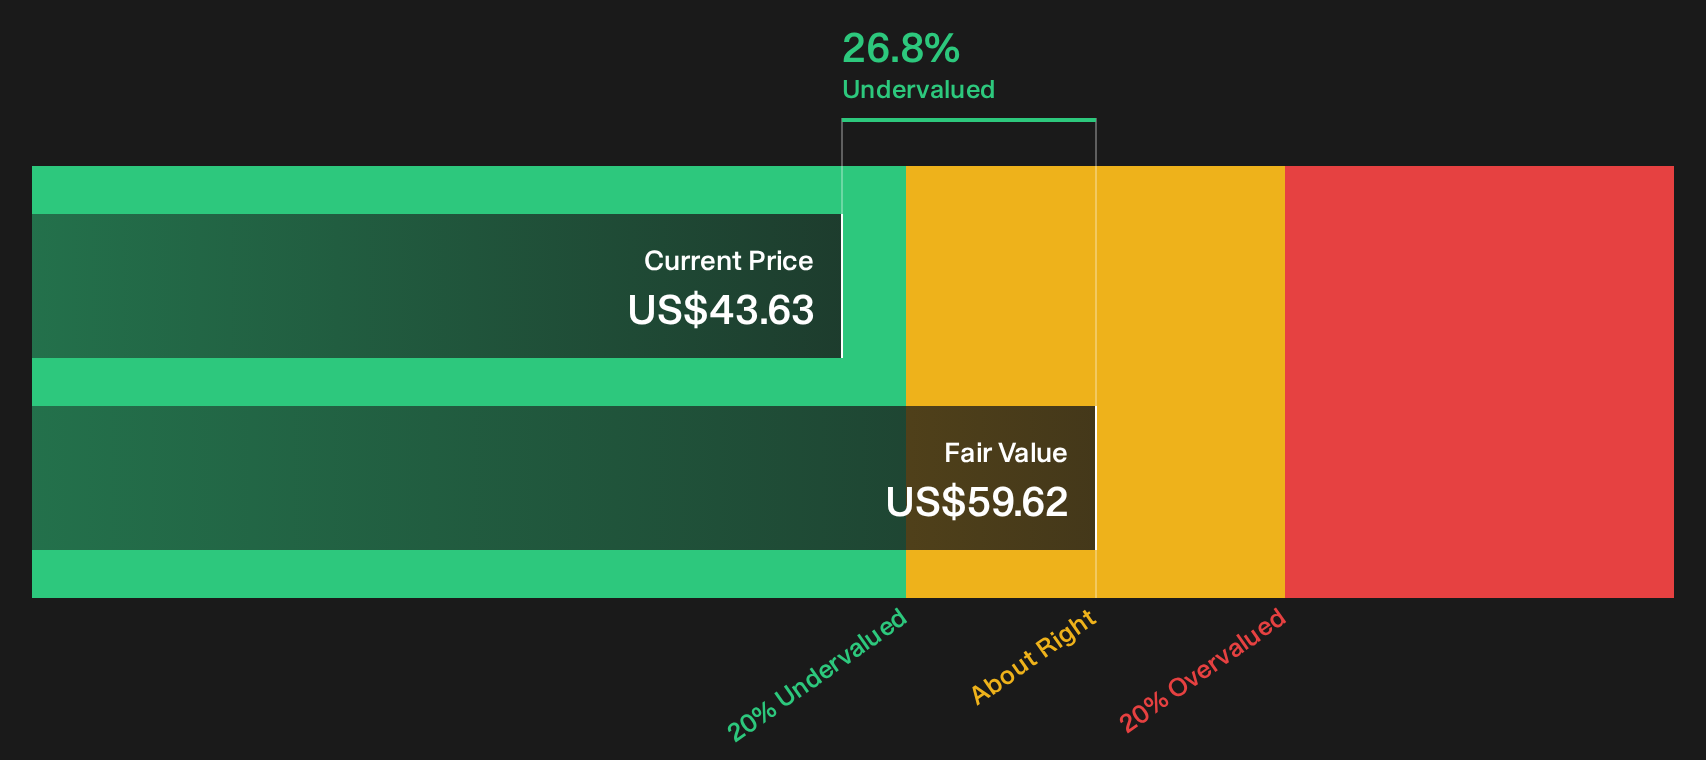
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Box for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Box so far, and that is exactly why it helps to move quickly, compare the risks against the upside, and weigh them for yourself using 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Box?
Once you have sized up Box, it can be helpful to widen your watchlist and pressure test your thesis against other opportunities that fit different roles in a portfolio.
- Target resilience first and filter for sturdier balance sheets by scanning companies in the list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding pressure.
- Hunt for mispriced quality and review the 32 high quality undervalued stocks to see which stocks our models flag as offering more fundamentals per dollar of price.
- Spot potential future leaders early and work through the 20 high quality undiscovered gems before other investors crowd into the same stories and compress the potential upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com