
Earnings Beat Might Change The Case For Investing In NetScout Stock (NTCT)
- NetScout Systems reported second quarter revenue of US$222.19 million and net income of US$34.38 million, with both basic and diluted earnings per share from continuing operations higher than the prior year period.
- The company paired this earnings release with fresh third quarter revenue guidance of US$240 million to US$250 million and a reaffirmed full year 2027 outlook, which indicated management confidence in the current demand pipeline and execution.
- Investors will now be watching how NetScout Systems' reaffirmed full year guidance influences the existing investment narrative related to cybersecurity and AI.
NetScout Systems Investment Narrative Recap
To own NetScout Systems, you need to believe it can keep turning its cybersecurity and service assurance footprint into steady, profitable contracts as networks become more complex and AI driven. The analyst consensus narrative on Simply Wall St already leans on that idea. The latest quarter, with higher net income and EPS than a year ago, fits that story rather than changing it.
The near term swing factor still sits in execution on large cybersecurity and observability deals, especially with enterprise and government clients. The biggest risk remains pressure on legacy products as customers move toward cloud native and consolidated platforms. This earnings release does not remove that concern.
The reaffirmed full year 2027 outlook, with expected revenue between US$885 million and US$915 million and GAAP EPS guidance of US$1.55 to US$1.70, is the announcement that ties most directly to the latest results. It links NetScout Systems' recent earnings trajectory to management’s operational plan for the rest of the year.
For you as a shareholder prospect, that range frames the next catalyst. Delivery against the US$240 million to US$250 million third quarter revenue guide, and progress toward the full year revenue and net income targets, will likely shape how much confidence investors place in the cybersecurity growth story and in NetScout Systems' ability to manage mix shifts away from older offerings.
Analysts currently model NetScout Systems reaching US$954.2 million in revenue and US$122.2 million in earnings by 2029. That outlook lines up with forecast annual revenue growth of 3.5% and implies an earnings increase of about US$26.7 million from the US$95.5 million reported today.
Uncover why NetScout Systems' fair value indicates a 28% potential upside to its current price before that discount to expectations tightens.
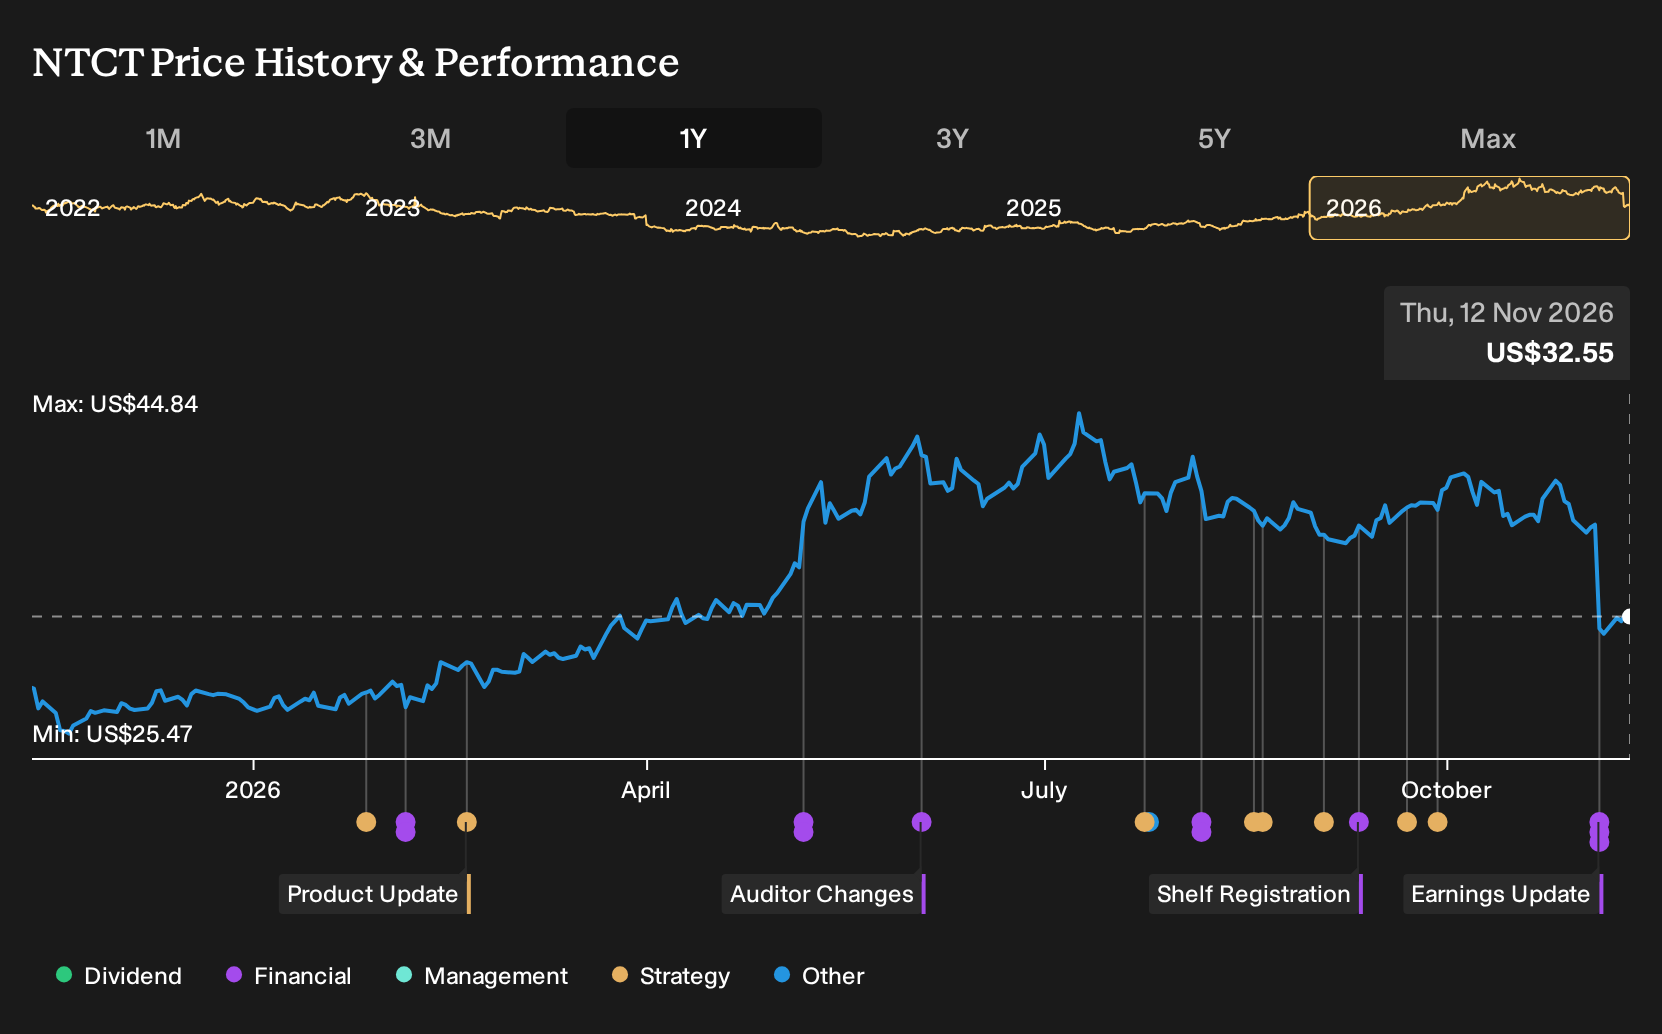
Exploring Other Perspectives
One alternate angle on NetScout Systems focuses less on AI upside and more on whether high government and enterprise spending can really last. The most optimistic analysts were penciling in about US$959.3 million of revenue and US$106.8 million of earnings by 2029 before this report, and they implied a much higher P/E. Those forecasts have not absorbed the new quarter yet, so treat them as one possible scenario rather than a script and compare several viewpoints before deciding what this latest guidance might mean for you.
Explore 4 other NetScout Systems fair value estimates, including one that suggests up to 119% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your NetScout Systems research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for NetScout Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate NetScout Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond NetScout Systems?
If the NetScout Systems story has you thinking about where else dependable earnings, strong balance sheets, or income potential might come from, the Simply Wall St Screener can help you scan for other stocks that fit your style in a few clicks.
- For investors who want potential growth at lower entry prices, check out 11 elite penny stocks with strong financials that already show solid financial underpinnings.
- If you prefer quality businesses that may be trading below what their fundamentals suggest, start with a 32 high quality undervalued stocks that could warrant a closer look.
- For readers focused on income, consider a shortlist of 6 dividend fortresses that combine meaningful payouts with the potential for capital stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com