
Did Strong Nine Month Results Just Shift IONOS Group's (XTRA:IOS) Investment Narrative?
- IONOS Group SE reported results for the nine months to 30 September 2026 with revenue of €1,054.56 million and net income of €180.44 million, alongside higher basic and diluted earnings per share from continuing operations compared with the same period in 2025.
- The business also highlighted customer numbers reaching about 7 million and confirmed its 2026 outlook, which links the latest earnings run-rate to its existing plans for revenue growth and adjusted EBITDA.
- Now the focus shifts to how IONOS Group's reaffirmed 2026 outlook fits with its longer term investment narrative around AI and cloud.
Scan beyond IONOS Group to compare its AI and cloud peers by checking our hand-picked 53 AI infrastructure stocks shaping the next leg of digital infrastructure demand.
IONOS Group Investment Narrative Recap
To own IONOS Group, you need to be comfortable with a business that is pushing hard into AI led web presence tools and sovereign cloud, while still spending heavily on infrastructure. The latest nine month figures show revenue of €1,054.56 million and net income of €180.44 million, which broadly supports that operating thesis without changing it in a dramatic way.
The short term swing factor remains whether the firm can convert AI products and cloud contracts into higher margin subscription revenue while keeping customer growth near the recent 7 million level. The biggest near term risk still sits around front loaded cloud CapEx and softer free cash flow if spending on hardware and marketing stays elevated.
The analyst consensus Narrative on Simply Wall St leans heavily on AI products and cloud capacity as key earnings drivers, and the reaffirmed 2026 outlook ties directly into that. Management expects currency adjusted revenue growth of about 8% and adjusted EBITDA of roughly €530 million, which connects the current earnings run rate to that AI and cloud heavy plan.
For you, the practical question is whether IONOS Group can execute that roadmap while managing known pressure points like higher CapEx, restructuring in the AdTech unit and a balance sheet that carries a high level of debt. If execution on AI subscriptions and public and sovereign cloud contracts stays on track, those elements can remain important catalysts for sentiment around the stock.
IONOS Group's current investment story lines up with analysts who are modelling 9.1% yearly revenue growth, current earnings of €231.5 million and consensus earnings of €397.8 million by 2029. This implies an earnings increase of about €166 million. To square that view with the stock price, those same forecasts point to around €1.8b of revenue and €397.8 million of profit in 2029.
Uncover why IONOS Group's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
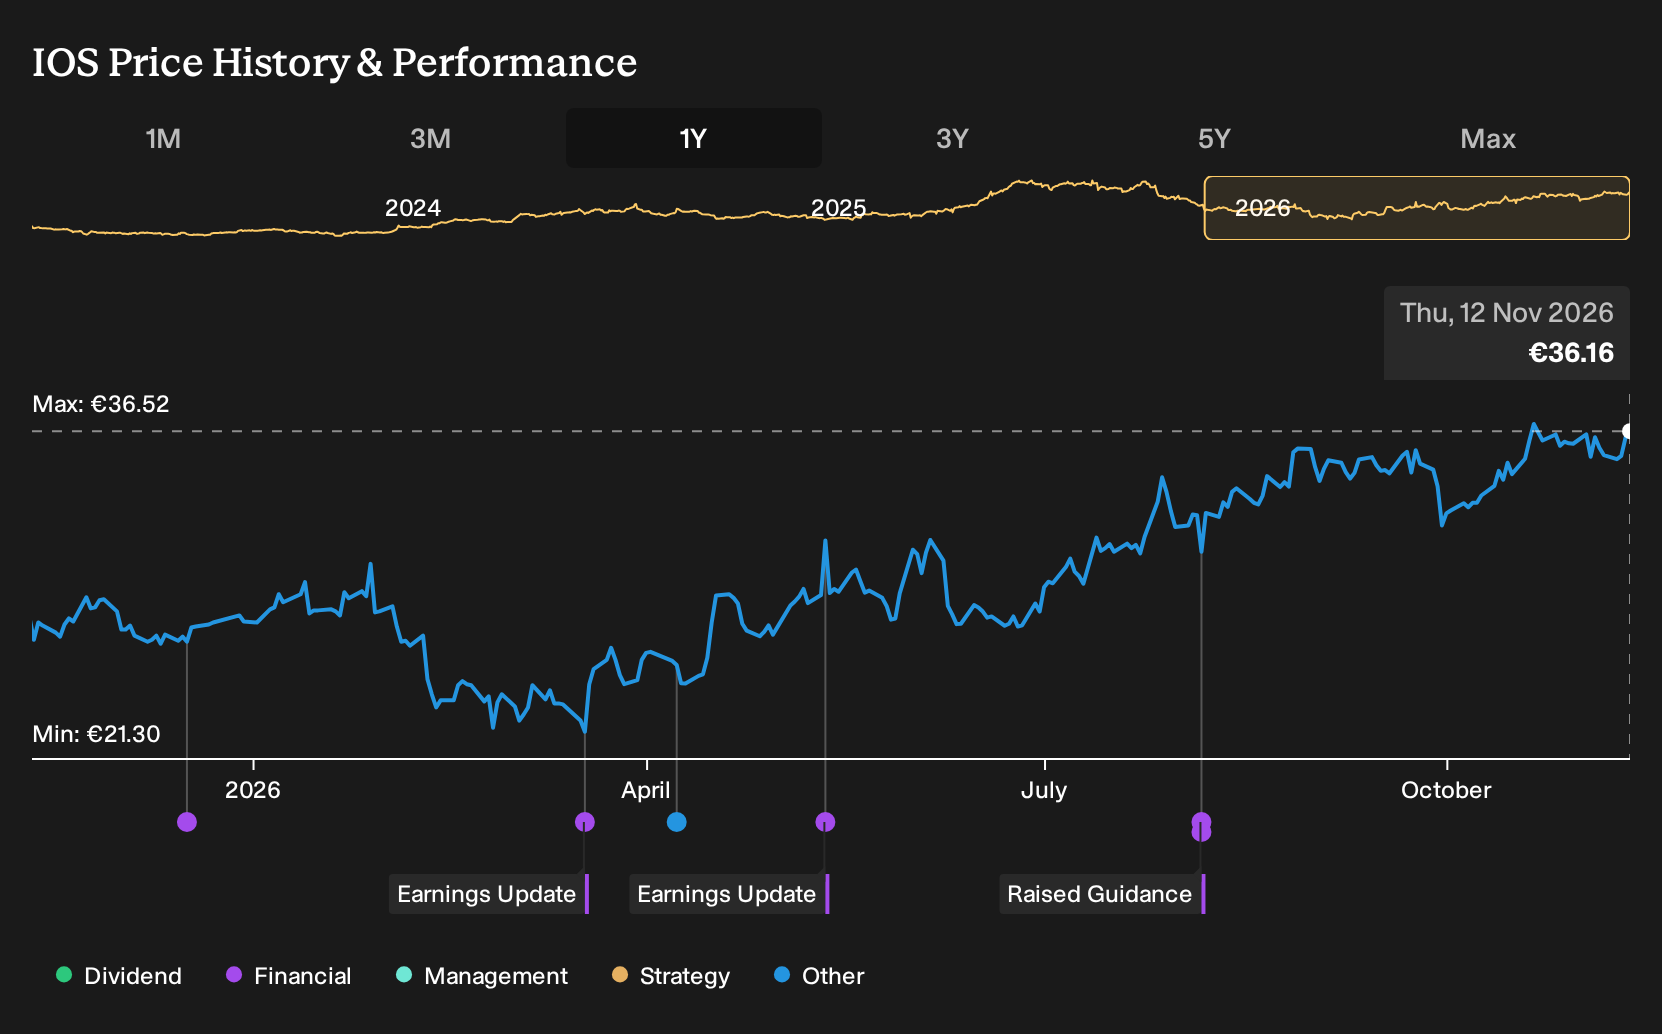
Exploring Other Perspectives
One bullish twist on IONOS Group focuses on cloud margins rather than AI upsell. The most optimistic analysts were pencilling in revenue of about €1.9b and earnings of €471.6 million by 2029 before this update, which is far above consensus. Use this earnings release as a prompt to compare those competing stories.
Explore 3 other IONOS Group fair value estimates, including one that suggests potential upside of as much as 69% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your IONOS Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IONOS Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IONOS Group's overall financial health at a glance.
Looking for more investment ideas beyond IONOS Group?
IONOS Group might fit one part of your watchlist, but your capital is rarely a one stock story. Use the Simply Wall St Screener to line up alternatives that match different goals, then weigh IONOS Group against what else is out there.
- If you want potential growth with limited balance sheet strain, scan a 205 resilient stocks with low risk scores that score well on resilience and financial risk.
- For investors who care about stability and income together, review a curated 216 dividend fortresses that combine higher yields with underlying business strength.
- To cast a wider net for future watchlist candidates, sift through a 565 high quality undiscovered gems that show solid fundamentals but attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com