
Pulse Biosciences (PLSE) Stock Looks Overvalued Even With Clinical Progress
Pulse Biosciences has delivered an extremely strong share price run in recent years, which naturally raises the question of whether a US$52.25 stock is still grounded in the company’s book value. With the price now reflecting years of optimism and recent clinical milestones, investors are asking how much of the balance sheet strength is already baked in.
- Pulse Biosciences has returned roughly 7x over the past 3 years, putting substantial weight on whether its current valuation can still be anchored to its underlying net assets.
- Early completion of enrollment in the NANOPULSE-AF study and progress toward CE Mark submission may support expectations for future commercialization, which can influence how much of today’s price investors are willing to tie to the company’s existing equity base.
- Your read on Pulse Biosciences is one view; the desks covering it have another. See what analysts think Pulse Biosciences's shares could be worth.
For investors, the debate is whether Pulse Biosciences' current share price is adequately supported by its book value when set against the industry average.
If you are weighing Pulse Biosciences against other possibilities, a focused stock screen can help you compare its rich recent run with 32 high quality undervalued stocks.
Does Pulse Biosciences Look Pricey on Book Value?
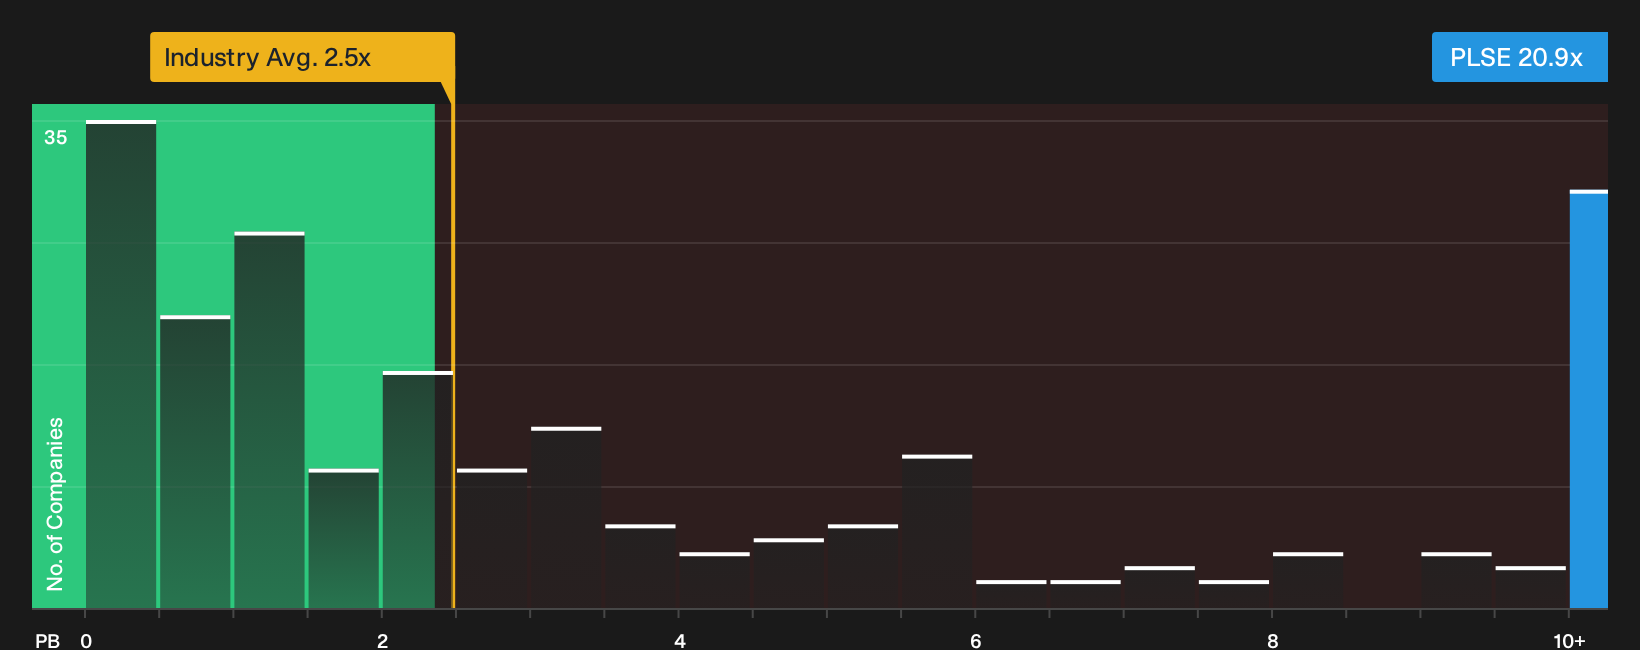
For Pulse Biosciences, P/B is a useful lens because investors are largely paying for its equity base and pipeline rather than established earnings. The stock trades on a P/B of about 20.9x, compared with roughly 2.5x for the wider Medical Equipment group and around 7.0x for close peers. That is a steep premium in simple balance sheet terms, so holders are effectively assigning far more value to each dollar of net assets than is typical in the sector.
Early completion of enrollment in the NANOPULSE-AF study and progress toward CE Mark submission help explain why some investors are willing to accept that premium. However, the current 20.9x level still screens as overvalued against the industry benchmark. For anyone considering Pulse Biosciences at this price, the key question is whether the clinical progress and future commercialization potential justify such a rich multiple, or whether expectations have already run ahead of what the balance sheet currently supports. Explore the numbers behind Pulse Biosciences's P/B valuation.
The Pulse Biosciences Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Pulse Biosciences take the valuation puzzle a step further and spell out what would need to happen to growth, margins and earnings for the stock to be worth materially more or materially less than today’s price. These narratives sit on the platform’s Community page. Rather than a single multiple or model output, each narrative lays out the key assumptions sitting behind its fair value estimate so you can see how those assumptions stack up as new results arrive.
One of the top narratives on Pulse Biosciences: 22% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Growing clinical evidence through PRECISE BTN, NANOCLAMP AF, and European feasibility studies is expected to strengthen reimbursement, support guideline inclusion, and drive higher procedure adoption…"
Discover why this Narrative puts Pulse Biosciences at 22% undervalued.
Pulse Biosciences: why the price tag is only half the story
Headline ratios tell only part of what you need to know about Pulse Biosciences, because recent checks have thrown up risk factors that deserve a closer look before you rely on the valuation alone. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com