
HubSpot (HUBS) After Halligan’s Return Is The Stock A Bargain Or Fairly Valued
HubSpot (HUBS) just paired a busy third quarter earnings release with fresh guidance and multiple buyback updates, all against the backdrop of co founder Brian Halligan returning as chief executive.
Recent trading tells a mixed story for HubSpot. The share price jumped 6.39% on the day of the earnings and leadership news and is up 5.31% over the past week. However, the 30 day and 90 day share price returns are slightly down and the year to date share price return has fallen 43.53%. This has contributed to a 1 year total shareholder return decline of 44.74% and a 5 year total shareholder return drop of 74.31%, which indicates near term enthusiasm alongside longer term pressure as investors reassess growth prospects and risk around the new buybacks and management reset.
Scan how other software and AI platform stocks are reacting to management resets and buybacks with a curated list of 20 high quality undiscovered gems that currently sit off most investors' radar.After a sharp reset in HubSpot’s share price and a fresh US$1.0b buyback paired with Halligan’s return, the real issue now is simple: Does the current valuation still skew the risk reward toward buyers?
Most Popular Narrative: 16% Undervalued
HubSpot closed at $215.84, while the analyst consensus Narrative on Simply Wall St places fair value at $257.67, indicating a material gap that now frames the debate around Halligan’s return and the new buyback firepower.
HubSpot is a direct beneficiary of the rapid digitization of SMBs and enterprises, as more customers consolidate their marketing, sales, and service stacks onto integrated cloud platforms like HubSpot. This is evidenced by rising multi-hub adoption and seat upgrades, which should drive recurring revenue and higher average revenue per customer over time.
The company's quick pivot to adapt to shifting buyer behavior, such as declining traditional SEO and the rise of AI-powered search, positions HubSpot to capture new sources of lead generation (YouTube, social, newsletters, LLM citations). This supports customer growth and improves the durability of top-line expansion.
See why 69 investors see HubSpot as 16% undervalued.
Result: Fair Value of $257.67 (UNDERVALUED)
Still, the narrative around HubSpot can shift quickly if AI monetization remains slow, or if competition and SMB budget pressure continue to weigh on new customer demand.
Find out about the key risks to this HubSpot narrative.
Another Take On HubSpot’s Valuation
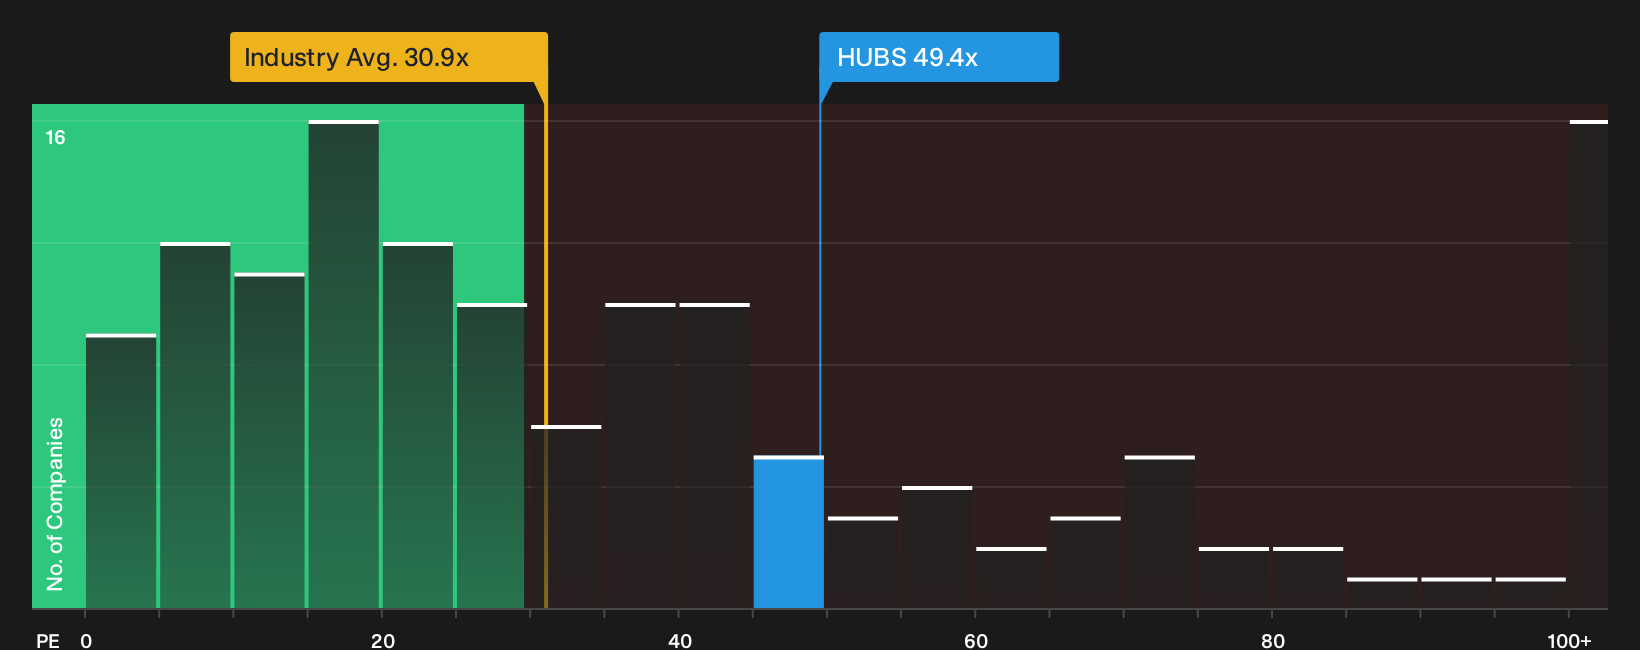
The story looks different when you leave fair value models aside and focus on what the market is actually paying for HubSpot. The stock trades on a P/E of 49.4x, compared with about 30.9x for the broader US Software group and 45.9x for closer peers, while the fair ratio sits higher at 59.9x. That mix points to a rich entry tag today but also to room for the multiple to move if sentiment or earnings expectations shift again. Where does that leave your own comfort zone on price versus growth risk?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around HubSpot is clearly split, which is exactly when fresh eyes on the numbers matter most. Move quickly, review the underlying drivers, and pressure test the upside by weighing the 3 key rewards.
Looking For More HubSpot Sized Investment Ideas?
Do not stop at HubSpot. Put fresh names on your watchlist now, or you risk missing opportunities that better match your own risk and return preferences.
- Target dependable compounding by scanning a 6 dividend fortresses that focuses on income potential backed by higher yields.
- Hunt for mispriced opportunities through a 32 high quality undervalued stocks that filters for quality businesses trading below assessed worth.
- Protect your downside first by running a 29 resilient stocks with low risk scores built around resilient balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com