
Is Enova International (ENVA) Undervalued On Its $500 Million Buyback And Debt Refinance?
Enova International (ENVA) just rolled out a new share repurchase plan of up to US$500 million that runs through June 30, 2028, along with fresh debt refinancing and a larger revolving credit facility.
All this capital activity from Enova International comes after a sharp reset in sentiment, with the share price down about 37% over the past 90 days but still showing a 3.1% gain year to date.
For longer term holders, the picture looks very different, since the 1 year total shareholder return is about 30.8% and the 3 year total shareholder return is a little more than 3x, which suggests the recent share price weakness contrasts with what has been a strong multi year run.
The fresh US$600 million bond issuance, the larger revolving facility and the new US$500 million buyback authorization now sit against that backdrop. Together, these actions can signal that management views the current share price as an efficient level at which to return capital and reshape the balance sheet.
Spot opportunities with similar balance sheet and capital return stories by scanning the list of solid balance sheet and fundamentals (23 results). This may echo what is playing out at Enova International.Enova International just saw a sharp reset after a multi year surge, and management is committing US$500 million to buybacks at this level. Is the real upside still ahead, or was most of it already captured on the way up?
Most Popular Narrative: 30% Undervalued
Compared with the last close at $167.01, the analyst consensus Narrative on Simply Wall St anchors Enova International’s fair value at $238.50. This frames the new $500 million buyback against a stock that this framework views as materially discounted.
The ongoing migration of small businesses and consumers toward digital lending, supported by preferences for speed and convenience, continues to drive strong demand and originations for Enova International, with recent double digit originations and revenue growth indicating potential for further revenue expansion if these preferences persist.
Enova International's use of advanced machine learning and AI for real time, data driven credit risk management is now extending into generative AI and automated final decisioning at OnDeck, which is cutting funding decision times to under a minute and could support lower credit losses and higher net revenue margins.
See why 11 investors see Enova International as 30% undervalued.
Result: Fair Value of $238.50 (UNDERVALUED)
Still, tighter consumer lending rules or a period of weaker funding markets could quickly pressure Enova International’s margins and limit how far this AI driven thesis can run.
Find out about the key risks to this Enova International narrative.
Another View On Enova International’s Valuation
The analyst narrative and fair value of $238.50 lean on future earnings assumptions. The SWS DCF model paints a different picture, with an estimate of future cash flow value at $106.74 and the current $167.01 share price sitting above that. Which set of expectations do you trust more?
Look into how the SWS DCF model arrives at its fair value.
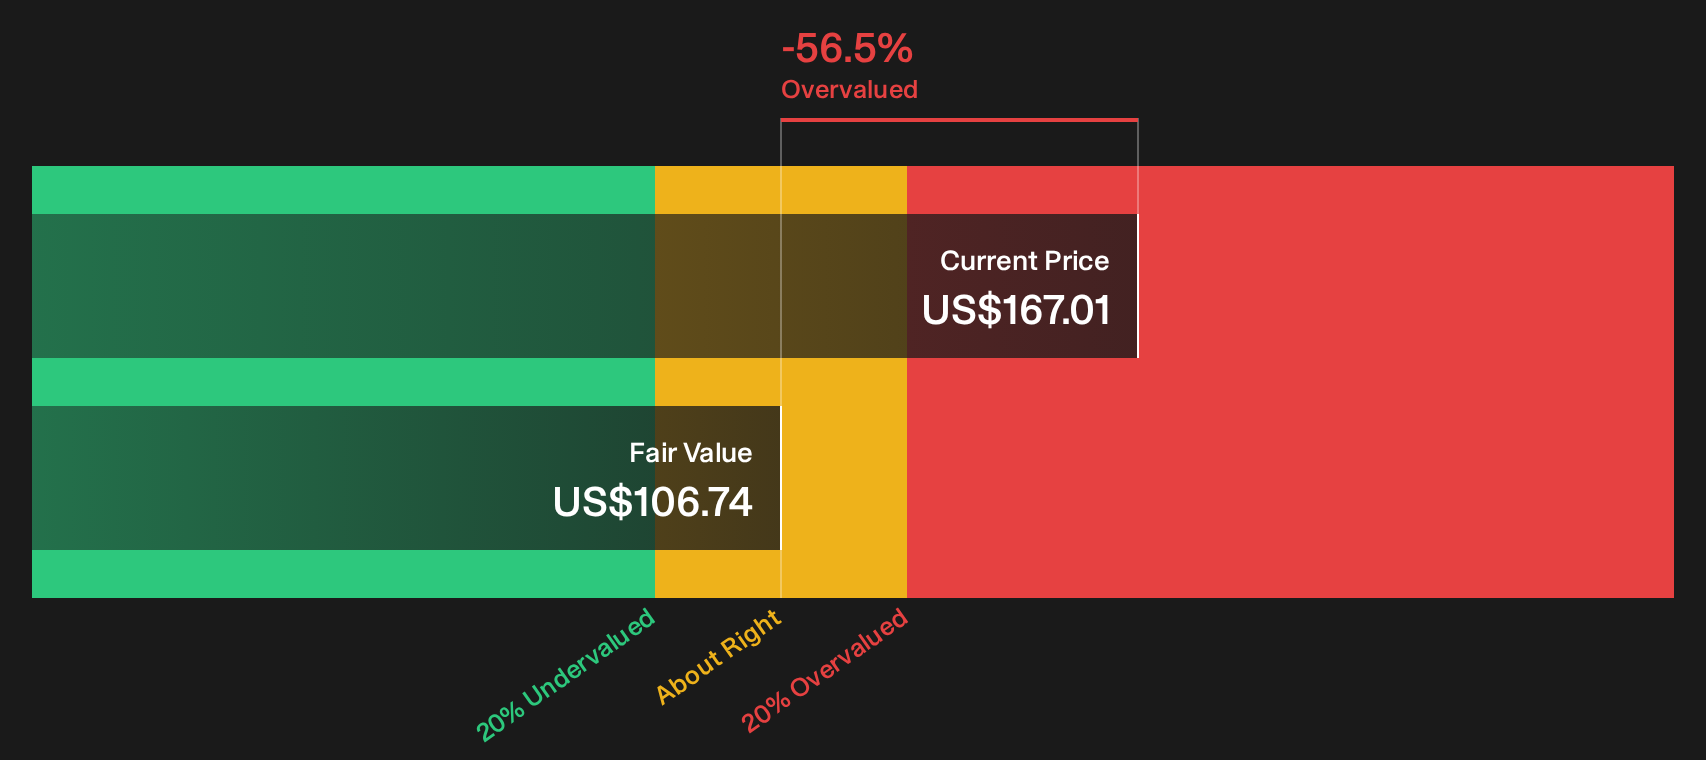
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Enova International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in the Enova International story so far. Act quickly on your curiosity, review the full data set, and weigh the 4 key rewards and 2 important warning signs for yourself.
Looking for more investment ideas beyond Enova International?
If Enova International has your attention, do not stop here. Put the same scrutiny to work across fresh opportunities and widen your opportunity set intelligently.
- Target strong balance sheets and resilient cash generation by running companies through the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality where fundamentals and valuation can align by scanning the 20 high quality undiscovered gems.
- Prioritise resilience and capital protection by focusing on candidates screened as 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com