
Liberty Energy (LBRT) Rises On Persian Gulf Supply Fears While Undervalued Narrative Holds
How Geopolitics In The Persian Gulf Fed Into Liberty Energy’s Recent Move
Heightened risks to crude shipments in the Persian Gulf, including reported attacks on tankers, pushed oil prices higher and helped lift Liberty Energy (LBRT) as investors focused on supply security.
The latest move in Liberty Energy slots into a choppy year, with a 7 day share price return of 13.83% following a 30 day decline of 32.39% and a 90 day drop of 41.30%. At a recent share price of US$12.92, the 1 year total shareholder return is down 14.14%, while investors who have held for 5 years still show a 38.80% total shareholder gain. This indicates that long term holders have fared better than more recent buyers as sentiment has cooled.
Scan for other energy service stocks that could react to similar supply shocks by running the 43 power grid technology and infrastructure stocks alongside Liberty Energy on your watchlist.
That rebound, after such a steep few months, puts Liberty Energy at an interesting crossroads. Does the recent pricing shock leave more upside than downside for new buyers, once you strip it back to valuation?
Most Popular Narrative: 52% Undervalued
Liberty Energy's analyst consensus Narrative on Simply Wall St places fair value at $27.00 compared with the recent $12.92 close, framing a wide valuation gap that rests heavily on its power buildout and completions cash flow holding together.
The main thing that has to go right is Liberty Energy successfully executing its capital intensive pivot toward a 3 GW distributed power platform while keeping its frac fleets tightly utilized and cost efficient through digiTechnologies and AI driven tools.
The current valuation implies the market is discounting Liberty Energy’s plan to deploy roughly 3 GW of on site power with targeted 5 to 6 year cash on cash paybacks and double digit unlevered returns, while also questioning how much of the tight frac and energy security backdrop will translate into durable cash generation for shareholders.
Find out how 9 investors see Liberty Energy as 52% undervalued.
Result: Fair Value of $27.00 (UNDERVALUED)
Still, Liberty Energy’s heavier 2026 capex plan of about US$1.5b and delayed power earnings contribution until at least 2028 could easily challenge that undervaluation story.
Find out about the key risks to this Liberty Energy narrative.
Another Take On Liberty Energy’s Valuation
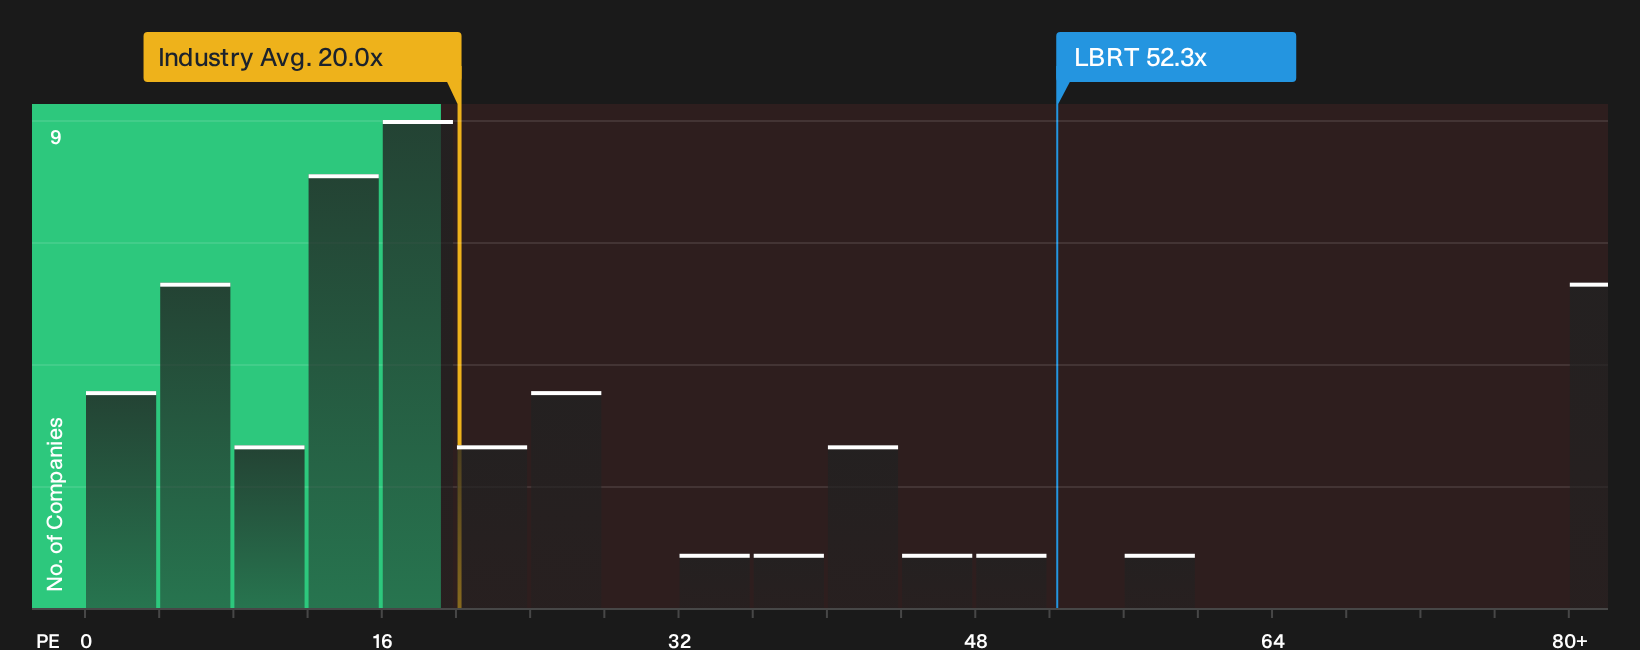
The first narrative paints Liberty Energy as 52% undervalued, yet the current P/E of 52.3x tells a different story. That is roughly double the US Energy Services industry at 20.4x, about 2x peer averages at 27.7x, and well above a fair ratio of 12.5x. That kind of gap can matter for anyone weighing upside against the risk that sentiment cools further.
Our valuation work that leans on this earnings multiple view raises a simple question. If the share price were to drift closer to that 12.5x fair ratio, would you see that as a reset or as an opening?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Liberty Energy has you torn, consider promptly stress testing your own thesis using the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Liberty Energy?
Do not stop at Liberty Energy. Fresh ideas often come from scanning outside your usual watchlist, and the right filter can surface opportunities you might otherwise miss.
- Target potential upside by focusing on quality companies that trade below estimated worth through the 32 high quality undervalued stocks.
- Strengthen your income stream by zeroing in on resilient payouts using the 6 dividend fortresses.
- Dial down portfolio stress by concentrating on sturdier finances with the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com