
3 Canadian Value Stocks To Watch In November 2026
AI related investments are pushing bond yields higher again, which puts pressure on richly priced Canadian stocks whose cash flows are more distant and uncertain. That creates a window for investors willing to focus on companies where current and near term cash generation looks solid relative to the share price. This article highlights three Canadian listings that our cash flow valuation screen flags as trading below estimated fair value today.
The three ideas covered next are just a sample, as the full cash flow screen also surfaced 6 more Canadian companies with equally compelling valuation stories that are not unpacked here. To see the full picture, head straight into the Undervalued Stocks Based On Cash Flows screener to analyze, filter, and identify the cash flow opportunities that best fit your approach.
Stantec (TSX:STN)
Stantec is a global design and consulting group focused on infrastructure, buildings, environmental work, and especially long term water and infrastructure programs that can underpin recurring, contract backed cash flows. Revenue is spread across Canada at about CA$1.6b, the United States at roughly CA$3.6b, and global operations at around CA$1.7b, while the stock’s market value sits near CA$12.1b.
The analyst consensus Narrative on Simply Wall St points to Stantec as a business where water focused and broader infrastructure projects could convert a large book of work into meaningful cash flow over time, if current execution continues.
"Demand for infrastructure upgrades, water and wastewater treatment, energy transition and climate adaptation projects remains very strong globally. This is reflected in double digit organic growth in Water across multiple regions and a record contract backlog of about $9.2b, which points to an extended runway for net revenue and earnings growth as multi year projects are executed."
What happens to that cash flow story depends heavily on how one less visible pressure shapes future profitability.
If that pressure on profitability is what you are weighing up next, read the full narrative for Stantec to see how Stantec’s backlog, pricing and capital intensity could be decoupling.
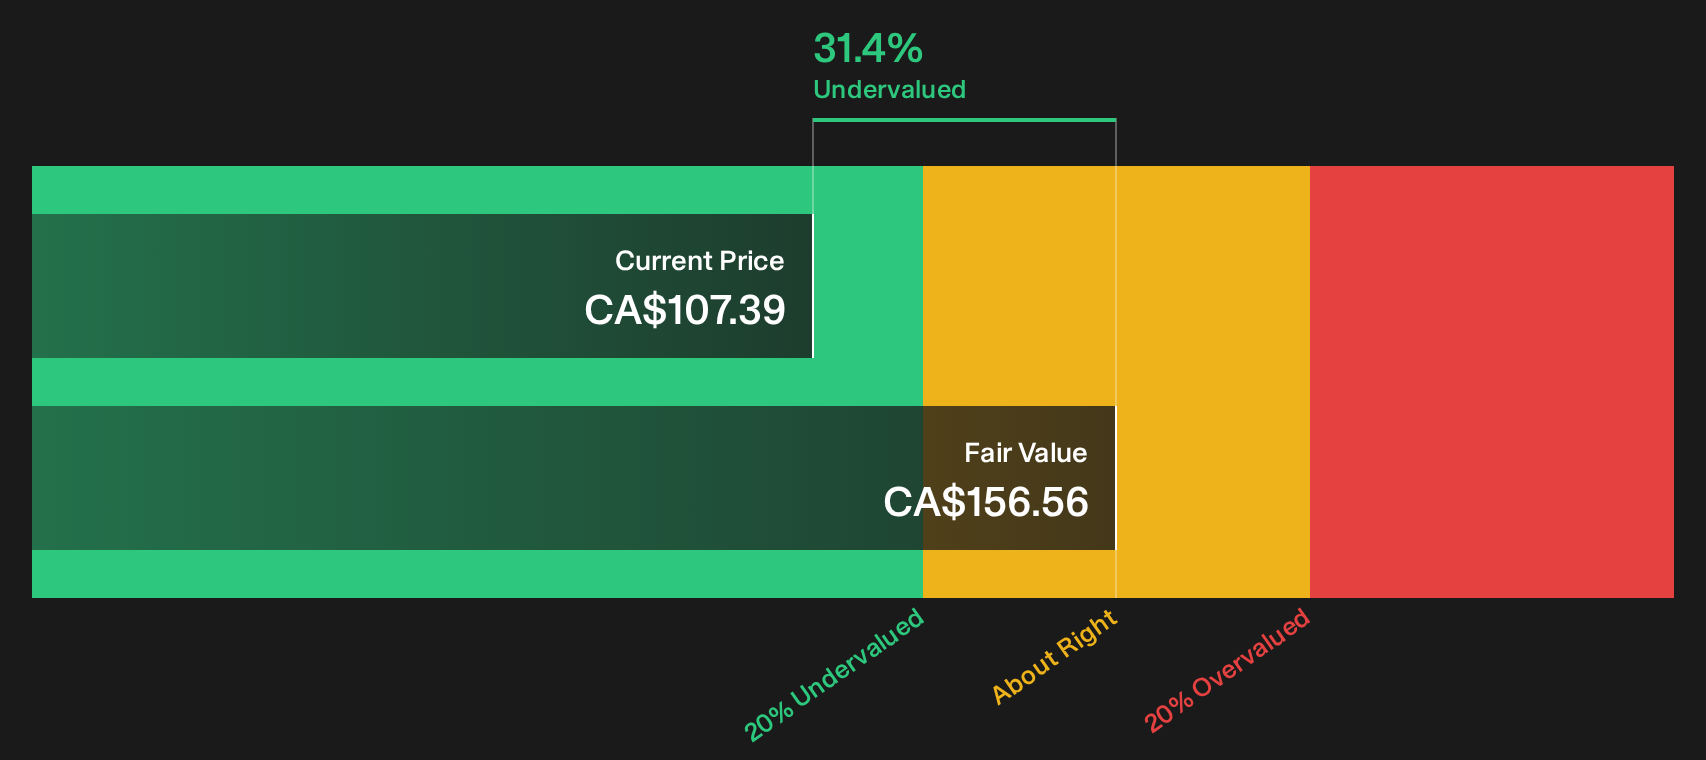
Barrick Mining (TSX:ABX)
Barrick Mining is a large Toronto based miner that earns most of its money from long life gold and copper operations like Carlin at about $5.3b, Cortez near $3.2b and Pueblo Viejo around $2.9b, contributing to a business valued near $90.7b.
The draw with Barrick Mining for this cash flow focused screen is how its long life gold and copper assets can shape future free cash generation. The analyst consensus Narrative on Simply Wall St highlights one project level shift that could be especially important here.
"Agreement with Newmont to restructure the Nevada Gold Mines joint venture, including bringing Fourmile and Newmont’s Mike and Fiberline assets into the JV and resolving historic disputes, is expected to let Barrick Mining reconfigure processing capacity, reduce ore trucking and pursue higher throughput in Nevada, which would directly affect group revenue and unit cash costs."
What ultimately matters is how that operational reset interacts with one less visible trade off that could move both margins and valuation expectations.
That trade off is exactly what the full narrative for Barrick Mining unpacks in detail, including how operational choices in Nevada could accelerate or stall Barrick Mining’s cash generation story.
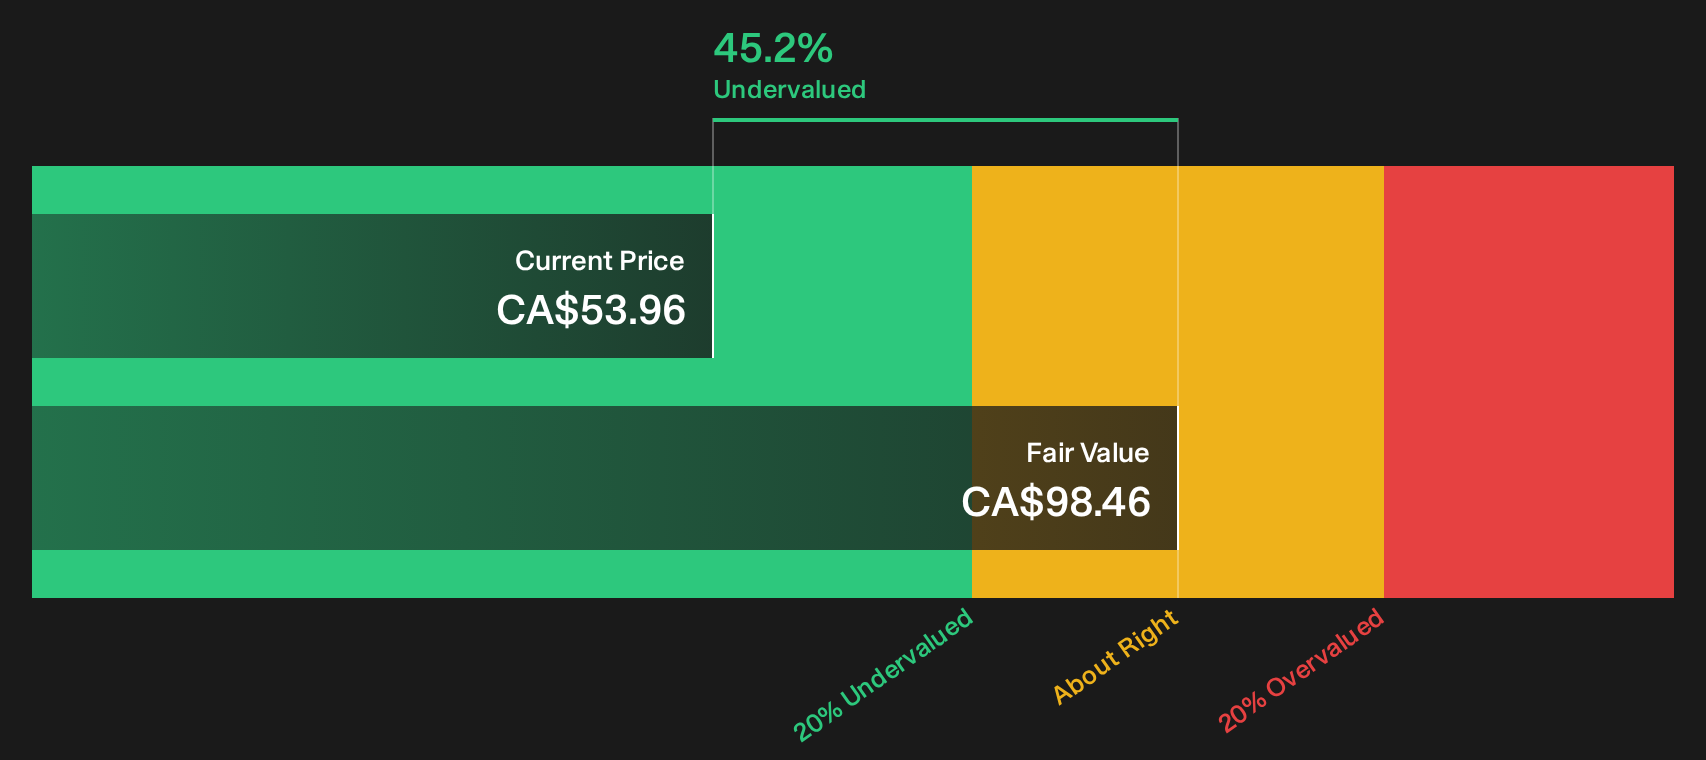
CGI (TSX:GIB.A)
CGI is a Montreal based IT and business process services group, best known for long term managed IT, cloud migration and FinOps enabled cloud management contracts that support recurring cash flows, and it is valued at about CA$23.6b.
For investors following the Undervalued Stocks Based On Cash Flows theme, CGI lines up neatly, because the bullish analyst Narrative on Simply Wall St ties its recurring cloud and managed services work directly to a discounted cash flow valuation case built on predictable earnings.
"As CGI moves from AI pilots to embedding AI in about 65% of IT solutions and in every new managed services proposal, internal tools such as DigiOps, AIOps Nova and AI developer assistants that are already lifting revenue per employee can create further delivery efficiency and support EBIT margin resilience and earnings quality."
One question for investors is what happens if a quiet shift in how CGI wins and prices long duration, AI rich cloud contracts ultimately determines whether those margins hold.
If that contract shift is what you are trying to gauge, the full narrative for CGI maps how CGI’s AI heavy deal mix could accelerate or quietly cap future cash generation.
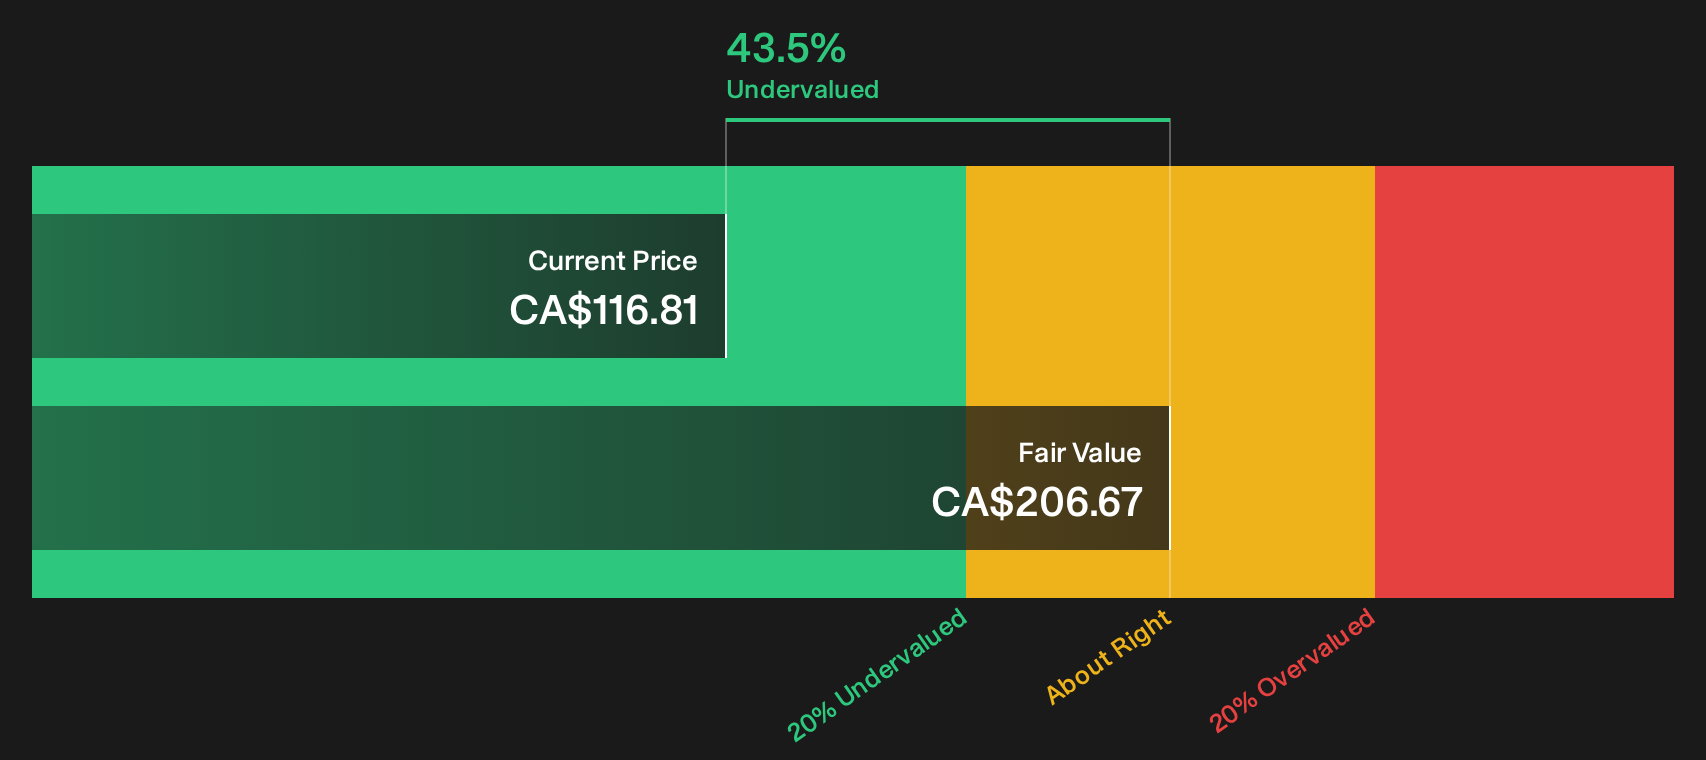
Seeking Fresh Alternatives Before Others
Fresh ideas move first when momentum builds, and slower investors get caught chasing breakouts after prices start flying. Scan these under the radar lists while it matters and act now.
- Target durable income streams by reviewing potential high yield payers inside the 3 dividend fortresses before yields drop and the strongest options are priced for perfection.
- Track where AI momentum quietly gathers by scanning the curated list of 53 AI infrastructure stocks while these infrastructure plays are still under the radar for now.
- Hunt for resilient balance sheets and steady cash generation across the hand picked list of solid balance sheet and fundamentals (5 results) before early interest starts driving valuations higher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com