
How Investors Are Reacting To Equinix (EQIX) Green Bond Offering
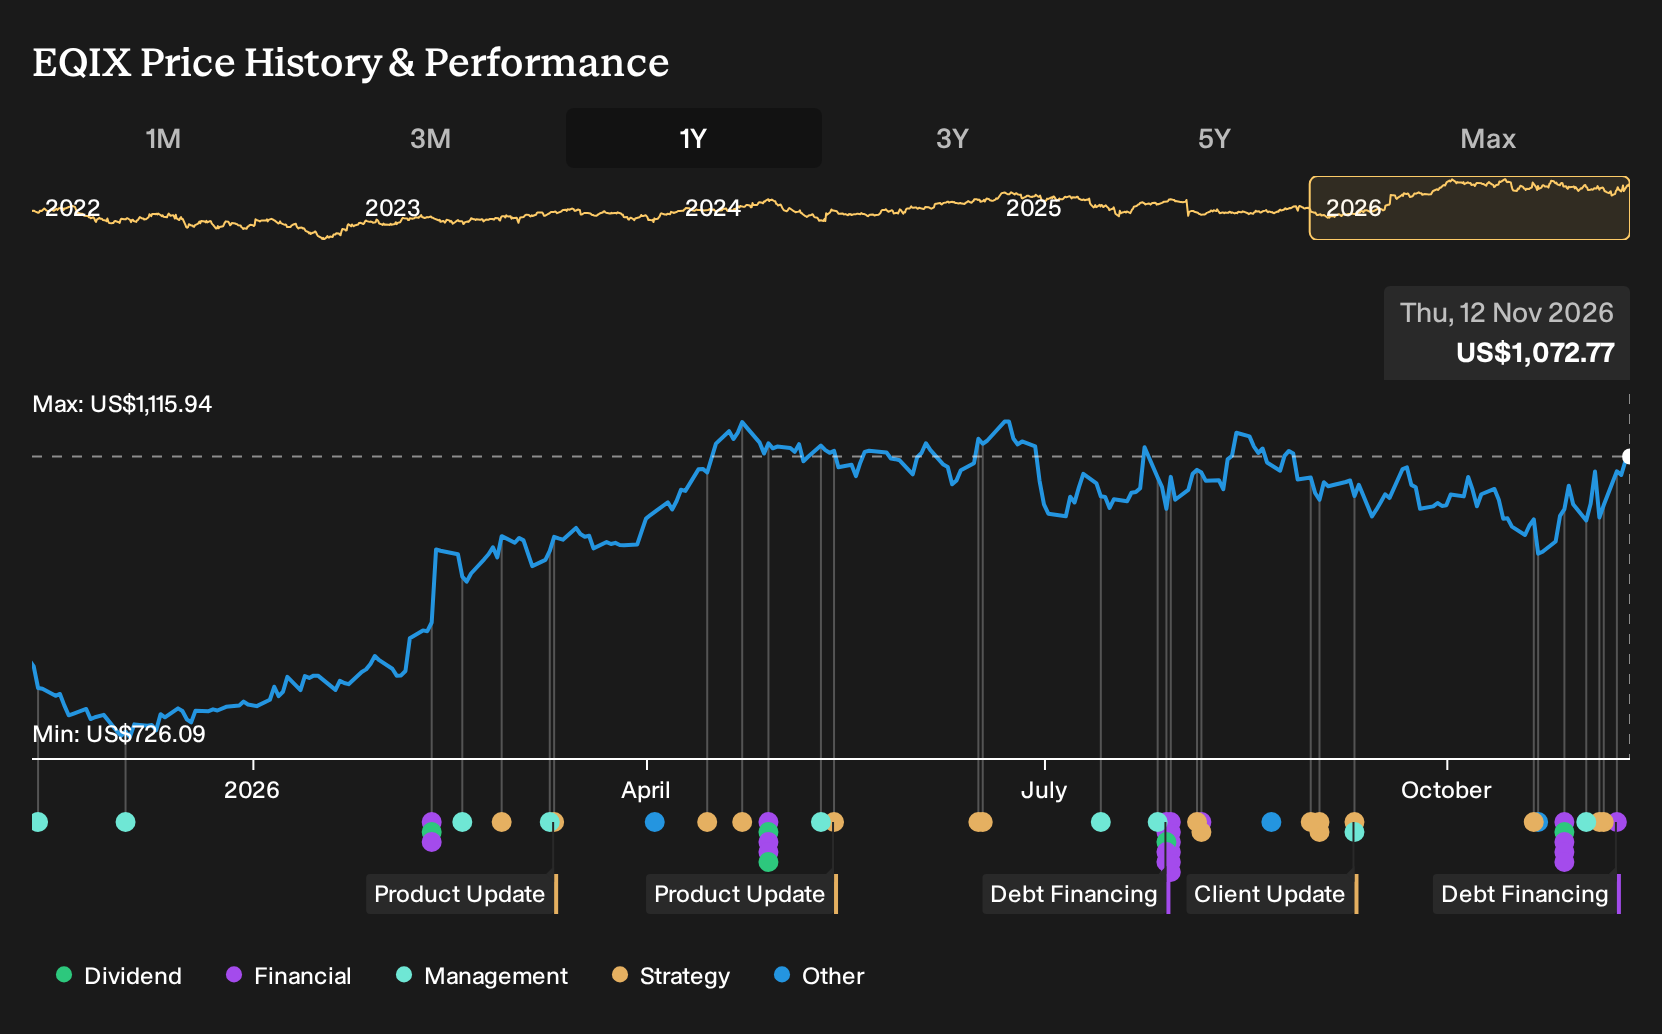
- Equinix issued €2.5b of euro-denominated senior green notes and recently brought its SG6 AI-ready data center in Singapore online, adding capacity for AI and high-performance computing while tying new funding to eligible sustainability projects.
- The mix of green financing, power-hungry AI infrastructure like SG6, and resource-efficiency targets such as 100% renewable coverage may help Equinix balance growth ambitions with rising scrutiny on data center energy use and emissions.
- This section now examines how Equinix's large green bond financing shapes the investment narrative around AI-ready capacity and sustainability.
Scan hand-picked peers funding AI-ready infrastructure with green capital by reviewing the 53 AI infrastructure stocks that echo Equinix's push into high-density, energy-efficient data centers.
Equinix Investment Narrative Recap
To own Equinix, you need to trust that AI and cloud demand keep filling its colocation focused, interconnection heavy data centers while management delivers large projects like SG6 on time and within power constraints. According to LunaRodas, an investor in the Simply Wall St Community, the big swing factor is whether that proprietary demand framework keeps translating into booked cabinets and disciplined pricing.
The fresh €2.5b green notes and euro senior bonds tighten the spotlight on leverage and cash generation, since debt is not well covered by operating cash flow. In the near term, the key upside trigger is successful delivery and pre selling of new capacity, while the main risk is execution under a heavier funding load.
The recent €2.5b of green senior notes look most relevant here because they sit directly on top of LunaRodas’ focus on capacity delivery and balance sheet strength. The financing lengthens maturities out to 2038 and fixes interest costs in the 4.15% to 5.45% range, with hedges trimming effective rates on the longest tranches.
For you, the trade off is simple to frame. More long dated euros give Equinix room to support AI ready builds such as SG6 and future green projects, yet the firm already relies entirely on higher risk borrowing rather than customer deposits. The catalyst is execution on the 3 gigawatts plus pipeline and 700 megawatts under development, while the risk is that cash flows lag these larger interest and capex commitments.
LunaRodas assigns a fair value of $938.23 to Equinix by arguing that record cabinet deliveries, quantified 12% new deal pricing, lower 1.7% churn, and the atNorth capacity uplift collectively support the long term guidance framework that management reaffirmed indirectly through execution rather than through new headline numbers.
Uncover why Equinix's fair value indicates a 13% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
You now have three fair value views from the Simply Wall St Community, stretching from about $1,233 to $1,691 per share for Equinix. That is a wide span for one ticker. When you also consider fresh green financing and new AI ready capacity, it becomes clear that opinions can differ sharply, so explore the full range of community forecasts.
Explore 2 other Equinix fair value estimates, including one that suggests it could be worth just $1,233.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Equinix research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Equinix. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equinix's overall financial health at a glance.
Looking for more investment ideas beyond Equinix?
Once you have a handle on Equinix, it can help to compare it with other opportunities that line up with your risk tolerance, income needs, and balance sheet preferences using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan the 32 high quality undervalued stocks that currently clear both financial strength and pricing filters.
- If steady income is a priority, review the 6 dividend fortresses that focus on companies offering higher yields with an emphasis on durability.
- If capital preservation matters most, filter for resilience using the 29 resilient stocks with low risk scores that screen for businesses with lower risk scores and sturdier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com