
What Hongkong Land Holders Bought Into
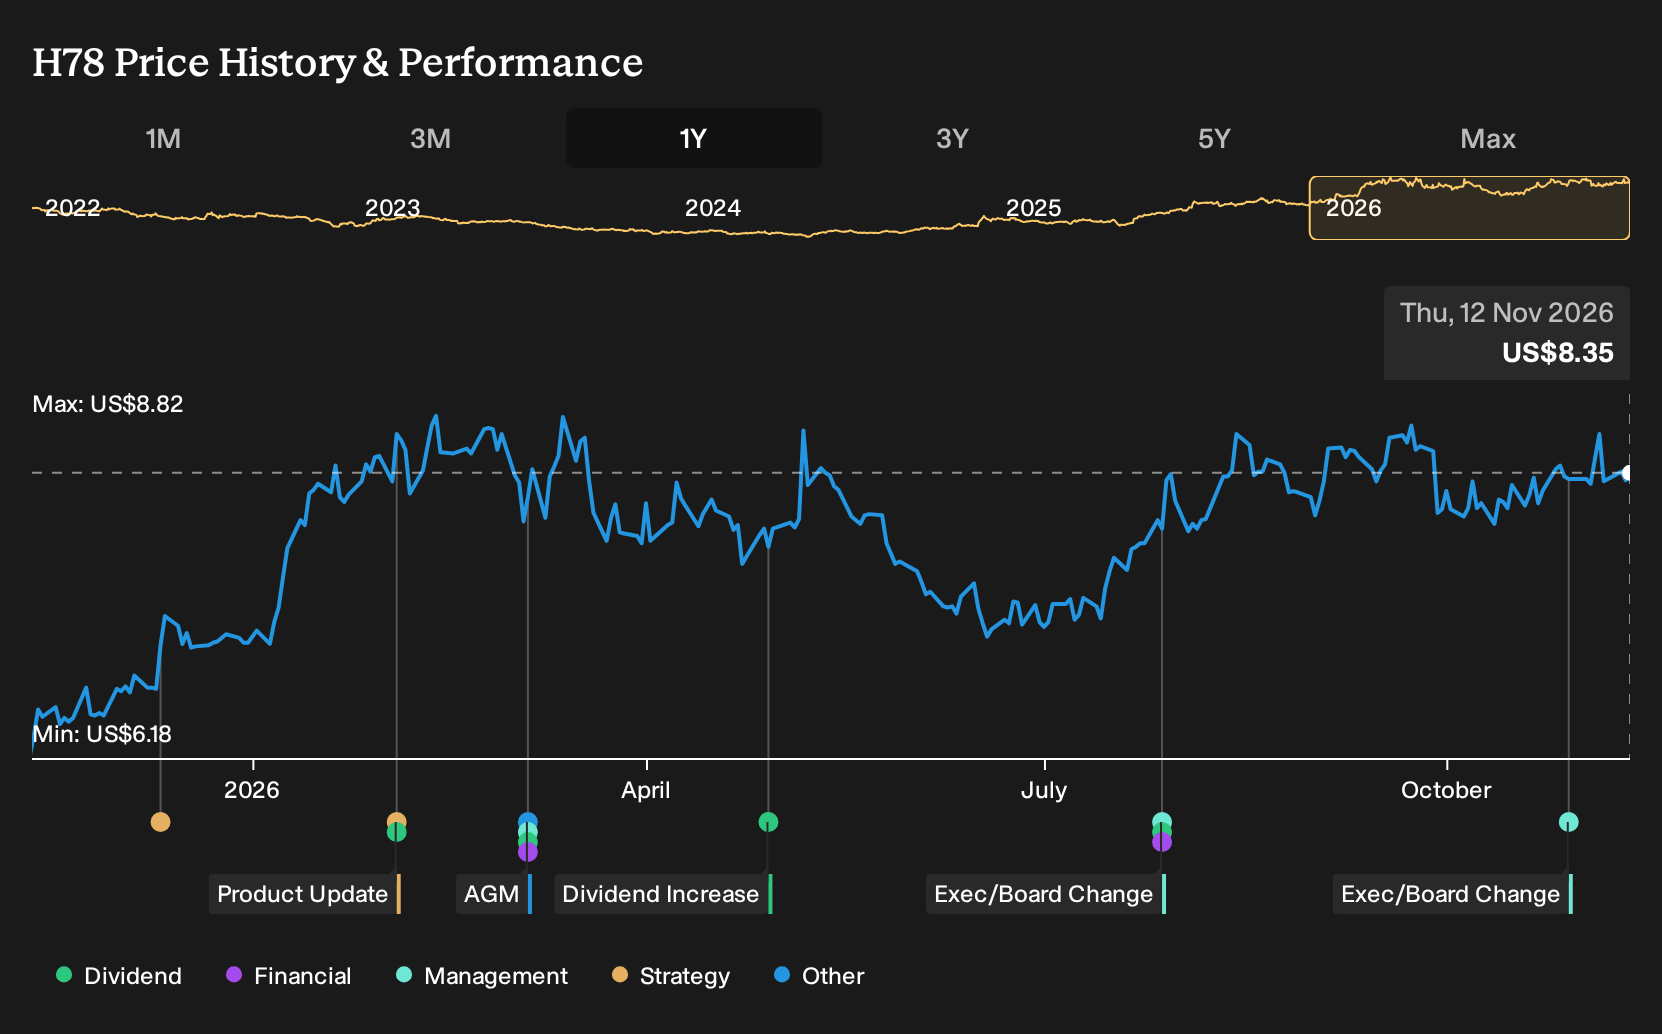
If you only skimmed Hongkong Land headlines about weaker office demand and China exposure, a flat or even painful year might have seemed more likely than a strong payoff. Investors who held Hongkong Land over the past year are up 34.7%, including dividends. If you were weighing the bullish talk of marquee asset repositioning against worries about remote work and capital recycling risk back in November 2025, what exactly did the record suggest you were being paid to believe?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Hongkong Land harder to judge, start where the gap is still open and scan 193 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Hongkong Land
The shares cost US$6.18 at the start of the period, and investors in Hongkong Land had two very different stories to price in.
The bullish narrative saw fair value at US$6.86, or 11% above the start price, based on revenue growth of 2.5% and a profit margin assumption of 47.9% within three years.
The bearish view put fair value at US$4.88, or 21% below the start price, and was based on a revenue decline of 12.3% a year despite a projected 73.0% margin and a 12.6x future P/E.
What The Evidence Did To The Hongkong Land Argument
Hongkong Land leaned into buybacks in mid 2026, cancelling repurchased shares and trimming the share count, which supported the bullish focus on capital management. The H1 2026 report told a different story on operations. Revenue moved from US$751.2m in H1 2025 to US$632.7m, while net income excluding extra items shifted from US$220.9m to US$1,259.5m, so the evidence cut both ways.
The main assumption under the spotlight was that capital recycling and repositioning would support profitability. For a different stock, you would track whether revenue and net income move in the same direction as management actions like buybacks or asset sales before relying on that narrative.
What Hongkong Land's Price Seems To Be Paying For Now
Hongkong Land now trades at US$8.35, after a 34.7% gain over the past year, and this Narrative’s Fair Value sits above that quote according to the analyst consensus Narrative on Simply Wall St.
The current argument leans on fee income, recycled capital and cost cuts. A buyer today would need to judge whether redeploying those proceeds into prime assets and fund platforms can really stick.
"Ongoing capital recycling of US$3.7b of net proceeds by mid 2026, with management aiming to exceed the minimum US$4b target ahead of 2027, gives Hongkong Land Holdings more room to redeploy into higher yielding prime assets and fee platforms, which can support future net asset value per share and earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 17% below our estimate - sells excavator tiltrotators into markets where most operators have never adopted them.
- Company 2 - 27% below our estimate - shifts its probiotic mix toward adult and oral health products with stronger demand.
- Company 3 - 44% below our estimate - builds AI driven hiring and matching tools that automate more of recruitment spending.
Three companies from the same screener. Open the full list of 200 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com