
Integra LifeSciences Holdings (IART) Stock Dropped, What Is Behind The Fresh Attention?
Why recent legal scrutiny matters for Integra LifeSciences Holdings
Pomerantz LLP has begun investigating Integra LifeSciences Holdings (IART) after the company cut full-year 2026 revenue guidance, following severe flooding at its Cincinnati facility and a confirmed third-quarter revenue shortfall.
Integra LifeSciences Holdings now trades at US$14.35, with the share price down 21.76% over the past 90 days yet still showing a 19.48% year to date share price return. However, the 5 year total shareholder return has declined 78.88%, pointing to fading longer term momentum despite more recent strength.
Scan beyond Integra LifeSciences Holdings and stress test your thesis against 29 resilient stocks with low risk scores, which have historically weathered operational shocks with more resilient business profiles.
Bulls point to Integra LifeSciences Holdings’ improved net income and recent share price recovery, while bears focus on legal scrutiny and long term value erosion. Which side does the current valuation actually support next?
Most Popular Narrative: 38% Undervalued
The bullish analyst Narrative on Simply Wall St marks Integra LifeSciences Holdings with a fair value of $23.00 against the latest $14.35 close, framing the stock as materially undervalued while hinging that view on successful execution of its recovery plan.
Analysts already factor in Integra LifeSciences Holdings finishing its Compliance Master Plan and stabilising operations. However, the reported reduction in remediation spending, several quarters without major supply upsets and ongoing transformation savings point to further room for structural cost efficiency gains that could still lift gross margin and earnings quality beyond what current models assume.
See why 2 investors see Integra LifeSciences Holdings as 38% undervalued.
That narrative applies an 11.65% discount rate and assumes Integra LifeSciences Holdings can turn today’s slim 0.8% profit margin into an 8.5% margin over time. It also bakes in revenue of about $1.8b and earnings of $152.5m by 2029, which is a significant step up from the current $1,656.8m revenue base and $13.0m net income.
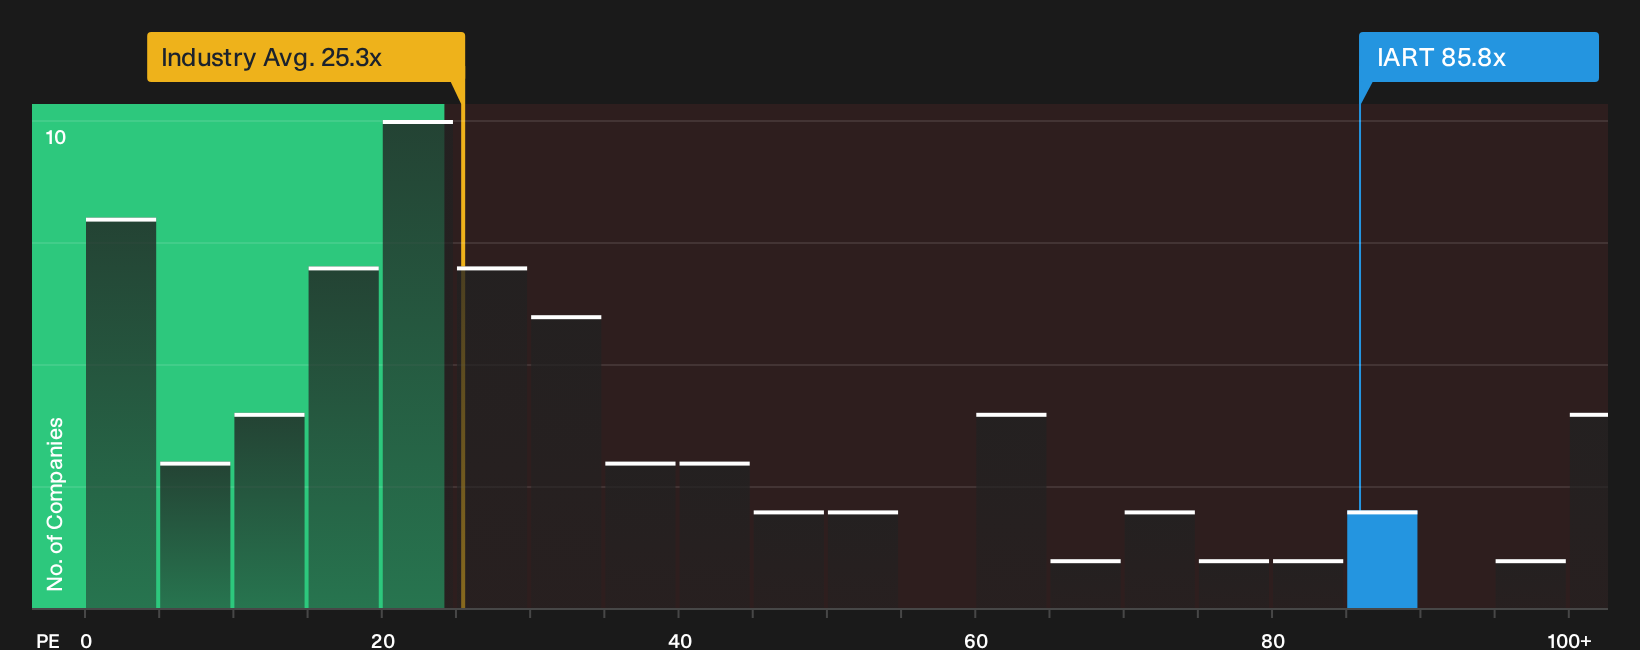
At today’s $14.35 share price, the implied 37.6% discount to that $23.00 fair value sits alongside a mixed quality profile. The stock screens as trading about 22.9% below the SWS DCF future cash flow value of $18.61, yet carries a very high 85.8x P/E relative to both its fair P/E of 55.2x and the broader US Medical Equipment sector at 26x, reflecting that current earnings are still low and shaped by one off items.
For context, Integra LifeSciences Holdings earns the bulk of its $1,219.8m Specialty Surgery and $437.0m Tissue Reconstruction revenue in the US, while carrying a market cap of about $1.1b and value score of 2 out of 6. Forecasts point to earnings growth of 62.9% per year with revenue growth closer to 2.2% per year, which leaves most of the valuation case resting on margin repair and better cash conversion rather than rapid top line expansion.
Result: Fair Value of $23.00 (UNDERVALUED)
Still, the Integra LifeSciences Holdings story can crack if flood related disruption drags on or if high leverage keeps tightening the screws on cash flow.
Find out about the key risks to this Integra LifeSciences Holdings narrative.
Another View: What Integra LifeSciences Holdings’ P/E Is Telling You
While the SWS DCF model points to Integra LifeSciences Holdings trading at a discount to its estimated future cash flow value of $18.61, the current 85.8x P/E paints a different picture. That ratio is well above the 55.2x fair ratio, the 34.2x peer average and the 26x wider US Medical Equipment group, which suggests meaningful valuation risk if earnings do not ramp as forecasts imply. Which signal do you trust more?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed headlines around Integra LifeSciences Holdings can easily sway sentiment in either direction. Consider reviewing the underlying data and weighing both sides of the thesis by checking 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Integra LifeSciences Holdings?
If Integra LifeSciences Holdings has your attention, do not stop there. Broaden your watchlist now so you are not chasing the next opportunity after it has already moved.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (23 results) that pair financial strength with fundamentals you can scrutinize in detail.
- Hunt for mispriced quality by reviewing the 20 high quality undiscovered gems that quietly combine solid cash generation with under-the-radar potential.
- Aim for income-focused resilience by checking the 6 dividend fortresses built around higher-yield payers with a focus on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com