
Safety Insurance Group (SAFT) Tests Its Valuation As New Dividend Meets Earnings Pressure
Safety Insurance Group (SAFT) just paired fresh quarterly results with a new cash dividend, approving a US$0.92 per share payout for the fourth quarter of 2026 alongside its latest earnings release.
At a share price of US$104.34, Safety Insurance Group has moved only modestly in recent weeks. However, a 37.82% year to date share price return combined with a 42.25% 1 year total shareholder return suggests earlier momentum has cooled but remains firmly positive in a longer view.
Spot opportunities beyond Safety Insurance Group by scanning a curated 6 dividend fortresses that, like SAFT, combines income potential with established business models.Safety Insurance Group now trades well above its recent levels, yet the intrinsic model points to a steep premium over fair value. Is the market being too optimistic, or are investors rightly cautious about the earnings trend?
Preferred P/E of 21.6x: Is It Justified For Safety Insurance Group?
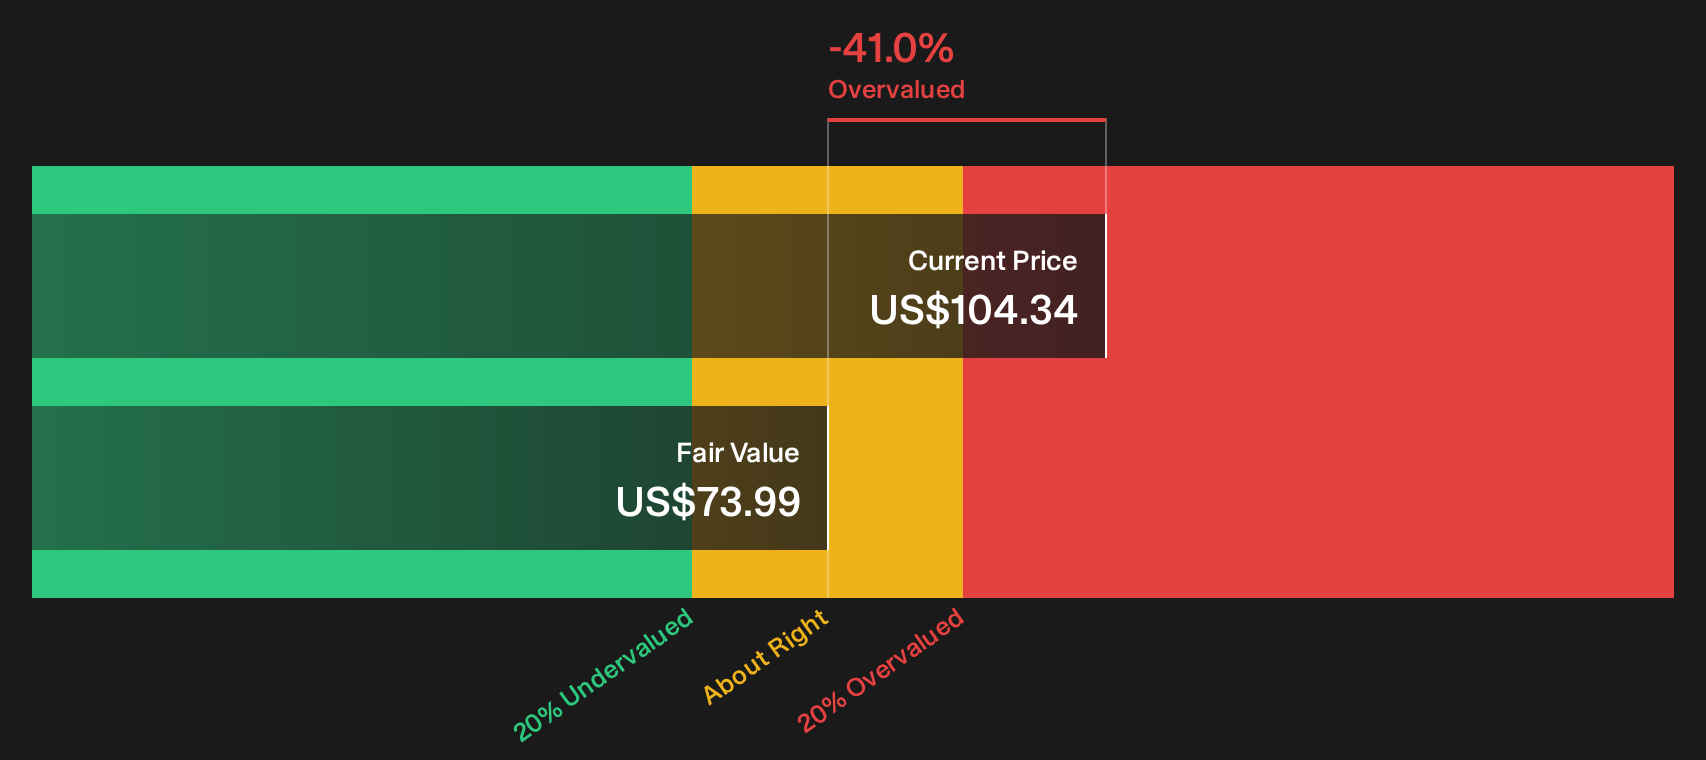
Safety Insurance Group trades at a P/E of 21.6x, above our SWS DCF model fair value indication of $73.99 per share and above the last close of $104.34. This points to investors paying a premium relative to both earnings history and intrinsic cash flow estimates.
The P/E ratio compares the share price to earnings per share and acts as a shorthand for how much investors are willing to pay for each dollar of profit. For an insurer like Safety Insurance Group, which reported net income of $70.895m on revenue of $1,287.453m and carries a 5.5% net margin, this metric helps you see how the market is weighing its profitability profile against alternatives.
On that score, the stock screens as expensive. The P/E of 21.6x is higher than the peer group average of 20.4x, and it is also well above the broader US Insurance industry average of 11.5x. Given that earnings have declined by 19% over the past year and by 5.2% per year over the past five years, the premium suggests the market is assigning a relatively rich price to a business that has faced pressure on profitability, even though the earnings quality is flagged as high and the dividend yield of 3.53% has been described as reliable.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 21.6x (OVERVALUED)
Still, the Safety Insurance Group story could shift quickly if competitive pressure in its core Massachusetts auto and home markets squeezes pricing power, or if underwriting results weaken and call the current earnings multiple into question.
Find out about the key risks to this Safety Insurance Group narrative.
Another View on Safety Insurance Group’s Value
The SWS DCF model paints a different picture for Safety Insurance Group. On that approach, the estimated future cash flow value sits at $73.99 per share, which is well below the current $104.34 price and indicates the stock appears overvalued on a cash flow basis.
That kind of gap does not have to close quickly. However, it raises a practical question for investors. Is the current premium a fair price to pay for a business with high quality earnings but pressured profit trends, or is patience on the sidelines the better approach until price and cash flow value align more closely?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Safety Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about whether the current optimism around Safety Insurance Group is warranted? Act quickly, pull apart the same numbers, and stress test both the upside case and the risk worries captured in the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Safety Insurance Group?
If Safety Insurance Group has sharpened your focus on quality, do not stop here. Broader opportunities often emerge where pricing, balance sheets, and income streams intersect cleanly.
Use the Simply Wall Street Screener to uncover a wider set of ideas that fit your goals before the market fully prices them in.
- Target resilience by scanning a curated 29 resilient stocks with low risk scores that filters for companies with sturdier profiles when you want potential returns with controlled downside.
- Hunt for value by reviewing a 20 high quality undiscovered gems that highlights under-the-radar businesses with strong fundamentals that many investors may be overlooking.
- Put capital to work in income-focused ideas through a list of solid balance sheet and fundamentals (23 results) that helps you find payout potential supported by healthier financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com