
Is Sonida Senior Living (SNDA) Undervalued After Revenue Jumped But Losses Widened?
What the latest Sonida Senior Living earnings reveal
Sonida Senior Living (SNDA) just released third quarter 2026 results that combined much higher reported revenue with a wider loss, a mix that can reshape how investors think about the stock.
The business recorded third quarter revenue of US$210.2 million compared with US$98.04 million a year earlier. The net loss widened to US$34.3 million, and basic loss per share from continuing operations moved to US$0.72 from US$1.56.
Recent trading has been softer, with the share price down 7.9% over the past month and 15.3% over 90 days. However, Sonida Senior Living still shows a positive year to date share price return and a very large 3 year total shareholder return of about 26 times that shorter term move. This suggests cooling momentum after a strong multi year run as investors weigh faster top line progress against ongoing losses.
Scan how Sonida Senior Living compares with other healthcare operators facing similar revenue growth and loss pressures by reviewing the hand picked list of solid balance sheet and fundamentals (23 results).
Sonida Senior Living has shifted from a powerful multi year run to a choppier few months as revenue expands while losses remain heavy. Has most of the share price progress already played out, or does valuation still leave meaningful upside on the table?
Most Popular Narrative: 30.2% Undervalued
On the analyst consensus Narrative on Simply Wall St, Sonida Senior Living carries a fair value of about $47.50 versus the recent $33.16 close. This frames the stock as materially discounted and puts the focus on what needs to go right to close that gap.
The acquisition of CNL Healthcare Properties adds 54 SHOP assets and broadens the real estate base in growth markets, which can support higher occupancy density and contribute to revenue and NOI growth as the combined platform matures.
See why 1 investors see Sonida Senior Living as 30% undervalued.
Result: Fair Value of $47.50 (UNDERVALUED)
Still, the Sonida Senior Living story depends on successful integration of the US$1.8b CHP deal and on stable labor costs, and missteps on either front could quickly weaken that undervaluation case.
Find out about the key risks to this Sonida Senior Living narrative.
Another view on Sonida Senior Living’s valuation
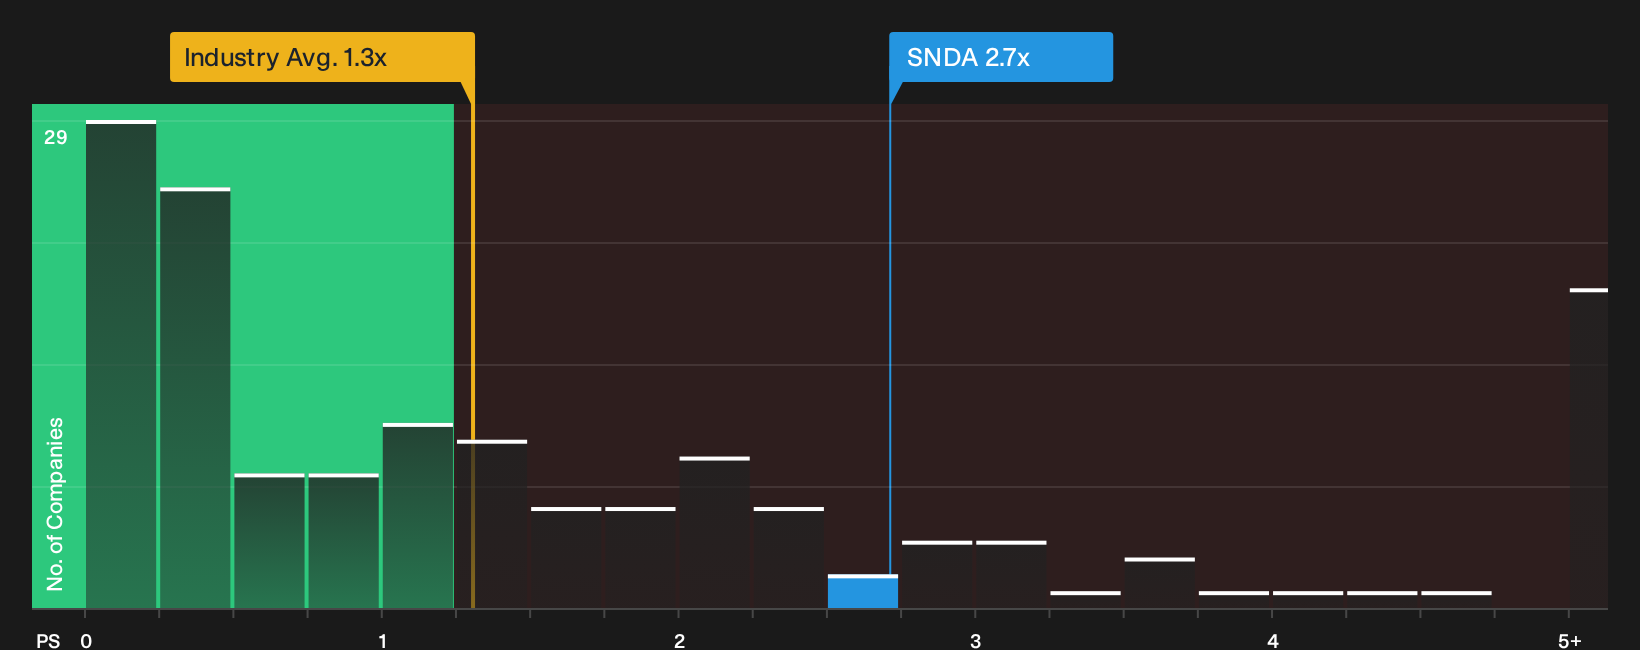
The analyst narrative points to Sonida Senior Living as about 30% below fair value at $47.50, yet the price tag looks very different when using sales multiples. On a P/S of 2.7x, the stock trades well above both the US Healthcare industry at 1.3x and its own fair ratio of 1.6x. That gap points to meaningful valuation risk if sentiment cools or revenue expectations reset, so how comfortable are you paying a premium today for a business that is still loss making?
Our valuation work based on this pricing yardstick goes further in that direction. SNDA is described as expensive against peers and its fair ratio, and our DCF framework currently suggests the market price of $33.16 sits well above an estimated future cash flow value of $2.06. Put side by side, these approaches ask you to weigh a rich current multiple against an optimistic long term story. Which lens do you trust more when sizing any position? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Sonida Senior Living is clearly divided. Move quickly, review the full data set and decide where you stand on its potential and risks. To see both the upside arguments and the red flags investors are focused on, start with the 1 key reward and 3 important warning signs.
Looking for more Sonida Senior Living style investment ideas?
Sonida Senior Living will not be the only stock on your radar, so widen the opportunity set and let data driven filters surface candidates you might otherwise miss.
- Zero in on potential mispricings by scanning a focused set of companies that combine quality markers with discounted valuations through the 32 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses that pair manageable leverage with robust fundamentals using the 29 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities by running a screen that highlights financially sound but less crowded ideas via the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com