
Workiva (WK) Could Be 24% Undervalued Following Strong Earnings And 2026 Guidance
Why Workiva’s Latest Earnings Matter To Investors
Workiva (WK) just delivered third quarter results that showed higher revenue and net income compared with a year earlier, paired with fresh guidance for both the upcoming quarter and the full 2026 financial year.
Management now projects fourth quarter revenue between US$275 million and US$278 million, with a GAAP operating margin between 7.1% and 7.7%. For the full year 2026, Workiva expects total revenue of US$1.041b to US$1.044b, and a GAAP operating margin range of 6.2% to 6.3%, alongside projected GAAP net income per diluted share of US$1.31 to US$1.34.
Despite Workiva guiding to higher revenue and profitability, the share price tells a different story in the short term, with a 7 day share price return down 19.9% and the year to date share price return down 17.4% on the back of a US$68.51 close. Over a longer stretch, the total shareholder return has declined 24.9% over one year and just over 50% over five years, which suggests recent earnings progress and guidance have not yet shifted investors’ view of the company’s risk and reward balance.
Scan how Workiva’s earnings reset compares with other software players that currently screen as 20 high quality undiscovered gems in this corner of the market.
Workiva just posted healthier earnings, yet the share price has retreated sharply, leaving investors asking the same thing: Is the meaningful upside still in front of the stock or already in the rear view mirror as valuation resets?
Most Popular Narrative: 24% Undervalued
Workiva’s last close at $68.51 sits well below the analyst consensus Narrative fair value of $89.80, pointing to a sizeable valuation gap. The analyst consensus Narrative on Simply Wall St ties that upside to specific execution levers around AI, cross sell and partner scale.
The main thing that has to go right is that Workiva successfully scales AI enabled, agentic-first workflows across regulatory, financial reporting, GRC and sustainability solutions while maintaining the high gross and net retention it currently reports.
The current valuation implies Workiva is fairly valued on the assumption that durable subscription growth, rising operating and free cash flow margins and expanding multi-solution and international cohorts are already reflected in the share price.
See why 8 investors see Workiva as 24% undervalued.
Result: Fair Value of $89.80 (UNDERVALUED)
Still, the Workiva story has pressure points, including regulatory uncertainty around European sustainability rules and the risk that rapid, partner-led deployments may dilute customer satisfaction.
Find out about the key risks to this Workiva narrative.
Another View On Workiva’s Valuation
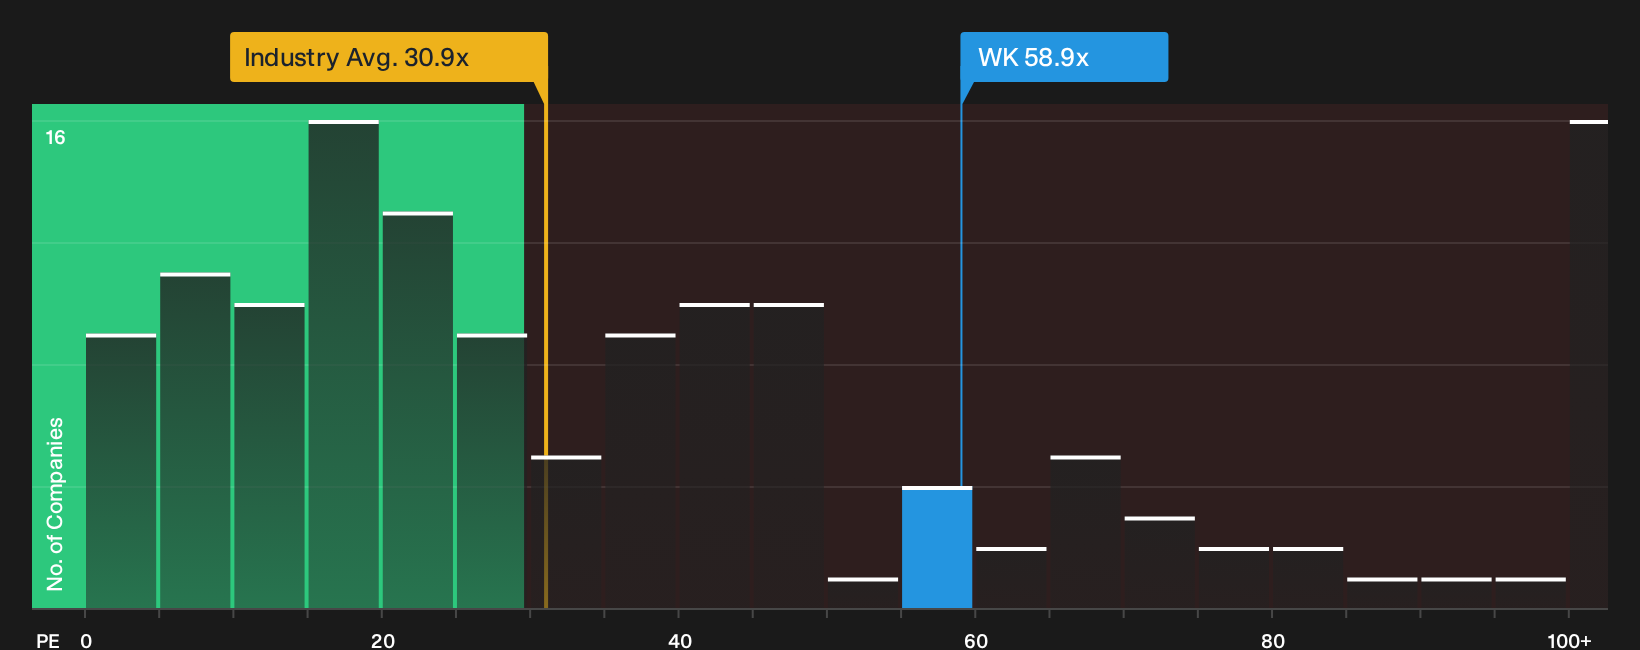
On the flip side of that fair value of $89.80, Workiva screens as expensive on traditional earnings metrics. The stock trades on a P/E of 58.9x compared with 31.2x for the wider US Software group and a 39.6x fair ratio estimate for the business itself. That gap raises a simple question for you as an investor: Is this a quality premium or valuation risk waiting to compress?
For a closer look at how this earnings multiple stacks up against both peers and that fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Workiva’s story so far. If you want to move fast and establish your own stance, start by weighing its 4 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Workiva?
If Workiva has you rethinking your watchlist, do not stop here. Fresh ideas often come from scanning outside your usual comfort zone.
- Target steady compounding and filter for quality at a sensible price with a curated set of 32 high quality undervalued stocks that already clear tough fundamental checks.
- Reduce portfolio stress by focusing on resilient businesses through a 29 resilient stocks with low risk scores that highlights stocks with stronger risk profiles.
- Strengthen your core holdings by hunting for companies with robust finances using a list of solid balance sheet and fundamentals (23 results) that rewards healthy balance sheets and sound fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com