
What Investors Got Wrong Before ABB's Rally
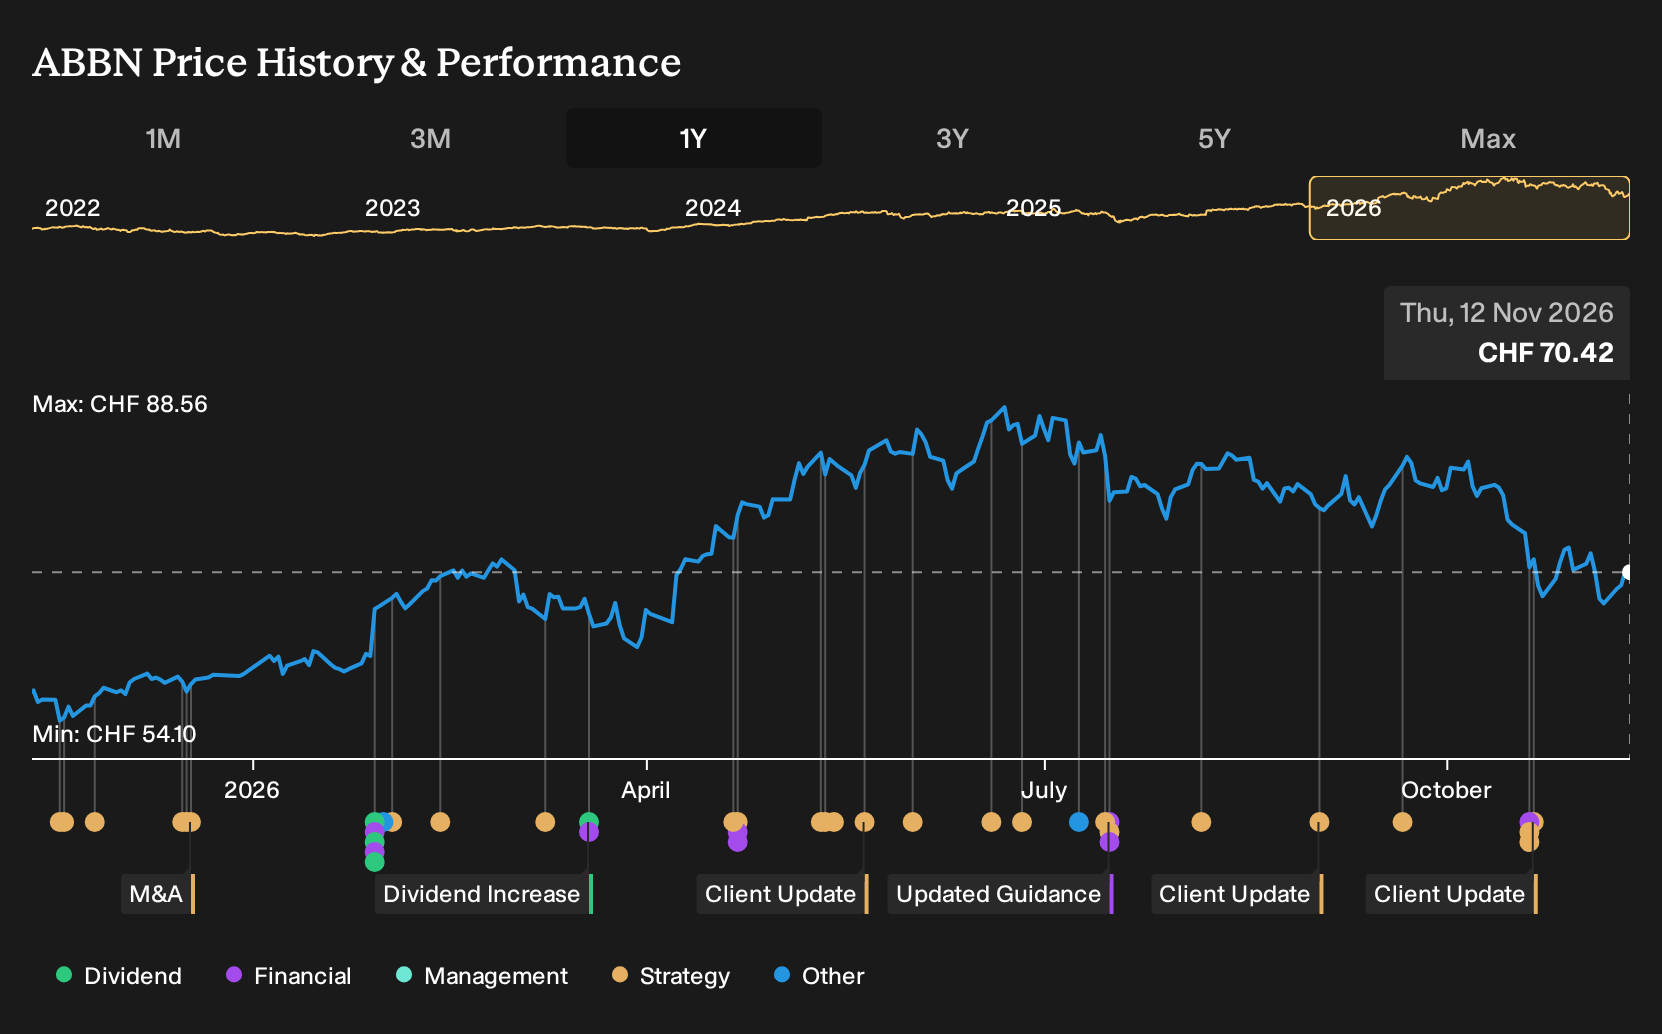
ABB just agreed to buy UK flow control specialist Rotork in a US$5.6b cash deal, a concrete move to bulk up its automation footprint rather than just talk about electrification and AI data centers. For ABB shareholders, the return over the past year was 27.2%, including dividends. If you were weighing a purchase a year ago, what had to sound credible about acquisitions, robotics divestment plans, and grid demand before any of this news hit the tape?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond ABB. See which of 43 power grid technology and infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing On ABB
The shares cost CHF57.42 at the start of the period, so any thesis on ABB had to explain why that upfront price made sense in the context of electrification, automation, and portfolio reshaping.
The bullish narrative saw fair value at CHF62.63 and leaned on ABB being a preferred partner for grid resilience and data center buildout. Analysts in that camp assumed revenue could rise 7.5% a year and margins could reach 14.8% by around 2028.
The more cautious view put fair value at CHF51.11 and focused on pressures from weaker end markets and Chinese competition, with assumptions built around 5.4% annual revenue growth, a 14.0% margin, and a future P/E of 24.1x.
What The Evidence Did To The ABB Argument
ABB signing the US$5.6b Rotork deal, plus a planned robotics sale and a joint venture with Mitsubishi Electric in Asia Pacific, lined up closely with the bullish script on portfolio reshaping and grid focused automation. Reported Q3 2026 figures showed revenue and net income above Q3 2025, while net margin moved from 13.8% to 12.6%, so profitability progress looked less clear. Overall, the evidence cut both ways.
The lesson is simple. When a story leans on margin expansion as much as ABB's did, do not just track sales and headlines. Keep checking whether net income grows faster than revenue and whether the reported margin actually moves toward the narrative.
What ABB's Recent Run Already Prices In
ABB now trades at CHF70.42, with this Narrative's Fair Value sitting below that level according to Tokyo, a Simply Wall St Community investor who wrote the Narrative. The argument leans on ABB as an "operating system of industry" spanning electrification, motion, automation and software.
A buyer today is effectively betting ABB keeps turning that architecture into durable earnings at this higher price. The open question is how Tokyo's concern about future P/E normalizing and more modest margins interacts with what you are now paying for that story.
"Across these decades, ABB’s recurring strategic question has been: Which businesses strengthen its ability to make customers’ industrial assets operate better together? The answer has changed with technology, markets and management. Some acquisitions expanded that capability, some disposals released capital or reduced complexity, others corrected earlier mistakes."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
ABB And The Hardware Behind It
ABB focuses on electrification, motors and automation. Your grid and factory need something else too.
Those electrified systems still depend on hardware that stores and moves data quickly. Without that, automation software and control gear cannot run at full tilt.
Another specialist concentrates on memory and storage for data centers, mobile devices, vehicles and embedded electronics. Its products help AI servers, consumer gadgets and industrial systems keep data flowing.
As ABB leans into power systems and automation, this other player leans into data hardware. The unresolved angle is how both roles adapt as AI infrastructure spreads across plants, clouds and cars.
One Narrative has put that dependency into a written case. → See the AI infrastructure company one Narrative values 57% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com