
VeriSign (VRSN), What Is Behind The Fresh Attention?
VeriSign (VRSN) has finally secured ICANN approval to roll out the long awaited .web domain, resolving a decade long dispute and putting concrete launch dates on the calendar.
For context, VeriSign shares trade at US$312.48, with the 90 day share price return of 9.94% and the year to date share price gain of 29.91% pointing to building momentum as investors factor in the announced .web rollout. Over a longer horizon the 3 year total shareholder return of 51.99%, compared with the 1 year total shareholder return of 25.79%, suggests gains have been solid but not one way, with sentiment now being refreshed by concrete expansion of its domain portfolio.
Scan for other potential beneficiaries of internet infrastructure demand by checking out our curated list of 20 high quality undiscovered gems that could be flying under most investors' radar alongside VeriSign.
After a near 30% year to date run and fresh excitement around .web, the puzzle is whether VeriSign still offers meaningful upside or if most of the easy gains now sit in the rear view mirror.
Most Popular Narrative: 7% Undervalued
On the Simply Wall St analyst consensus Narrative, VeriSign screens as undervalued, with a fair value of $336.40 against the last close at $312.48. That view rests on a detailed set of growth and cash flow assumptions discounted at 9.44%.
The main thing that has to go right is that VeriSign continues to convert AI driven domain demand, new TLDs such as .web, and security focused products into durable growth while managing contract renewal and regulatory risks around its .com and .net registries.
See why 34 investors see VeriSign as 7% undervalued.
Result: Fair Value of $336.40 (UNDERVALUED)
Still, the VeriSign narrative could be knocked off course if .com or .net contract renewals tighten materially, or if AI driven domain demand cools faster than analysts expect.
Find out about the key risks to this VeriSign narrative.
Another View: What Multiples Say About VeriSign
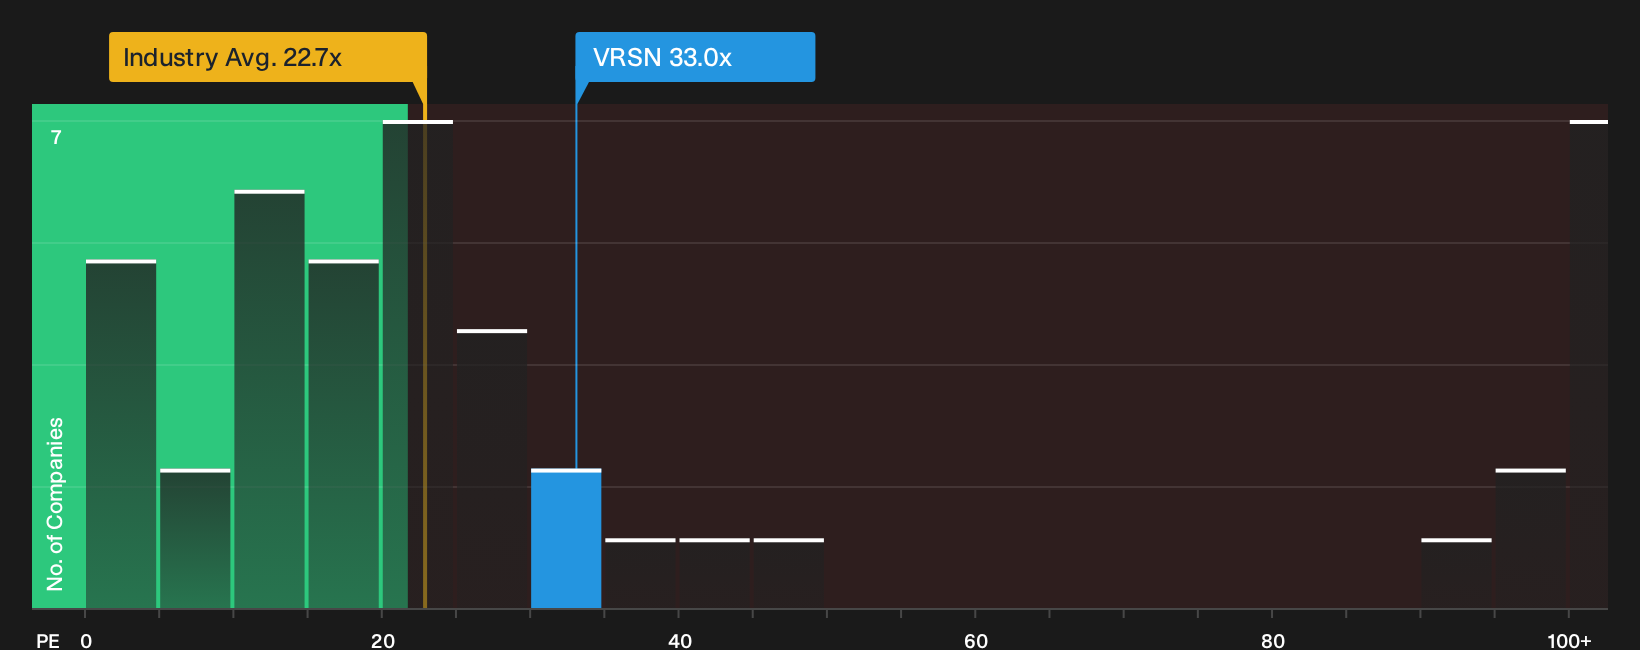
VeriSign may screen as 7% undervalued on the consensus fair value of $336.40, yet the P/E of 33x looks full next to a fair ratio of 27.5x, the US IT sector at 23.4x and a peer average of 45x. Is this a quality premium or just valuation risk creeping in?
For a closer look at how that P/E gap could close over time, including where the fair ratio might matter most, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sitting with all of this, the VeriSign story carries both enthusiasm and caution, so move fast on your own homework and weigh the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond VeriSign?
If VeriSign has sharpened your focus on quality opportunities, do not stop here. Broaden your watchlist and give yourself more ways to be right.
- Target resilient businesses that aim to protect capital through cycles by scanning our 29 resilient stocks with low risk scores for potential lower volatility candidates.
- Hunt for potential value opportunities by running through the 32 high quality undervalued stocks that combine solid fundamentals with what may be appealing price tags.
- Prioritise balance sheet strength by using the list of solid balance sheet and fundamentals (23 results) so you are not relying only on optimism when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com