
Amprius Technologies (AMPX) Stock Trades At A Premium To Sales
Amprius Technologies has delivered a very strong 3 year share price gain while more recently the stock has been choppy, which puts a fresh spotlight on whether its current price is supported by the level of sales the business is generating today. With mixed short term returns and active customer demand in high performance battery markets, the key issue now is how much revenue investors are effectively paying for.
- Over the past 3 years the share price has risen about 112.5%, so anyone looking at the stock now needs to consider whether that move still matches what the company is producing in sales.
- Recent record revenue and a new high energy battery product, alongside a sizeable U.S. defense contract, can shape how quickly sales may scale relative to the cost base and capital needed to support that growth path.
- Your read on Amprius Technologies is one view; the desks covering it have another. See what analysts think Amprius Technologies's shares could be worth.
The issue now is whether Amprius Technologies' current valuation is justified by its sales when you line the share price up against the revenue it is bringing in.
If you are weighing Amprius Technologies against other high performance battery plays, it can help to line it up beside 53 AI infrastructure stocks.
Has Amprius Technologies Run Too Far on Sales?
P/S fits Amprius Technologies best right now because revenue is the clearest financial anchor for a business that is still loss making on earnings and heavily investing in capacity.
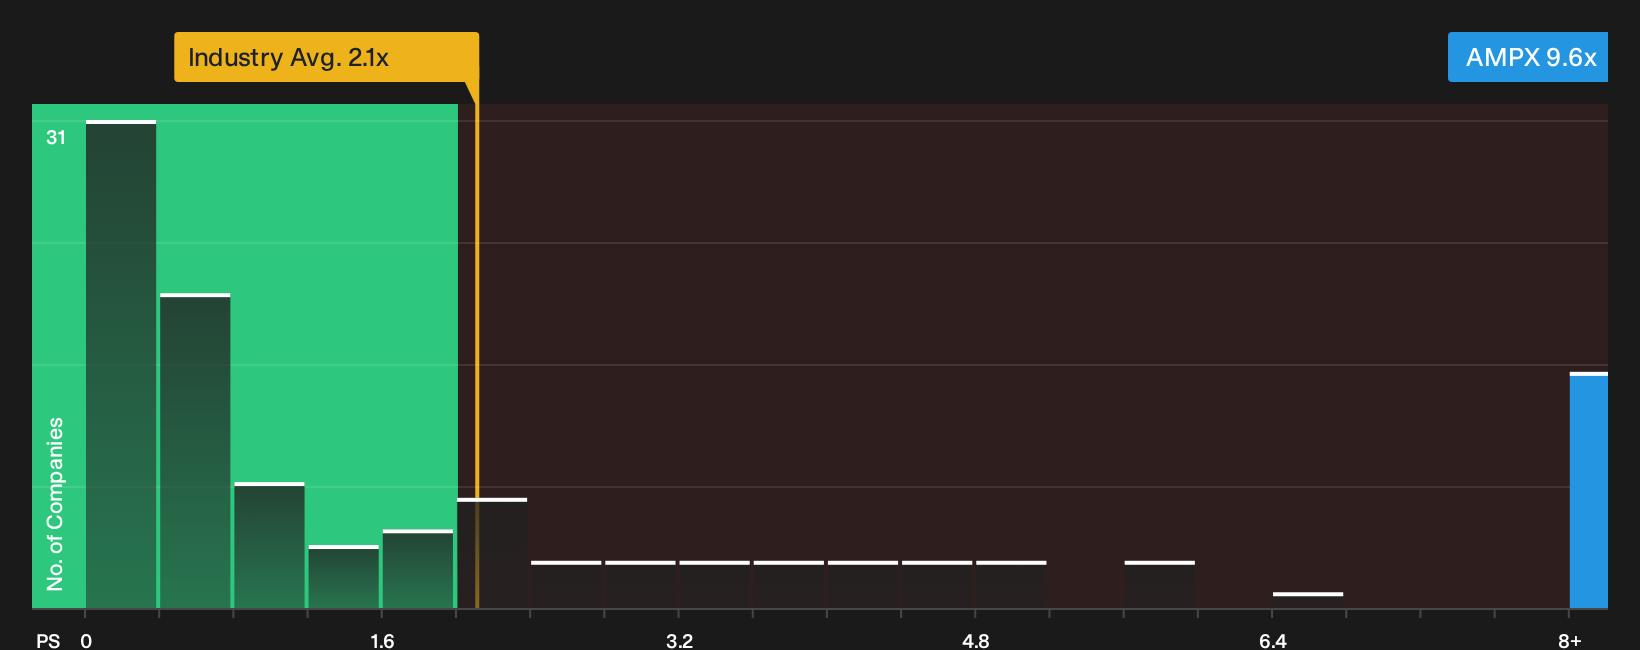
The stock trades on a P/S of 9.6x, which is far above the Electrical industry average of 2.1x and also higher than the 11.7x peer group reference for similar high performance battery players. On a tailored fair value framework that factors in Amprius Technologies' growth profile, margins, size and risk, the current P/S sits above the level implied by those fundamentals, which points to the shares looking overvalued on this metric. Despite record Q3 2026 sales and upgraded full year revenue guidance lifting expectations, the multiple still asks you to pay a premium relative to both sector norms and closer peers. Explore the numbers behind Amprius Technologies's P/S valuation.
The Amprius Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Amprius Technologies valuation puzzle leaves off, spelling out exactly what kind of future growth, profitability and earnings profile would need to occur for the stock to be worth materially more or less than today. Rather than relying on a single multiple or model output, each scenario lays out the assumptions behind its view of fair value so you can compare those with Amprius Technologies' actual results as they are reported.
One of the top narratives on Amprius Technologies: 62% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Amprius Technologies delivers NDAA-compliant capacity and contract manufacturing scale on the timelines implied by its IBAS-funded U.S. buildout and multi-year orders from drone and electric motorcycle customers…"
Discover why this Narrative puts Amprius Technologies at 62% undervalued.
Amprius Technologies: why price alone is not the full story
There is one more piece that matters for Amprius Technologies, which is the set of potential pressure points our checks have picked up and that investors may want to weigh for themselves. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com