
Valvoline (VVV) Faces Margin Pressure, Is It Still 19% Undervalued?
Valvoline (VVV) heads into its November 19 earnings report with expectations for lower year over year profit alongside higher revenue for the September 2026 quarter, a combination that can sharpen investor focus on margins.
Recent trading has turned choppy for Valvoline, with the share price slipping 2.98% in the last session and 2.79% over the past week, even after a strong 30 day share price return of 15.45% and a year to date share price gain of 20.64%. This points to momentum still building despite a more modest 9.53% total shareholder return over the past year and flat total shareholder returns over three and five years.
Scan the wider auto services space for stocks showing similar earnings pressure but stronger recent momentum through a curated list of 32 high quality undervalued stocks.
Valvoline shares have sprinted ahead while analyst targets and intrinsic estimates still point higher, leaving a clear gap between recent enthusiasm and pinned down fair value. How much of that spread still looks justified on the numbers?
Most Popular Narrative: 19% Undervalued
On the analyst consensus Narrative on Simply Wall St, Valvoline screens as undervalued, with a fair value of $43.25 against a last close of $34.83. This puts the focus squarely on whether the growth and margin story holds up to the discount rate of 9.33% that underpins that estimate.
The consistent growth in same-store sales driven by both increased transactions and higher ticket sizes from premium service offerings remains in place, and recent guidance for system-wide same-store sales of 7.5% to 8% reinforces the view that Valvoline can keep translating resilient maintenance demand into revenue and earnings growth over time.
Aggressive store expansion through both company-owned and franchise models continues, with the network at 2,456 locations and franchise partners committing over US$1b to roughly 650 additional units. This supports a long runway for higher system-wide sales and EBITDA as Valvoline works toward its target of at least 3,500 stores.
See why 2 investors see Valvoline as 19% undervalued.
Result: Fair Value of $43.25 (UNDERVALUED)
Still, the bullish Valvoline narrative bumps up against clear pressure points, including higher finished lubricant costs and softer traffic if miles driven and new customer acquisition weaken further.
Find out about the key risks to this Valvoline narrative.
Another View: Valvoline Looks Expensive On Earnings
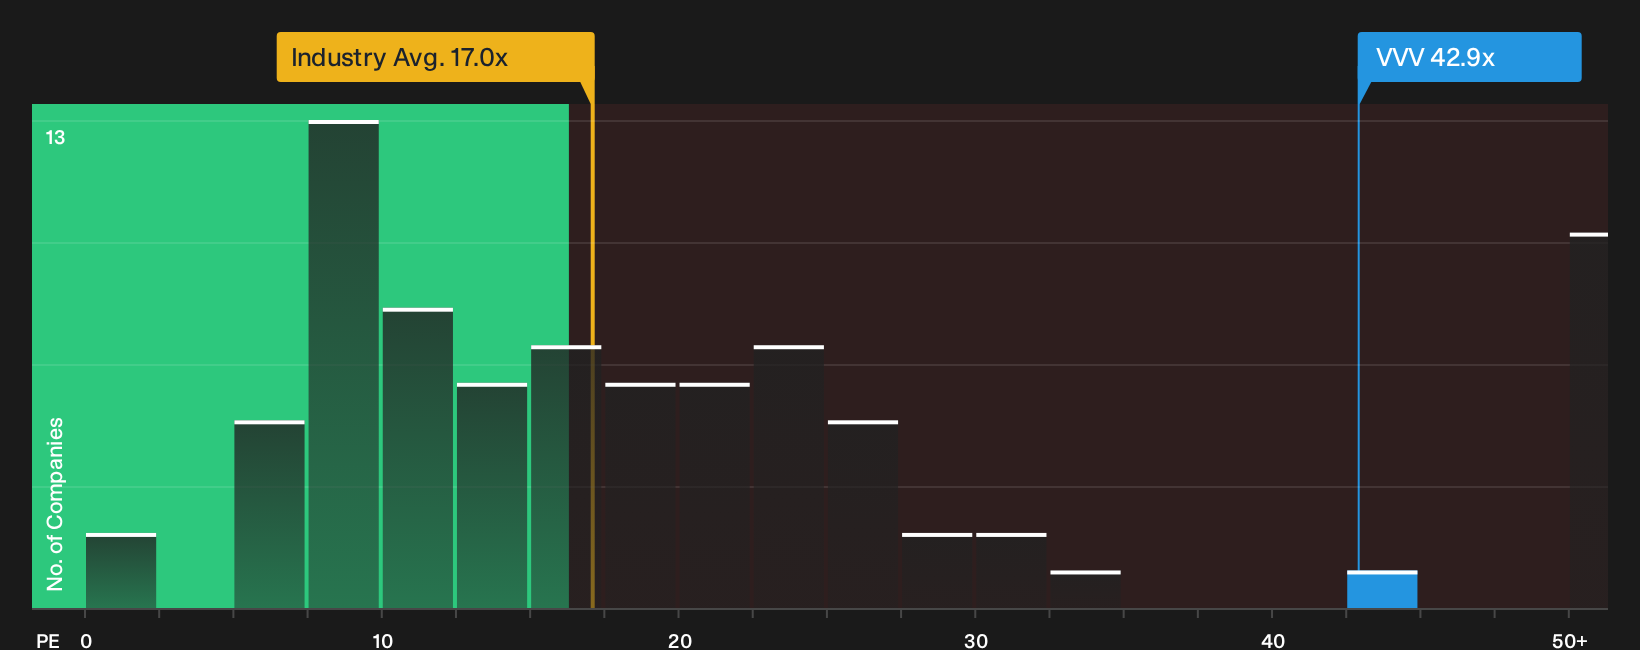
On a simple P/E lens, Valvoline tells a very different story. The shares trade at 42.9x earnings, compared with a fair ratio of 28.6x, a US Specialty Retail industry average of 17.3x, and a peer group closer to 8x. That gap points to valuation risk if expectations ease.
For investors who prefer to anchor on earnings multiples rather than cash flow models, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Valvoline can either feel exciting or unsettling, so move quickly, review the full picture, and weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Valvoline?
If Valvoline has sharpened your thinking, now is the time to widen the lens and hunt for other opportunities that fit your style and risk comfort.
- Target durable growth paired with attractive pricing by scanning a curated set of potential bargains through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies screened for higher yields and sturdier payouts using the 6 dividend fortresses.
- Prioritize resilience and capital protection by focusing on businesses filtered for sturdier finances in the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com