
Datadog (DDOG) Could Be 32% Undervalued As Strong Earnings Reset The Valuation Debate
Why Datadog’s latest earnings matter for the stock
Datadog (DDOG) just delivered third quarter results that paired higher year over year sales and net income with tighter full year revenue guidance, giving investors fresh numbers to reassess the recent share price pullback.
The business reported US$1.20b in third quarter revenue and US$118.32 million in net profit, alongside updated expectations that full year 2026 sales will land in a range of US$4.515b to US$4.525b.
Datadog’s latest guidance lands just after a sharp reset in sentiment, with the 30-day share price return down 34.9% even as the year to date share price return is up 37.89%. The 3-year total shareholder return of 69.04% still signals a materially positive longer track record.
The earnings beat, tighter full year revenue outlook and news of its largest customer trimming usage now sit alongside a 5.65% 7-day share price return and a recent full year total shareholder return that slipped 0.81%. This hints that investors are recalibrating risk more than writing off Datadog’s longer term potential.
Spot oversold setups like Datadog’s and scan a hand picked group of resilient tech names on our 32 high quality undervalued stocks.After a one month slide of roughly 35% against solid reported results, Datadog now presents a sharper question for investors: Does this reset finally tilt the risk reward toward buyers, or not yet?
Most Popular Narrative: 32% Undervalued
At a last close of $184.46 versus an analyst consensus fair value of about $271.71, the most followed view on Simply Wall St frames Datadog as materially undervalued based on forecast cash flows and earnings power. That analyst consensus Narrative on Simply Wall St anchors its case in how the platform connects AI heavy workloads, broader product adoption and long term profitability.
Expanding AI workloads, with over 750 AI customers including all 10 of the top AI leaders and growing use cases such as GPU monitoring, Agent Observability, AI Guard and Bits AI, can support higher observability and security spend per customer and feed Datadog revenue growth over time.
See why 181 investors see Datadog as 32% undervalued.
Result: Fair Value of $271.71 (UNDERVALUED)
Still, the Datadog story can change quickly if large customers keep trimming usage or if softer revenue guidance continues to reset what investors are willing to pay.
Find out about the key risks to this Datadog narrative.
Another View: Datadog’s Rich Sales Multiple
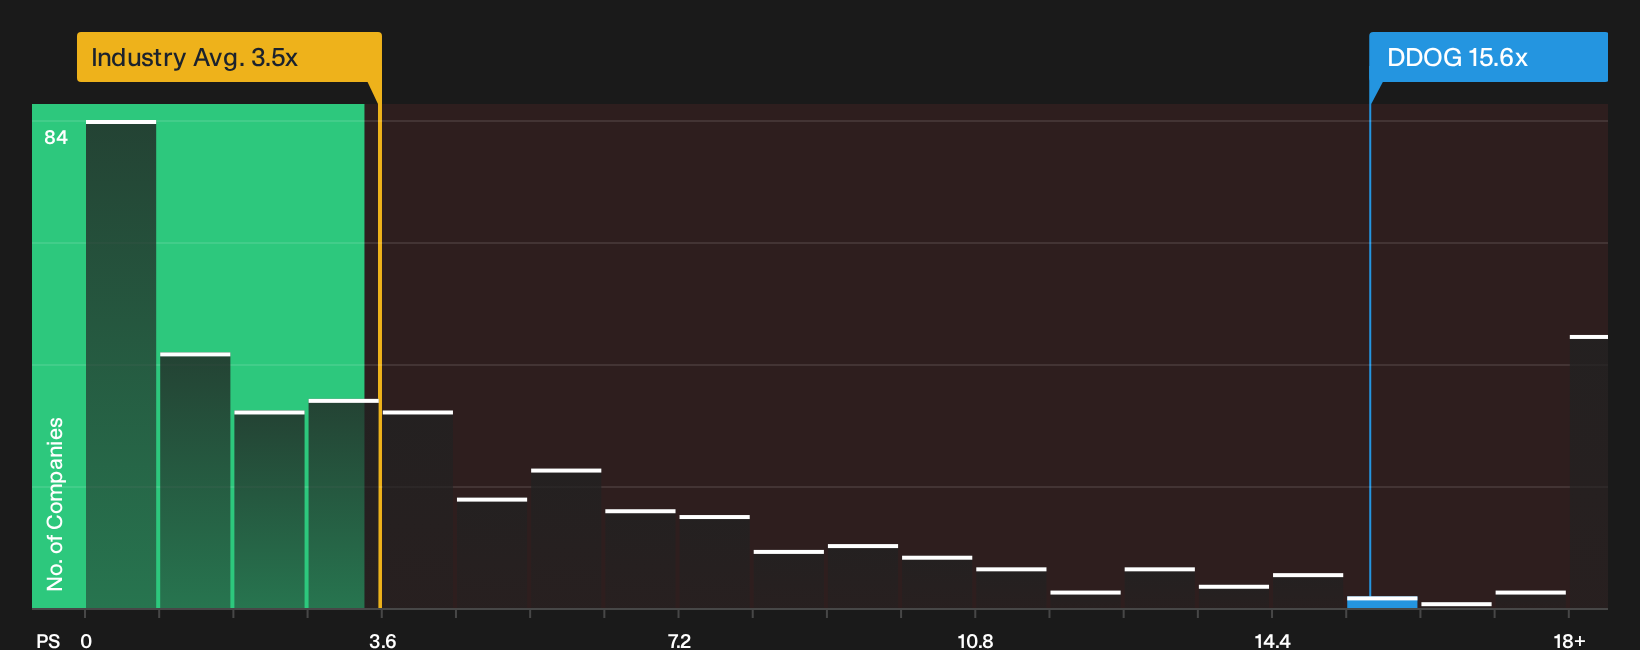
There is a catch. While our DCF model flags Datadog as trading about 44.6% below an estimate of future cash flow value, the P/S ratio tells a very different story, with the stock at 15.6x sales versus a US Software sector closer to 3.5x.
The fair ratio for Datadog is 13.4x sales. This implies the current price already runs ahead of where the market could eventually settle if enthusiasm cools. That stretch can work as upside torque if growth stays strong, or it can magnify downside if sentiment fades more quickly than fundamentals justify. Which risk matters more to you right now.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on Datadog leave you torn, move fast and test the story against the numbers yourself so sentiment does not decide for you. Start by weighing both sides of the investment case through 4 key rewards and 1 important warning sign
Looking for more Datadog style investment ideas?
If Datadog’s reset has sharpened your focus, do not stop here. The next move often comes from a stock you have not reviewed yet.
- Target reliable compounding by scanning a 6 dividend fortresses that aims to balance meaningful income with balance sheet strength.
- Hunt for value by reviewing a 20 high quality undiscovered gems that combines solid fundamentals with lower market attention.
- Dial down portfolio stress by focusing on a 29 resilient stocks with low risk scores built around resilience and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com