
Dynatrace (DT) Partners With CrowdStrike And Lifts Guidance, Is It Still Below Fair Value?
Why Dynatrace Stock Is Back In Focus After Fresh Guidance And A New Partnership
Dynatrace (DT) just landed on investor radars after a cluster of November updates. The company raised full year 2027 revenue guidance, reported new quarterly results, expanded a buyback plan, and unveiled a CrowdStrike partnership.
The recent guidance hike, CrowdStrike alliance and fresh US$1b repurchase authorization arrived after a sharp reset, with a 30-day share price return down 30.36% even as the year-to-date share price gain sits at 6.02% and the 1-year total shareholder return declined 4.02%. This points to momentum that has cooled but could be reassessed in light of these updates.
Scan beyond Dynatrace and spot other software players reacting to similar security and observability themes with our hand picked 41 profitable AI stocks that aren't just burning cash.
The swing in Dynatrace shares after higher guidance, fresh results and a new buyback pits business progress against a cooler mood. To figure out which side is louder, pricing and valuation need a closer look next.
Most Popular Narrative: 27% Undervalued
Dynatrace last closed at $44.90, while the analyst consensus Narrative on Simply Wall St anchors fair value at about $61.26 using an 8.73% discount rate. That gap frames a view that the observability specialist could be priced below modeled future cash flows and earnings power.
The move toward value based, consumption driven pricing continues with Dynatrace Platform Subscription contracts showing platform consumption growth well over 20% compared with ARR growth of about 16% to 17%, and a heavy DPS renewal mix expected in the second half of fiscal 2027, which can translate sustained consumption into higher net retention, ARR expansion, and operating leverage over time.
See why 54 investors see Dynatrace as 27% undervalued.
Result: Fair Value of $61.26 (UNDERVALUED)
Still, if Q4 renewals disappoint or the Arize deal delivers lower ARR than expected while pressuring margins, the bullish Dynatrace narrative could unravel quickly.
Find out about the key risks to this Dynatrace narrative.
Another View: Dynatrace Looks Expensive On Earnings
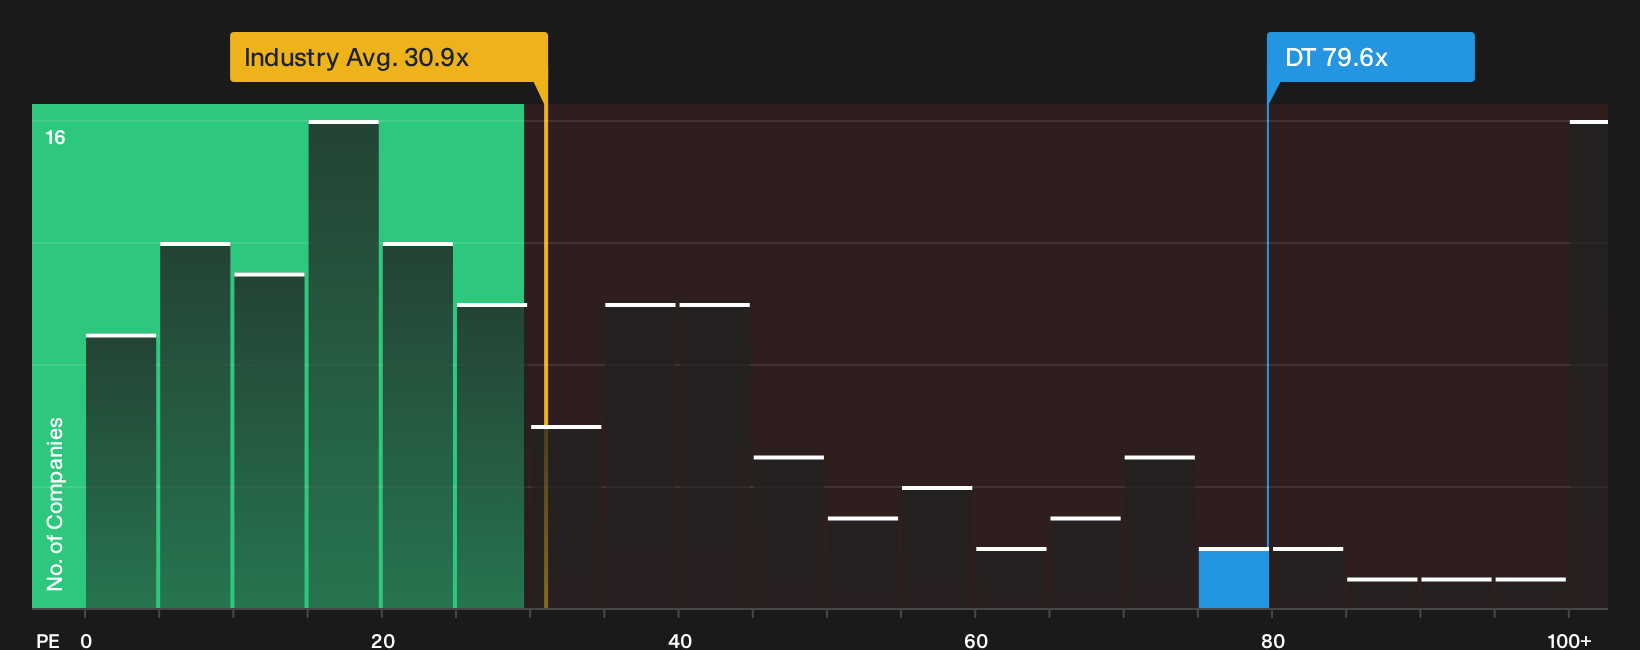
That DCF based fair value paints Dynatrace as undervalued. The picture changes when you look at what investors pay for each dollar of earnings. DT trades on a P/E of 79.6x versus 30.9x for the wider US Software group and a 45.6x fair ratio estimate.
This gap suggests meaningful valuation risk if sentiment cools toward the richer multiple, especially with profit margins currently at 7.4%. The question for anyone watching DT is simple: Does the earnings profile justify that premium, or is the DCF view doing too much of the heavy lifting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Dynatrace so far. Use the data to move quickly, examine both sides of the debate, and weigh the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Dynatrace?
If Dynatrace has your attention, do not stop at one ticker. Use the Simply Wall St screener and line up alternatives before the next move leaves you behind.
- Target dependable compounding by reviewing companies with resilient balance sheets and steady fundamentals through this list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality and see which businesses screen as potential bargains in our curated 32 high quality undervalued stocks.
- Build a cash flow focused watchlist by scanning income ideas in the hand picked 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com