
Top Japanese Growth Stocks For November 2026
AI related goods drove most of global trade growth in early 2026, with East Asia at the center of that surge. Japanese growth stories tied to this wave are attracting attention, because demand for computing power and related services has become a global supply chain priority rather than a niche theme. This article walks through three high conviction Japanese growth stocks from our screener that aim to tap into that trend.
The three Japanese stocks below are only a sample, because the full High Growth High Conviction screen surfaced 27 more companies with equally compelling narratives across AI hardware, software and infrastructure that are not covered here.
If you want to identify and analyze the highest conviction opportunities in one place, head straight to the High Growth High Conviction screener.
Sansan (TSE:4443)
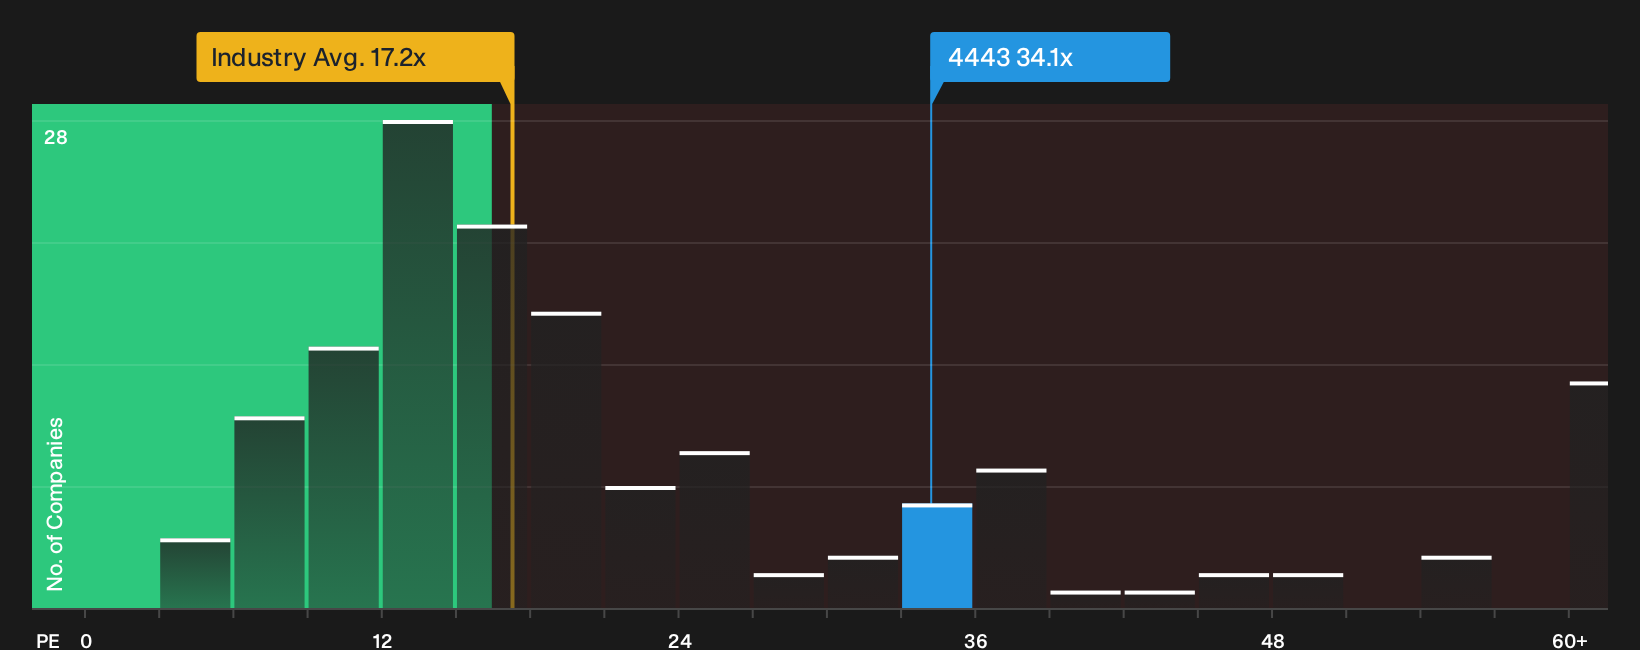
Sansan is a Tokyo based SaaS provider whose Sansan cloud platform helps enterprises turn business card and contact data into shared sales intelligence, which aligns neatly with a growth focused screener. The Sansan and Bill One segment brings in about ¥48.9 billion, far ahead of Eight on ¥7.1 billion, with a market value around ¥274 billion.
Sansan taps the High Growth High Conviction theme through a contact management suite that management and analysts expect to keep scaling. Earnings forecasts of 23.39% a year and a very large five year profit lift support that view, even as the P/E of 34.1x reflects a high valuation and margins depend on how one previously unseen pressure develops.
That pressure is exactly what investors should stress test through the 3 key rewards and 1 important warning sign to see how Sansan’s upside story could change fast.
Micronics Japan (TSE:6871)
Micronics Japan focuses on semiconductor test equipment such as probe cards, wafer probers and test sockets, which anchor its place in the High Growth High Conviction theme. The probe card line produces about ¥84.9 billion versus ¥1.4 billion from TE Business, and the firm is valued around ¥391.6 billion.
Micronics Japan is closely linked to the global chip build out through its probe cards and wafer test tools. Earnings are forecast to grow about 24.88% a year following recent profit growth of 89.4%, and the company currently trades at a P/E of around 20.9x. That combination of forecasts and premium pricing could change significantly if a single key assumption about demand shifts.
If that key demand swing is what you care about, go straight to the 2 key rewards and 1 important major warning sign to see what might be accelerating or stalling Micronics Japan in the period ahead.

freee K.K (TSE:4478)
freee K.K offers cloud accounting and back office software for small businesses and accountants in Japan, with its subscription based freee Accounting platform directly tied to the High Growth High Conviction theme. The business is valued at about ¥244.2b.
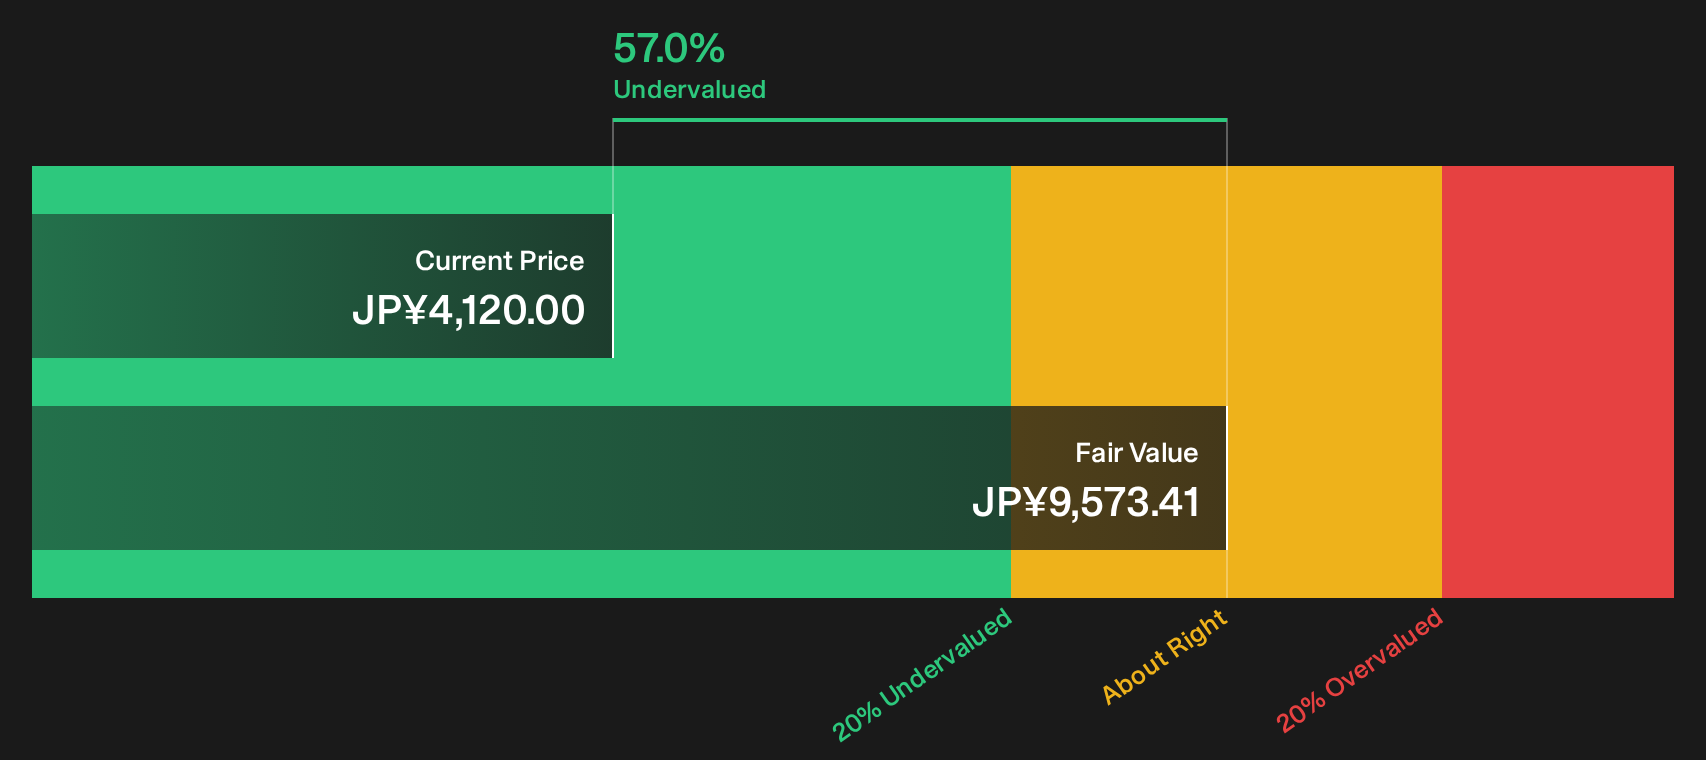
freee K.K pairs 36.2% historical earnings growth with a 39.78% forecast and a share price that some models place 57% below estimated cash flow value, which fits the screener’s hunt for high conviction growth. The real test comes if one unresolved pressure on profitability and capital efficiency shifts direction.
As that profitability pressure builds, unpack how it could reshape freee K.K’s growth path with the 3 key rewards and 1 important major warning sign before sentiment and pricing decouple.
Seeking Alternatives Before The Crowd?
Fresh ideas move fast. Breakout themes gain momentum, weaker stories get caught dropping, and under the radar for now quickly expires. Scan these curated lists and act now.
- Spot resilient cash generators before others notice by running your filters through the list of solid balance sheet and fundamentals (25 results) while it still reflects today’s strongest fundamentals.
- Ride income focused momentum by reviewing the hand picked 27 dividend fortresses that aim to keep portfolios supported when prices swing.
- Target fast moving automation tailwinds by checking the curated 85 robotics and automation stocks before this corner of the market is crowded.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com