
American International Group (AIG) Could Be 7% Below Fair Value As Earnings And Dividend Hold
American International Group (AIG) just combined a stronger third quarter earnings report with a fresh dividend affirmation, giving investors new numbers to weigh on revenue, profitability, and ongoing cash returns.
Recent price action has been modest, with a 30 day share price return of 6.34% and a 90 day gain of 7.74%, while the year to date share price is still down 2.02%. For investors looking beyond this latest quarter, American International Group has delivered a 1 year total shareholder return of 7.98% and a 5 year total shareholder return of 64.97%, which indicates that momentum has built more steadily over the longer run than in the very short term.
Compare AIG's earnings and dividend story with a curated 6 dividend fortresses that also combine income potential with established business models.The business appears stronger on paper after this quarter and the dividend confirmation, yet the share price has moved only modestly. Is American International Group actually cheap, or is that resilience already reflected in the price?
Most Popular Narrative: 6.6% Undervalued
On the Simply Wall St analyst consensus Narrative, American International Group is tagged with a fair value of $88.45 against a last close of $82.57. This frames a modest valuation gap and puts the current price in the context of detailed earnings and revenue forecasts.
The main thing that has to go right is that AIG continues to convert its cycle management, underwriting discipline, and expense ratio program into sustainably strong combined ratios across both General Insurance and Global Personal.
The current valuation implies that the market is still applying a discount to AIG shares, even though the company reports stronger underwriting income, capital returns through buybacks and dividends, and a more focused global P&C profile.
See why 33 investors see American International Group as 7% undervalued.
Result: Fair Value of $88.45 (UNDERVALUED)
Still, the AIG story can break if catastrophe losses stay elevated or if competition forces weaker pricing that drags on underwriting results and earnings resilience.
Find out about the key risks to this American International Group narrative.
Another View: Market Multiple Sends A Different Signal
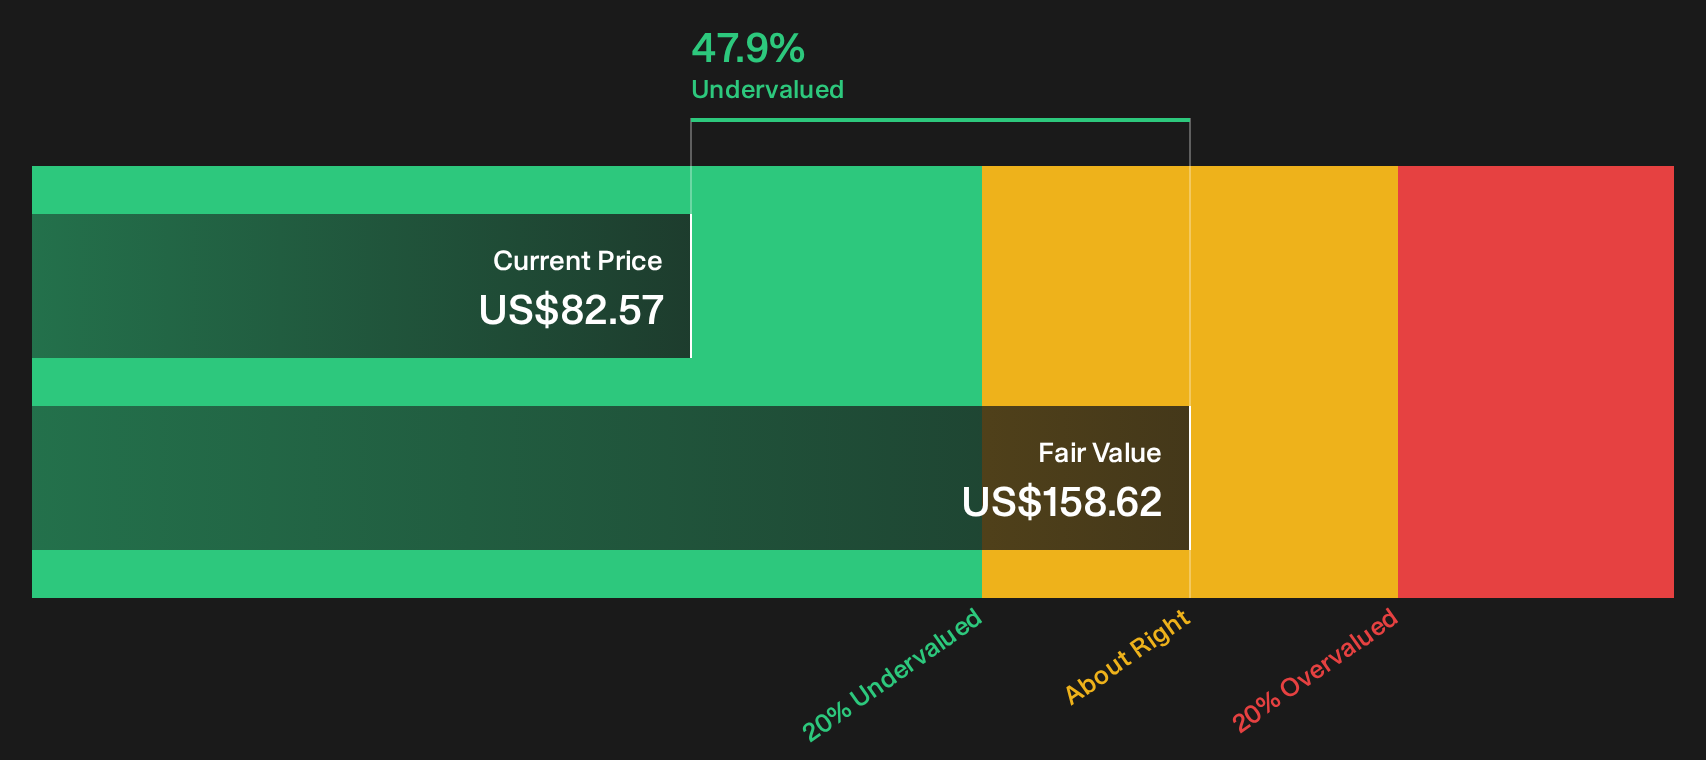
Our DCF model points to a future cash flow value of $158.62 per American International Group share, compared with the current price of $82.57, which screens as undervalued. Yet the stock trades on a 13x P/E, slightly above the fair ratio of 12.9x and above the US Insurance industry at 11.5x. Is the cash flow model too optimistic, or is the market multiple underestimating the long term story?
Investors who want to understand how that cash flow estimate is built can Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment in this piece leans cautiously optimistic, so move quickly from reading to testing the numbers yourself and stress test your own thesis with the full breakdown of 3 key rewards.
Looking for more investment ideas beyond American International Group?
If AIG has sharpened your focus, do not stop here. Fresh opportunities often emerge where valuation, quality, and resilience quietly line up before attention arrives.
- Spot potential value leaders early by scanning companies that pass strict quality and pricing filters with the 32 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle tough conditions.
- Get ahead of the crowd by tracking 20 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com