
PagerDuty (PD) Launches Paige As Fair Value Questions Follow
PagerDuty (PD) just rewired its core product story with the launch of Paige, an AI SRE agent, and the PD Reliability Platform, a unified incident, automation, and signal hub for operations teams.
The launch of Paige comes after a period in which PagerDuty’s share price has gained 32.1% over the past 90 days and 26.88% year to date. However, the 1-year total shareholder return is only 0.83% and the 5-year total shareholder return is down 61.07%, indicating that recent momentum has improved while long-term holders have faced a much tougher experience.
Scan how other AI focused operations platforms are priced and growing by reviewing the hand picked 41 profitable AI stocks that aren't just burning cash that pair automation stories with positive earnings profiles.
PagerDuty has just reshaped its product story while the share price has only recently started to move. Is the real upside still ahead, or has the stock already used most of its run?
Most Popular Narrative: 22% Overvalued
PagerDuty last closed at $15.72 while the analyst consensus Narrative on Simply Wall St points to a fair value of $12.86, which frames the recent rally against expectations for flat revenue and pressured profitability under a 9.36% discount rate.
• The current valuation implies the market is placing a high value on PagerDuty’s ability to convert essentially flat revenue and mid 20s non-GAAP operating margins into durable free cash flow growth, even though this narrative indicates that the stock is overvalued and skewed to the downside.
See why 19 investors see PagerDuty as 22% overvalued.
Result: Fair Value of $12.86 (OVERVALUED)
Still, two things could flip this PagerDuty story fast if they break right: a stronger Operations Cloud transition and more resilient retention than analysts currently plug in.
Find out about the key risks to this PagerDuty narrative.
Another View: SWS DCF Points To Undervaluation
The analyst consensus narrative pegs PagerDuty at a fair value of $12.86 and calls the stock overvalued. The SWS DCF model lands in a very different place. It estimates future cash flows at $24.04 per share, which is above the current $15.72 price and frames PagerDuty as undervalued instead. That split raises a basic question for you as an investor: Do you place more weight on the market’s alignment with analyst earnings forecasts, or on the cash flow path implied by the SWS DCF model?
For a closer look at how sensitive this view is to margin and growth assumptions, Look into how the SWS DCF model arrives at its fair value.
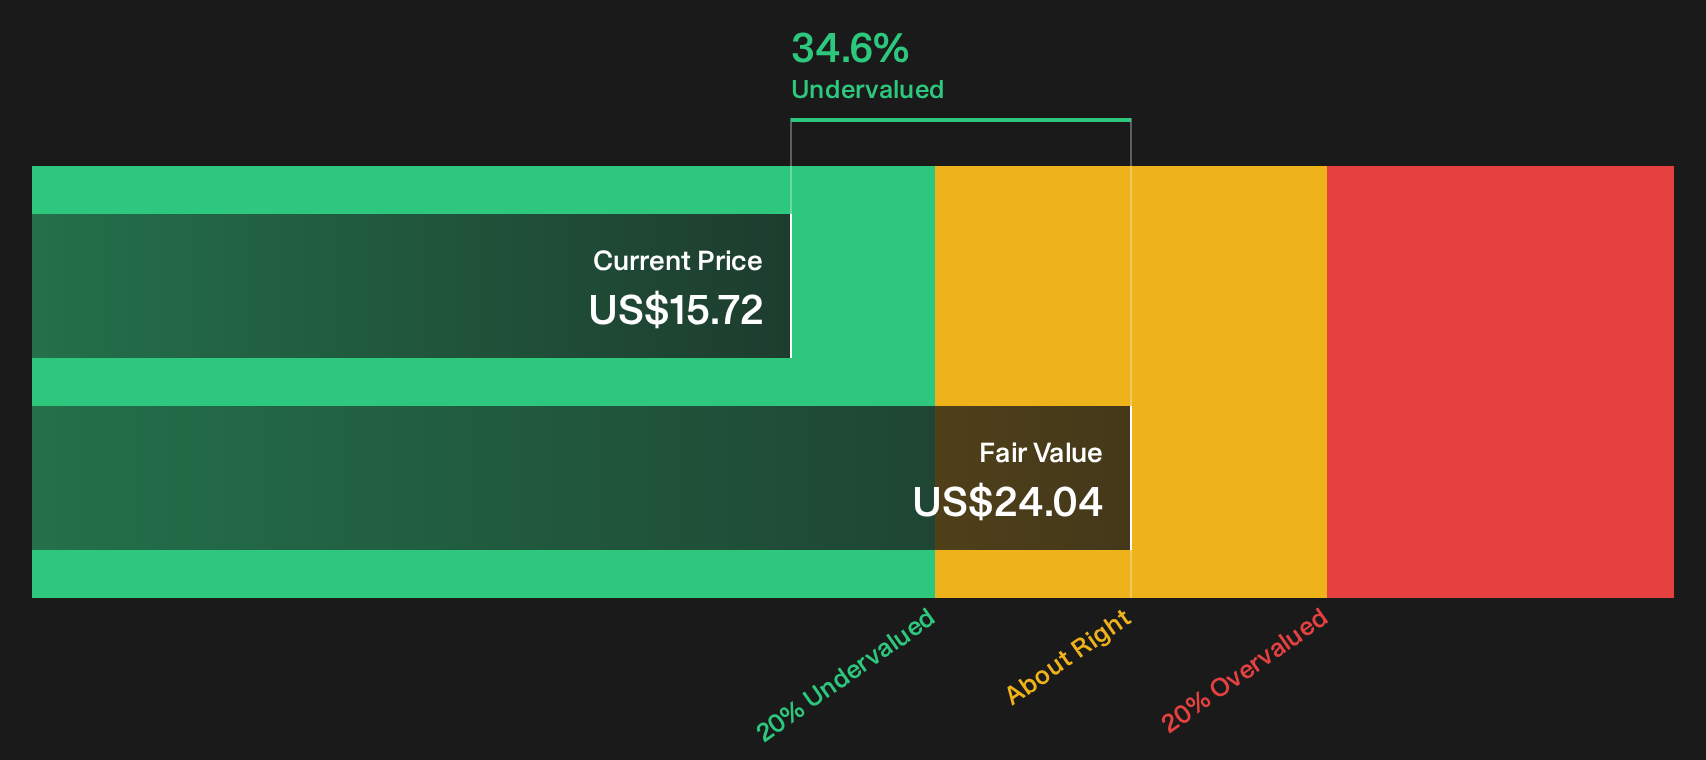
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PagerDuty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages across PagerDuty’s narratives can be useful if you move quickly, compare the data points yourself, and build an independent thesis using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PagerDuty?
If PagerDuty has you rethinking your watchlist, do not stop there. Broaden your opportunity set and stress test your thesis against other well filtered options.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that keep financial risk in check.
- Hunt for mispriced potential by reviewing the 20 high quality undiscovered gems that pair strong business quality with limited market attention.
- Dial back volatility and focus on capital preservation by checking the 29 resilient stocks with low risk scores that screen for stronger risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com