
Quanta Services (PWR) Looks Fairly Valued On Its Baird Conference Narrative
Quanta Services (PWR) heads into its Baird 2026 Global Industrial Conference appearance in Chicago with investor attention firmly on how management frames demand for power infrastructure, data centers, and renewable projects.
Quanta Services shares trade at US$606.16 after a sharp 19.1% 7-day share price gain, even though the 30-day and 90-day share price returns are both down around 12% and 11.6%. The year-to-date share price return of 37.9% and 1-year total shareholder return of 42.1% sit on top of very large 3-year and 5-year total shareholder returns. This sets a high bar for how management talks about future opportunities at the Baird conference and may explain why recent moves look more like investors recalibrating growth expectations than a major shift in risk appetite.
Spot similar power grid and data center momentum stories by scanning the hand-picked 43 power grid technology and infrastructure stocks that sit in the same theme as Quanta Services.Quanta Services is now back near record territory after a sharp weekly jump and a softer few months. For fresh money, does it make more sense to lean in here or wait for a cooler entry before the numbers are weighed?
Most Popular Narrative: 2% Undervalued
Quanta Services closed at $606.16, while the most-followed valuation narrative on Simply Wall St flags a fair value of $620 that uses an 8.98% discount rate and implies only a small gap between price and value according to Andrei_Niculescu, an investor in the Simply Wall St Community who wrote the narrative.
Quanta is the labour and execution bottleneck of the power build-out. It self-performs about 85% of its work, added about 26,000 employees in 2026 (about 12,000 organic), and is the counterparty utilities and hyperscalers use to turn capex into energised megawatts. It sits upstream of stocks like AEP’s 765 kV programme, GE Vernova’s turbines and the large-load interconnections behind CEG and VST. The business is excellent. The question is price.
See why 0 investors see Quanta Services as 2% undervalued.
Result: Fair Value of $620 (ABOUT RIGHT)
Still, the Quanta Services story could be knocked off course if hyperscaler data center spending cools, or if copper and grid equipment supply tightens materially.
Find out about the key risks to this Quanta Services narrative.
Another View: Quanta Services Through The P/E Lens
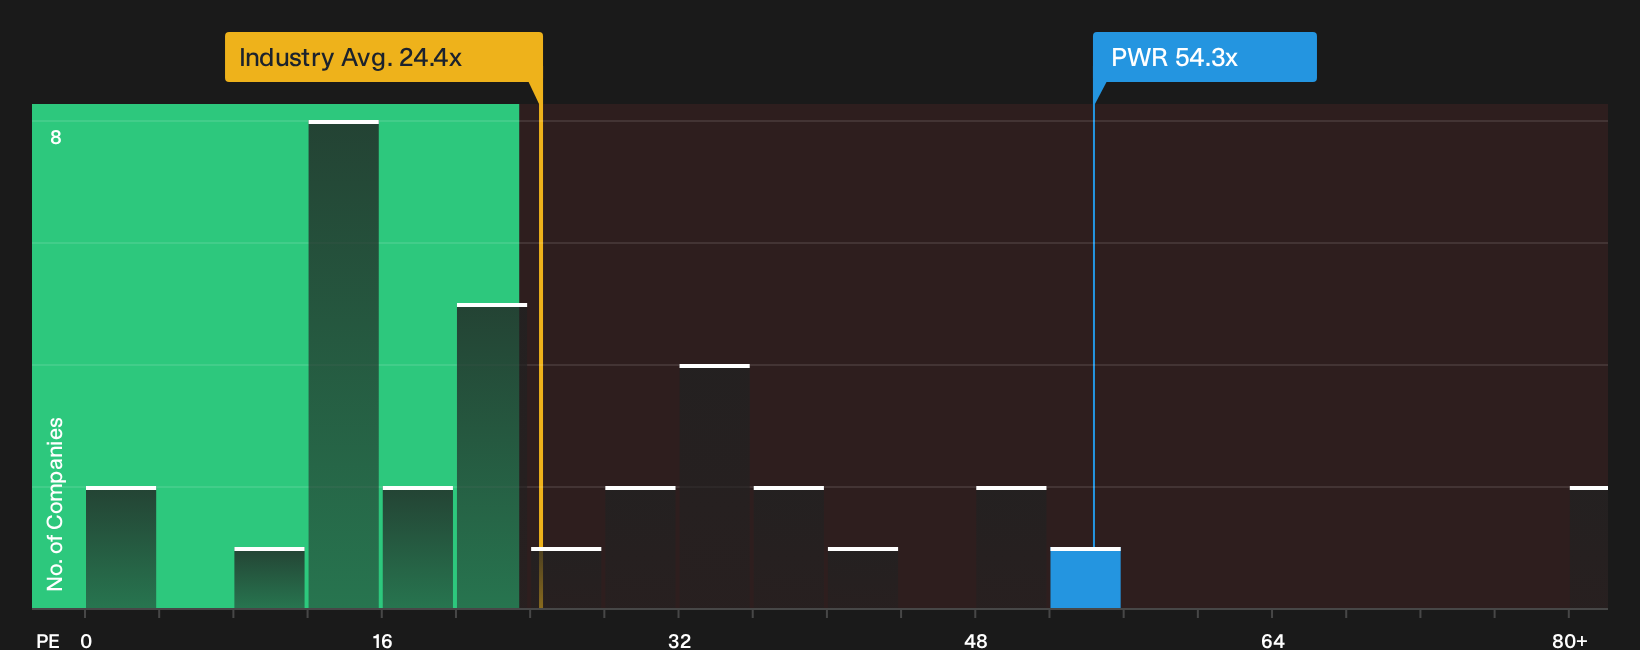
Quanta Services may look close to fairly priced on that US$620 narrative fair value, but the P/E picture tells a harsher story. The stock trades on a 54.3x P/E, while the estimated fair ratio sits at 38.6x and peers are around 22.5x, which points to a rich tag and meaningful derating risk if growth cools.
That kind of gap means you are paying a clear premium over both the Construction industry and similar companies, with limited room for any stumble before the multiple becomes a pressure point rather than a support. The key question is whether you believe Quanta Services has the durability to keep justifying such a stretch multiple over time or whether it makes sense to focus on cheaper peers instead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Quanta Services leaves you on the fence, act quickly, review the numbers, and evaluate the narrative against your own risk tolerance alongside the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Quanta Services?
If Quanta Services already feels tightly priced, broaden your opportunity set now by scanning high conviction lists where quality, value, and resilience come through the data.
- Target potential mispricing by reviewing the 32 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their underlying strength.
- Boost your income playbook by checking the 6 dividend fortresses built to spotlight companies offering higher yields with supporting financial profiles.
- Protect your downside by focusing on the 29 resilient stocks with low risk scores that score well on balance sheet strength and overall risk factors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com