
Does First R And D Day Change The Bull Case For Teva (TEVA)?
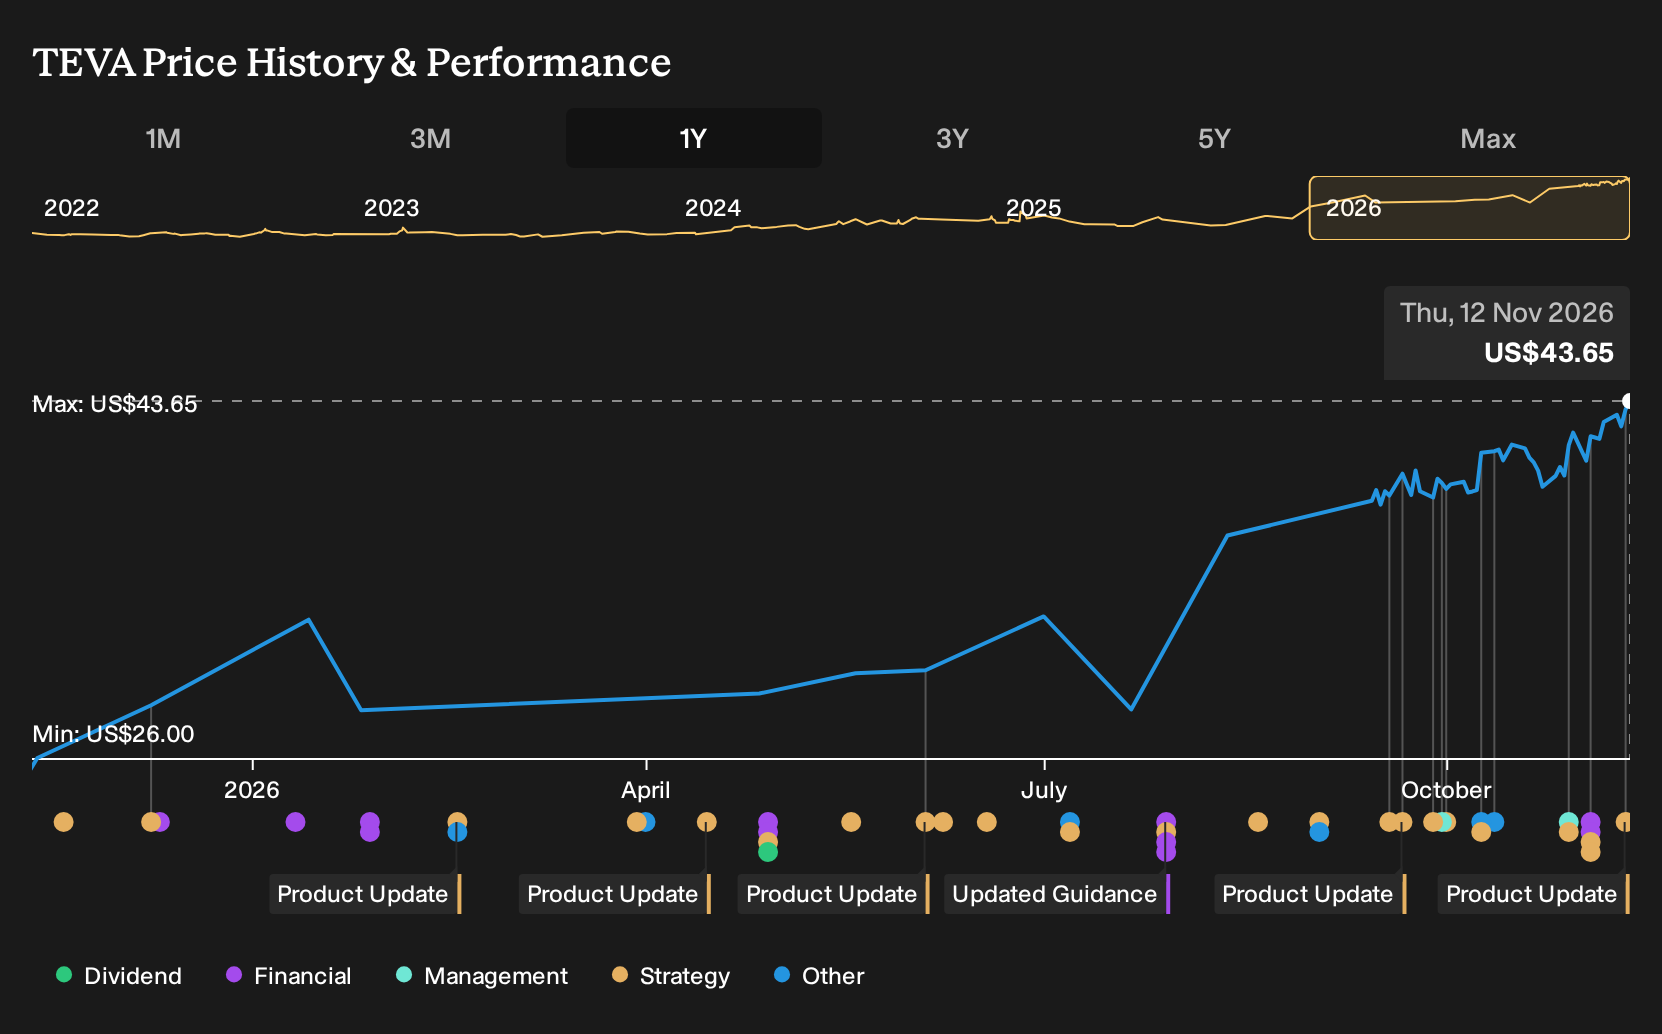
- Teva Pharmaceutical Industries used its first R&D Day to outline a shift toward higher value medicines, highlight progress across late stage and early stage drug programs, and update investors on commercial and financial capacity to support this next wave of products.
- The company reinforced how in house antibody discovery and accelerated development paths, such as WELTRUZA moving directly from Phase 1 to Phase 3, are reshaping its mix toward branded therapies with a growing late stage pipeline.
- The next focus will be on how Teva Pharmaceutical Industries' first R&D Day pipeline update could influence the existing investment narrative.
Compare Teva Pharmaceutical Industries' R&D pivot with hand picked peers by scanning 20 high quality undiscovered gems that are quietly building drug pipelines with strong fundamentals.
Teva Pharmaceutical Industries Investment Narrative Recap
To own Teva Pharmaceutical Industries today, you effectively need to buy into the Pivot to Growth story. That means believing the shift toward higher value CNS and immunology drugs and a larger late stage pipeline can matter more over time than current low net margins and the pressure from debt that is not yet well covered by operating cash flow.
The near term swing factor is execution on the launch queue and R&D plan that the analyst consensus Narrative on Simply Wall St already ties to higher future earnings. Recent R&D Day data and pipeline progress look directionally supportive of that roadmap. The biggest immediate risk stays the same: heavy investment, impairments and clinical or regulatory setbacks could keep profitability thin even as revenue guidance edges higher.
The R&D Day update is probably the single most relevant recent announcement for this story. Teva Pharmaceutical Industries laid out a deeper late stage and early stage portfolio, including anti IL 15 in celiac disease, TEV 408 in vitiligo, ATTENUKINE in cancer and next generation antibodies for asthma and inflammatory bowel disease, all alongside in house discovery capabilities.
These disclosures matter because they link directly to the catalysts analysts already focus on: a multiyear launch queue in CNS and immunology, a rising contribution from branded therapies and management targets for higher gross margin and operating margin. The same update also highlighted that revenue from newer medicines has more than doubled and that several assets, such as WELTRUZA moving straight into Phase 3 and ecopipam under FDA priority review, are already testing Teva’s ability to deliver on that plan.
Teva Pharmaceutical Industries' current earnings of US$506.0 million are projected by analysts to reach US$3.0b by 2029. This implies an increase of about US$2.5b, while revenue is expected to reach US$18.6b in the same year off a forecast 2.6% yearly rise in sales.
Discover how Teva Pharmaceutical Industries' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$48.9 to US$67.1, so the highest figure sits more than a third above the lowest. These private investors are weighing Teva Pharmaceutical Industries' R&D updates, rising guidance and heavier impairments very differently. Use that spread as a prompt to review multiple viewpoints before forming your own stance.
Explore another Teva Pharmaceutical Industries fair value estimate, including one that suggests as much as 54% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your Teva Pharmaceutical Industries research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Teva Pharmaceutical Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Teva Pharmaceutical Industries' overall financial position at a glance.
Looking For More Investment Ideas Beyond Teva Pharmaceutical Industries?
Once you have formed a view on Teva Pharmaceutical Industries, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener lets you scan for stocks that match your preferred mix of financial strength, valuation and income potential, so you can build a watchlist that really reflects your own approach.
- If you want resilient businesses that aim to keep downside risk in check, start with a short list of 29 resilient stocks with low risk scores that already clear strict quality filters.
- Income focused investors can look for durability first and yield second by reviewing a hand picked set of 6 dividend fortresses that combine higher payouts with supporting fundamentals.
- For those hunting for mispriced potential, broaden your opportunity set with a curated pool of 32 high quality undervalued stocks that pair solid financials with room for sentiment to catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com