
Did French Restructuring Just Shift Coty's (COTY) Investment Narrative?
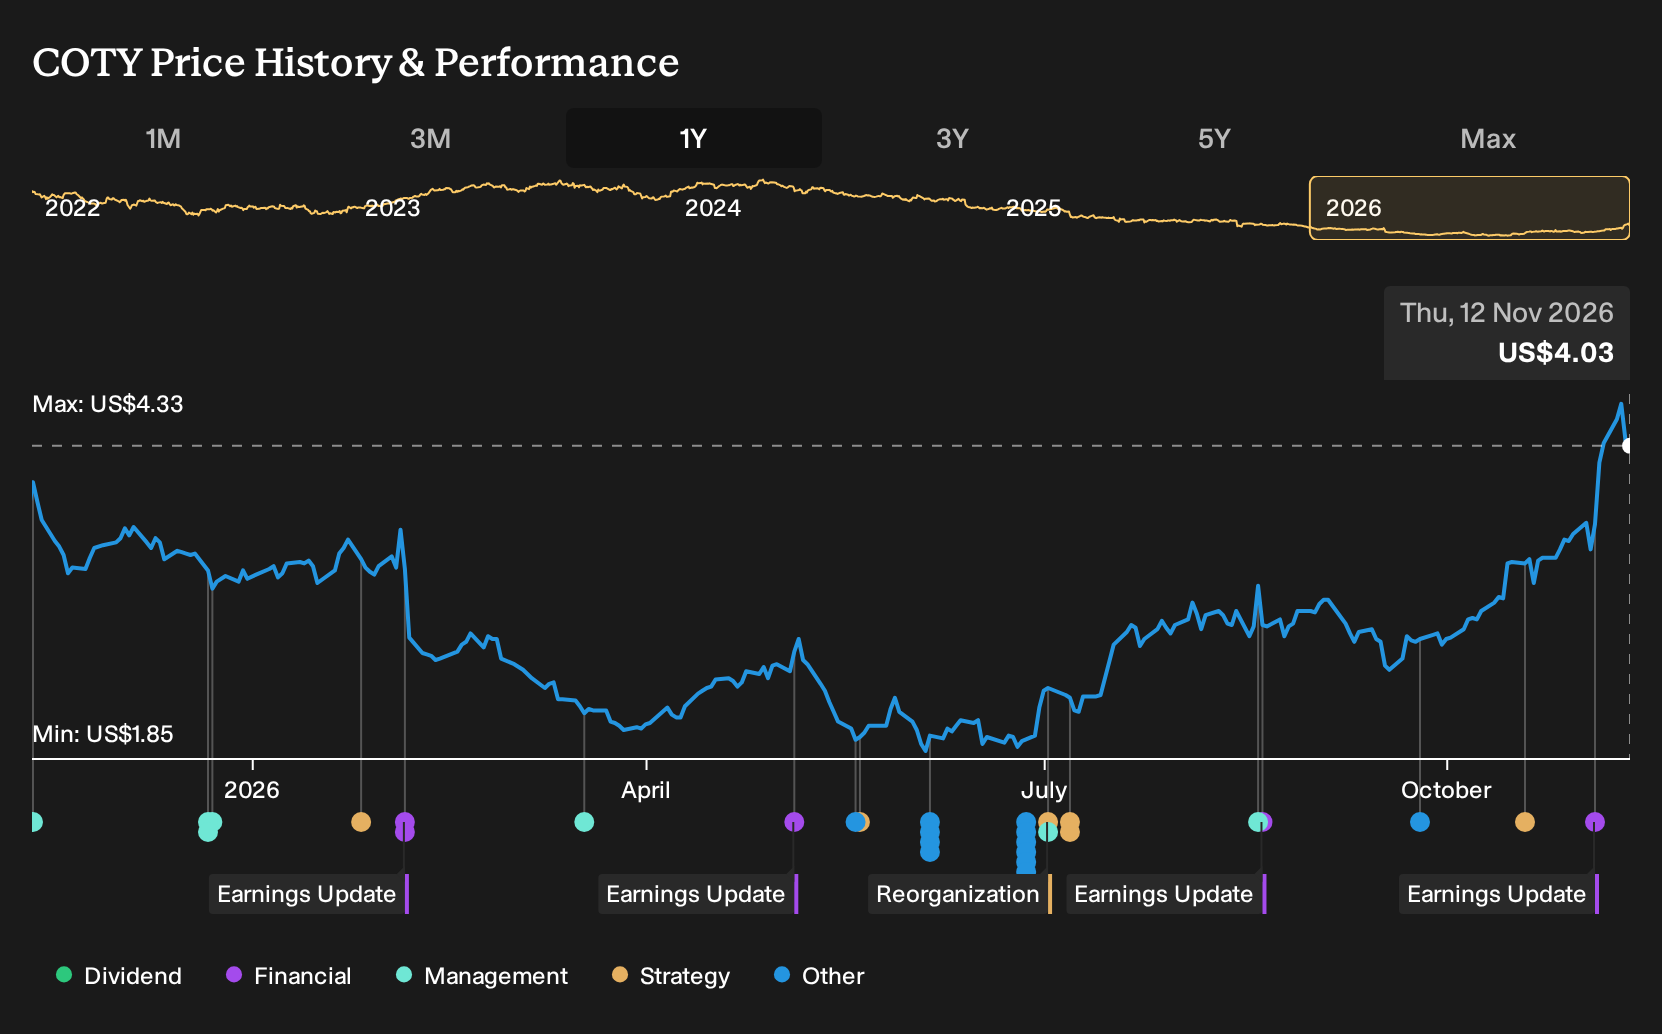
- Coty reported first quarter 2026 sales of US$1,555.2 million and net income of US$109.5 million, alongside a proposed restructuring of its French beauty operations that could result in about 155 job cuts.
- The 40 year extension of Coty’s Marc Jacobs license, with a push into makeup alongside fragrances, reflects a long term tilt toward prestige beauty as the broader organization is reshaped and simplified.
- We will look at how Coty’s investment narrative is influenced by the long term Marc Jacobs license extension and French restructuring.
Scan how Coty’s prestige tilt compares with peers by zeroing in on hand picked beauty and consumer names with resilient balance sheets through our list of solid balance sheet and fundamentals (23 results)
Coty Investment Narrative Recap
To be comfortable owning Coty, you need to believe the prestige pivot can offset pressure in mass beauty and that cost programs translate into steadier earnings. The latest quarter hints at that balance. Sales were US$1,555.2 million, slightly below last year, while net income rose to US$109.5 million, so execution rather than demand swings remains the focus.
In the near term, the key catalyst is whether Coty can stabilise like for like trends and protect margins as it simplifies the portfolio, in line with the analyst consensus Narrative on Simply Wall St. The biggest risk is ongoing share loss in growing categories, especially as French restructuring and SKU cuts carry near term disruption risk if retailers or consumers do not transition smoothly.
The 40 year extension of the Marc Jacobs license looks central to this story. It locks in a prestige pillar across fragrance and makeup at the same time Coty is preparing for the Gucci Beauty exit and reviewing its French operating model. That matters because prestige resilience is one of the main offsets cited to future Gucci related profit pressure.
For catalysts, the Marc Jacobs agreement sits alongside Coty.Curated, Color the Future and the All in to Win savings plan. Together, they frame a path where fewer, larger launches and fixed cost cuts aim to counter volume softness and the planned Gucci license termination. The operational test from here is simple. Coty needs to turn these programs into cleaner inventory, steadier gross margins and a less volatile earnings base.
Coty's narrative projects US$5.6b revenue and US$266.7 million earnings by 2029. This assumes revenue decreases by 1.2% per year and an earnings swing of about US$843.1 million from a loss of US$576.4 million today.
Uncover how Coty's fair value indicates a 26% potential downside to its current price, suggesting that the current premium may not hold.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Coty’s cost story rather than prestige growth. Before this French restructuring and Marc Jacobs license extension, the bullish narrative was built on over US$1b of savings and a path to about US$6.1b revenue and US$332.7 million earnings by 2029. That is a very different tone to consensus, and these new announcements may push both views to shift.
Explore 4 other Coty fair value estimates, including one that suggests as much as 143% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Coty research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Coty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coty?
Once you have a view on Coty, it helps to widen the lens and compare it with other businesses that match your preferred balance of quality, risk and income. The Simply Wall St Screener gives you quick ways to surface focused shortlists rather than scrolling through hundreds of tickers with no structure.
- If you care most about financial resilience, start with companies screened for stronger balance sheets and consistent fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Investors hunting for mispriced quality can look at opportunities where fundamentals and valuation filters line up by reviewing the 32 high quality undervalued stocks.
- If steadier income streams are your priority, focus on businesses with higher yields and robust payout support using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com