
Seiko Group And 2 Japanese Undervalued Stocks To Watch
With the Japanese yen pushing past the 160 per dollar mark and officials openly preparing to step in again, currency swings are throwing prices of many Tokyo listed companies out of their usual rhythm. That kind of distortion can leave high quality, cash generative businesses trading at a discount. This article identifies three such Japanese stocks that score well on balance sheet strength and value, and explains why they merit a closer look now.
The three stocks covered next are just a sample, and the full screen surfaced 15 more Japanese companies with similar cash generation, balance sheet strength and value signals that are not discussed here.
If you want to identify and analyze that wider group for yourself, head straight to the High Quality Undervalued Stocks screener.
Seiko Group (TSE:8050)
Seiko Group is a diversified Japanese manufacturer best known for its premium Grand Seiko and King Seiko watches, alongside devices, printers, IoT solutions and retail operations. The stock is valued at about ¥677.8b, with the high end watch lines linking it directly to the high quality, cash generative theme.
Seiko Group fits a High Quality Undervalued Stocks screen because premium watches generate steady cash flow and the stock trades below an estimate of its future cash stream. Earnings and revenue forecasts point to solid growth potential, although margins and valuation will hinge on how one unseen pressure in its luxury watch mix evolves.
That mix pressure is exactly what the DCF valuation analysis for Seiko Group is built to unpack so you can see where valuation and cash generation might be decoupling.
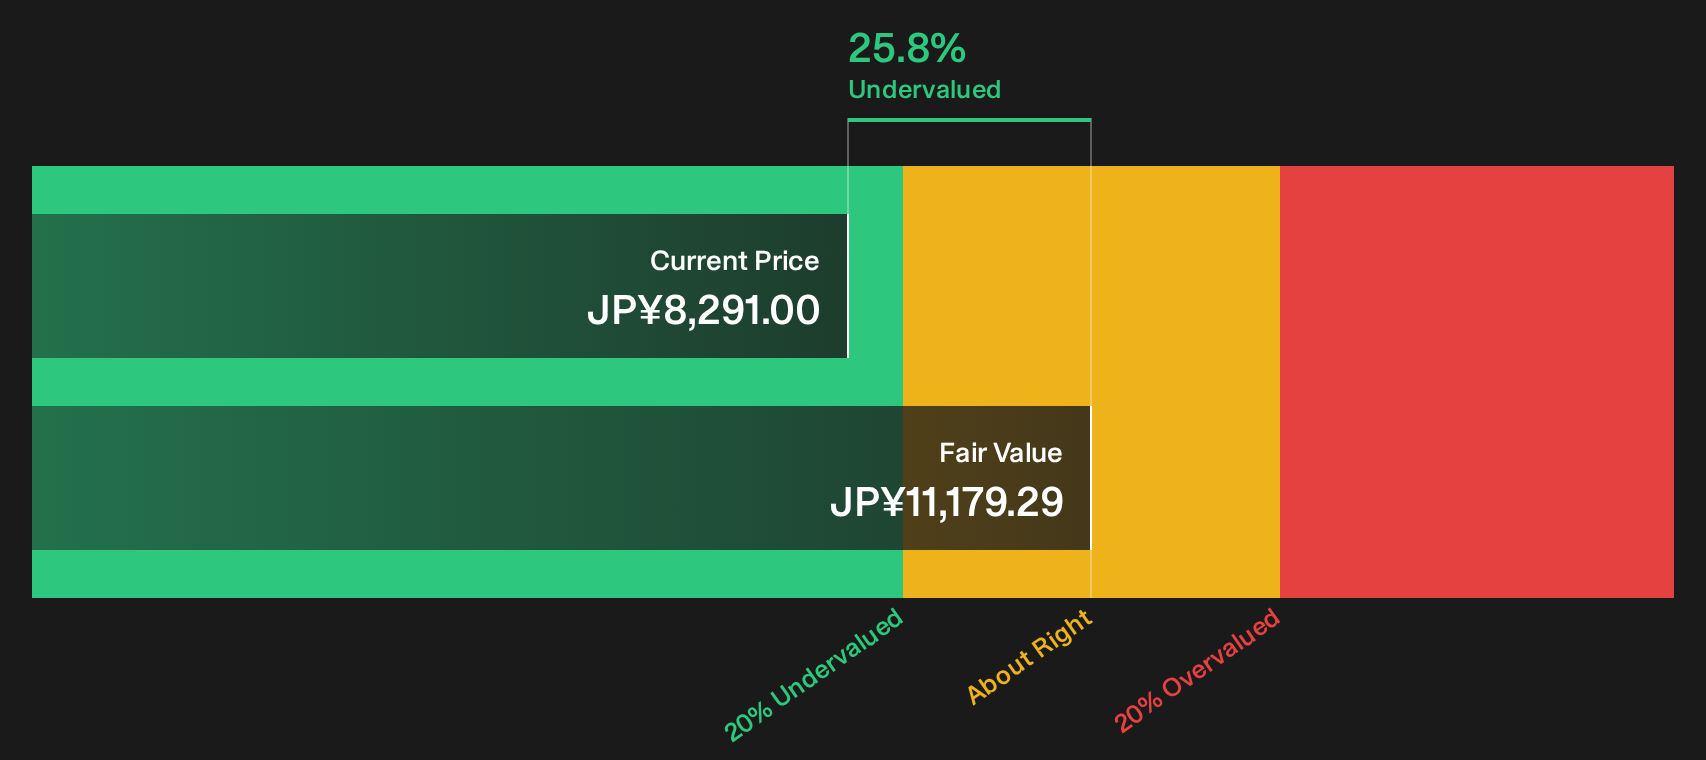
MTG (TSE:7806)
MTG focuses on health, beauty and wellness devices such as ReFa beauty tools and SIXPAD training gear, where branded gadgets can support steady cash generation. The group is valued at about ¥300.4b. Investors watching this kind of cash flow profile will care how one quiet shift in consumer demand plays out.
That quiet shift is exactly where the analysis report for MTG can show whether MTG’s cash engine is accelerating or consumer fatigue is starting to creep in.

GMO Payment Gateway (TSE:3769)
GMO Payment Gateway runs payment rails that let merchants accept cards, bank transfers, convenience store payments and digital wallets. Its multi payment service and GMO PG platform generate most of its ¥67.9 billion payment processing revenue, alongside smaller money service and enhancement units, and a market value near ¥655.2 billion.
GMO Payment Gateway matches the High Quality Undervalued Stocks theme through a cash rich payment platform that some value models price at about one third below estimated future cash flows. Earnings and revenue forecasts indicate faster growth than the broader Japanese market, which leaves plenty riding on how one unseen pressure in this fee based engine develops.
How that hidden pressure plays out is exactly what the 5 key rewards and 1 important warning sign explains, so you can see where GMO Payment Gateway’s upside might be capped or still underappreciated.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout trends, early momentum and stocks still flying under the radar for now do not stay quiet for long, so get in early.
- Track income machines that aim to keep paying investors through thick and thin by using the 27 dividend fortresses while yields still look compelling.
- Spot future infrastructure winners powering AI growth by scanning the 53 AI infrastructure stocks before these enablers are fully captured by mainstream screens.
- Hunt for under the radar cash generators in the list of solid balance sheet and fundamentals (25 results) before stronger balance sheets attract broader momentum-chasing capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com